Yagi Studio/DigitalVision via Getty Images
CEVA (NASDAQ:CEVA), a licensor of IP for wireless connectivity technologies, smart sensing and other solutions, got somewhat of a scare on May 9 with the release of the latest earnings report, which included, among other things, a top and a bottom line that were well below expectations. The stock dropped big by more than 10% at one point and CEVA came within an inch of falling below the support provided by an existing trendline, only to recover with more modest losses. Why will be covered next.
Why the stock has a decision to make
A previous article from last February took notice of a recently released financial model from CEVA, which called for strong growth in the coming years. This, along with improved earnings, helped power a rally in the stock at the time, which included a 21.4% jump immediately after the release of the Q4 FY2023 report. Still, CEVA was rated a hold and not a buy after taking into account other aspects. The stock, for instance, had underperformed for quite some time and that could continue if earnings saw renewed pressure due to, for instance, geopolitical trade issues.
Source: Thinkorswim app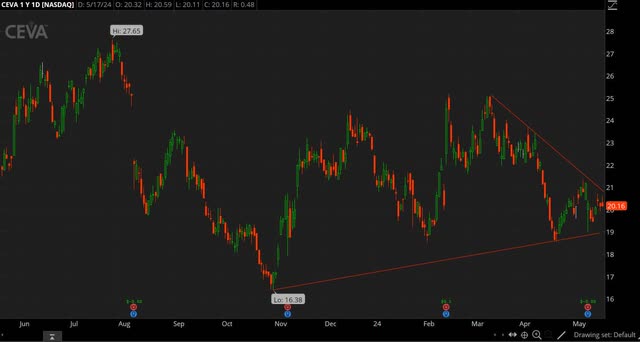
The chart above shows why not buying into the rally last February proved to be justified because the stock has faded since then. The stock hit a 2024 high of $25.19 a few days after the aforementioned article was written, but there have been no new highs since February 15. On the contrary, the stock has gradually declined after closing at $20.16 on May 17. CEVA is currently down 11.2% YTD in what has been a year of gains for the sector CEVA finds itself in.
The overall direction of the stock since the October bottom is still leaning towards higher prices, but that may change in the near future. Note how the stock has respected the boundaries imposed by the ascending and the descending trendline as shown in the chart, but this cannot continue since the trendlines are on a collision course. The stock will have to break through the upper trendline, or alternatively, through the lower trendline.
Both bulls and bears may want to hold off on placing bets due to the above. If the former, then a break above the upper trendline would be preferable. If the latter, then a break below the lower trendline would be preferable. Regardless, the stock has a decision to make since the current action cannot continue for long.
Why the stock sold off after the latest report from CEVA
The chart shows another thing. The stock fell and came close to breaching the lower ascending trendline on May 9, which happens to be the day CEVA released its most recent quarterly report, a Q1 FY2024 report which fell short of estimates. The consensus expected non-GAAP profit of $0.03 a share on revenue of $23M, but CEVA reported a loss of $0.05 on revenue of $22M. The table below shows the numbers for Q1 FY2024.
In terms of GAAP, CEVA posted a net loss of $5.45M or $0.23 per share. Royalty revenue contributed $10.7M, up 33% YoY, but this was offset by licensing & related revenue declining by 37% YoY to $11.4M. Keep in mind that CEVA has disposed of Intrinsix, which is excluded in the numbers for continuing ops. CEVA finished Q1 FY2024 with cash, cash equivalents, marketable securities and bank deposits of $159M with no long-term debt on the balance sheet.
|
(Unit: $1000, except EPS) |
|||||
|
(GAAP) |
Q1 FY2024 |
Q4 FY2023 |
Q1 FY2023 |
QoQ |
YoY |
|
Revenue |
22,072 |
24,162 |
26,262 |
(8,65%) |
(15.95%) |
|
Gross margin |
89% |
91% |
87% |
(200bps) |
200bps |
|
Operating income (loss) |
(4,960) |
(2,787) |
(2,620) |
– |
– |
|
Net income (loss) |
(5,448) |
3,769 |
(4,872) |
– |
– |
|
Net income (loss) from continuing ops |
(5,448) |
(8,098) |
(2,699) |
– |
– |
|
EPS |
(0.23) |
0.16 |
(0.21) |
– |
– |
|
EPS (continuing ops) |
(0.23) |
(0.34) |
(0.12) |
– |
– |
|
(Non-GAAP) |
|||||
|
Gross margin |
90% |
92% |
88% |
(200bps) |
200bps |
|
Operating income (loss) |
(831) |
1,946 |
1,156 |
– |
– |
|
Net income (loss) |
(1,259) |
2,378 |
107 |
– |
– |
|
EPS |
(0.05) |
0.10 |
0.00 |
– |
– |
Source: CEVA
Shipments increased by 25% YoY to 371M units, which explains the increase in royalties. Bluetooth shipments accounted for the majority with 202M units, followed by handsets with 61M units. Wi-Fi shipments outperformed with an increase of 50% YoY to 31M units. CEVA signed 11 licensing deals in Q1 FY2024, including two with first-time customers.
CEVA is behind, but it is sticking to its prior outlook
CEVA missed expectations, which is why management added some color as to why. A number of licensing agreements expected to be completed in the quarter were delayed. Nevertheless, CEVA seems to believe it can make it up later in the year because CEVA is sticking with its prior FY2024 outlook given earlier in the year, which calls for FY2024 revenue to grow by 4-8% YoY. From the Q1 earnings call:
“In licensing, the first quarter was challenged with a few licensing agreements delayed until later in the year, but overall the quality of the licensing deals signed and the overall demand for our next-generation IPs is very encouraging. We have the portfolio of technologies that meets some of the critical pain points of semiconductors and OEMs for their smart edge roadmaps and I am confident that we can meet our total revenue target for the year and we have built a healthy backlog which reinforces my belief on this. Overall, I remain very positive that 2024 will be a growth year for CEVA and will set us up to reach our longer-term revenue, margin and profitability targets.”
Source: CEVA earnings call
Quarterly guidance calls for Q2 FY2024 revenue to grow by 6-16% QoQ, which implies revenue of $23.4-25.6M. Non-GAAP gross margin is expected to be similar to the preceding quarter at 90%.
“Now for the guidance of the second quarter of 2024. As Amir stated earlier, we have signed a number of deals at the start of the second quarter, and also have good visibility into the second quarter potential deal flow for our wide range of technologies and markets. On royalties, we expect year-over-year growth in the second quarter and are monitoring the timing of new product introductions from our customers. All in all, we forecast sequential growth in overall revenues for the second quarter of 6% to 16%, primarily from licensing.
Gross margin is expected to be similar to the first quarter, approximately 88% on a GAAP basis and 90% on a non-GAAP basis, excluding an aggregate of $0.2 million of equity-based compensation expenses and $0.1 million for amortization of acquired intangibles.”
Using these guidelines from CEVA, Q2 FY2024 non-GAAP EPS is estimated at $0.03, assuming revenue comes in at the midpoint of guidance.
If we assume CEVA grows by 4-8%, then FY2024 revenue would end up at $101.3-105.2M. This is estimated to result in non-GAAP EPS of $0.28-0.32 in FY2024, which is better than FY2023’s EPS of $0.10, but far behind FY2022’s EPS of $0.78. Keep in mind that CEVA is buying back shares, and this and other factors could sway the final number. This translates to a non-GAAP P/E ratio of 67.2x, with the stock at $20.16 and EPS of $0.30.
Remember that CEVA expects growth to continue in the coming years, as laid out in the most recent Investor Presentation. The presentation saw a CAGR of 8-12% in FY2023-2027, which would result in revenue of $142.6M and non-GAAP EPS of $1.00 in FY2027. Apply a P/E multiple of 82x, the average for the last five years, and you end up with a stock price of $82 for CEVA. In other words, a quadrupling of the current stock price.
Could China be a headwind for CEVA?
It’s worth mentioning that China contributed $13.6M to Q1 FY2024 revenue of $22.07M for a 62% share. In comparison, China contributed $17.8M to $Q1 FY2023 revenue of $26.26M for a 68% share. Simply put, if not for China, the numbers could have looked much better. China sales dropped by $4.2M YoY, equal to the total decline in sales of $4.19M.
There is reason to believe this may not be a one-off event, but something that has legs to it. That is because companies in China are increasingly looking to rely on homegrown IP due to the risks of relying on outside IP that could be cut off due to U.S. government restrictions, something that has increasingly been the case in recent years, especially in the case of specific companies.
Huawei, for example, is seeing a resurgence in sales and in many instances gains are coming at the expense of companies that license IP from CEVA. This is the case in, for example, the market for 5G RAN equipment where Huawei is outperforming Nokia, a customer of CEVA. Huawei also has its own cellular modems for handsets, which means that if Huawei smartphones regain the market share lost in past years, primarily due to losing access to U.S. tech, in China or elsewhere, CEVA stands to be affected. There are many other examples.
Huawei and other Chinese companies are also looking to develop their own tech standards, especially after the start of the tech war between the U.S. and China, which could eventually result in lost sales for CEVA. This includes competing standards to Wi-Fi and Bluetooth, both of which are important to CEVA as shown earlier by the shipment data. If China relies more on its own IP, it will need less IP from CEVA. So the recent weakness may just be the start of something long term.
Investor takeaways
CEVA managed to rally earlier in the year with an outlook that called for growth in 2024 and in the following years, but CEVA is behind after the Q1 FY2024 report fell short of expectations. If CEVA is to grow in FY2024 as called for at the start of the year, it will have to do better than what it delivered in the most recent report.
The stock sold off after the Q1 FY2024 report, but losses were tempered by CEVA sticking with its FY2024 outlook, which suggests CEVA believes it can make it up in the rest of the year. This is important because the stock could multiply in value, assuming CEVA hits the targets laid out in a recent presentation. This includes going from EPS of $0.10 in FY2023 to more than $1.00 in FY2027, a 900% increase.
Still, the fact that licensing agreements are delayed is not an encouraging sign. CEVA trades at high multiples and for this to be justified, the company needs to show strong growth. CEVA trades like a high-growth stock, but growth has been lacking. Growth is expected to accelerate in H2 FY2024, but there is not much of it thus far. CEVA is actually behind after a weak start to the year.
The charts suggest CEVA is consolidating before the next move. The stock has posted a series of lower highs and higher lows, which cannot continue indefinitely. The stock actually came close to falling below support after the latest report, but it recovered in time. This can be seen as a good sign after a disappointing report, although it would be premature to say the coast is clear, since the possibility of breaking support by falling below trendlines is still there. Taking chips off the table may prove worthwhile since any bets, long or short, could go against you if the stock moves in the opposite direction expected.
I am neutral on CEVA with the stock in a holding pattern, which could be resolved in the not so distant future, up or down. The prudent thing would be to wait for further clarity by waiting to see in which direction the stock is heading. For CEVA to stick with its prior outlook is a sign of confidence, but that does not mean one should ignore the actual results. China seems to be giving CEVA problems and there is reason to believe more trouble could be brewing over there.
Bottom line, CEVA would be a buy if CEVA manages to hit its targets, but evidence CEVA is about to do just that is lacking. If future quarters resemble the latest one, targets may have to be revised. CEVA can still come from behind to hit its targets for the year and beyond, but that would require a leap of faith. While some may be willing to give CEVA the benefit of the doubt, odds are not everyone will be willing to do so.
Credit: Source link