
Luis Alvarez/DigitalVision via Getty Images
I am updating my previous analysis on Cardinal Health (NYSE:CAH) in light of Q4 and Full-Year 2024 earnings, which were released pre-market on Wednesday, August 14th.
I previously rated Cardinal Health a buy for the following reasons:
- Q3 earnings were strong with the company raising full-year guidance
- The OptumRx loss was a short-term blip with no change to the long-term investment thesis
- The specialty pharmaceutical business had the potential to drive even more growth than suggested by management
Since then, Cardinal Health has returned over 8% while the S&P 500 has returned close to 10%.
CAH Price Trend (TrendSpider)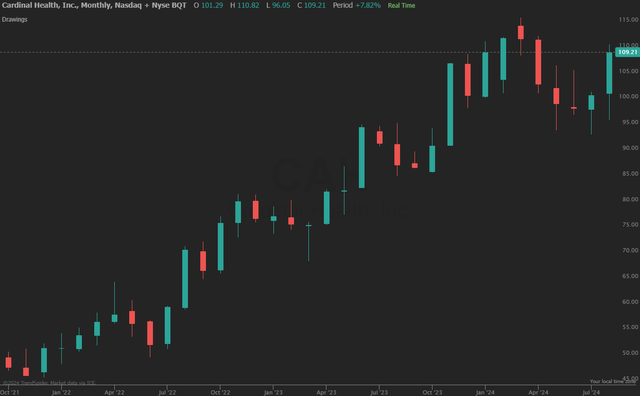
I continue to believe that Cardinal Health is a long-term value play, both because of price appreciation and the company’s increased commitment to shareholder returns. While 2025 guidance looks weak on the surface, the underlying pharmaceutical business is stronger than ever and will quickly turn this into a short-term blip. In addition, industry tailwinds continue to blow stronger in Cardinal Health’s core business.
There are certainly risks to consider that hold me back from a strong buy recommendation. Cardinal can’t afford to lose many more large contracts and cost pressures continue to remain strong. I believe the upside potential from the strong pharmaceutical business outweighs these risks and continue to rate Cardinal Health a buy at a price target of $128, 17% upside from today’s pricing.
Q4 Earnings Recap
Cardinal Health released Q4 2024 earnings pre-market on Wednesday, August 14th. Revenue of $59.87 billion beat consensus by $1.23 billion and EPS of $1.84 beat consensus by $0.11.
Q4 Earnings Summary (Seeking Alpha)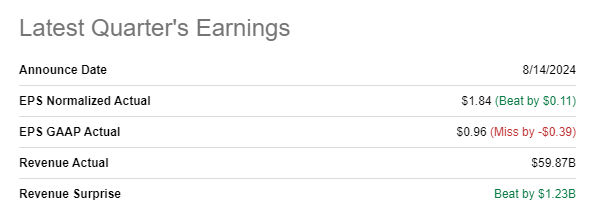
Revenue for the quarter was up 12%, and gross margin was up 5%. Revenue growth can be attributed to both the Pharmaceutical and Other Businesses, while margin growth can largely be attributed to margin expansion in the medical products segment.
CAH Q4 FY24 Financials (CAH Investor Relations)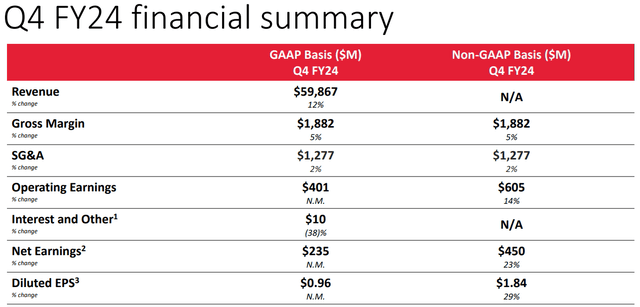
For the full-year, revenue was up 11% and margins were up a more impressive 8%. Revenue and margin drivers were similar to the quarter, continuing the trends across the year.
FY24 Full Year Financials (CAH Investor Relations)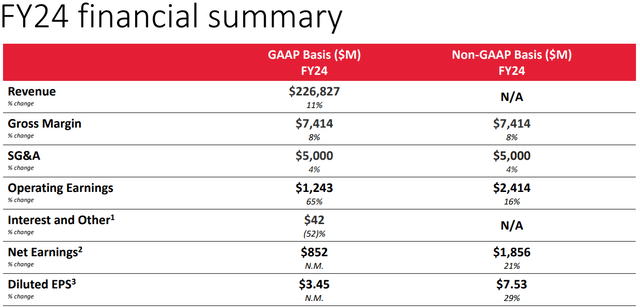
Cardinal Health had first released an FY25 outlook in Q3 following the OptumRx announcement. EPS was revised slightly up, interest was revised down, and share repurchases were revised up 50%. Guidance continues to be consistent with a short-term OptumRx impact, clearing out in the back half of the year.
FY25 Guidance (CAH Investor Relations)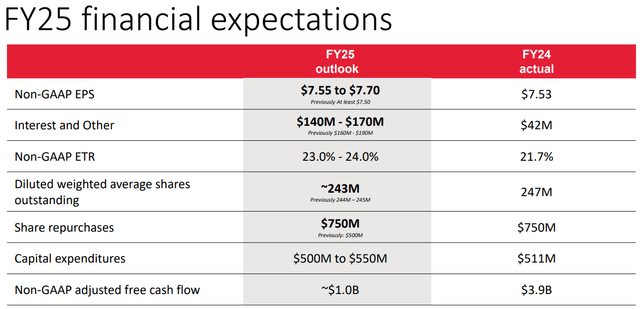
Overall, FY24 earnings were in line with my expectations, while the changes for FY25 exceeded them, especially on the profitability side.
Valuation
I updated my ongoing DCF analysis using the following assumptions:
- CAH delivers at the mid-point of management guidance, reasonable as CAH has raised guidance three times over the past year and 2025 guidance was in line with early read.
- Margins decline near-term as inflation levers have all been pushed, revenue growth is short of cost-growth
- 7% discount rate based on estimated WACC
- 3% long-run growth rate based on 5% market CAGR hedged down due to scale
This DCF analysis yields a price target of $128, in line with my prior price target and 17% upside from today’s prices.
CAH DCF Analysis (Data: SA; Analysis: Mike Dion)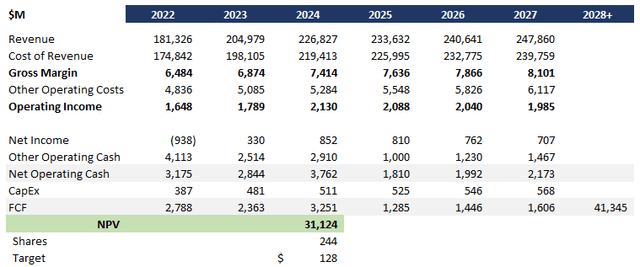
Wall Street has a slightly lower average price target at $116 or 6% upside, although my target of $128 still sits within the overall range of $101 to $137.
CAH Wall Street Rating (Seeking Alpha)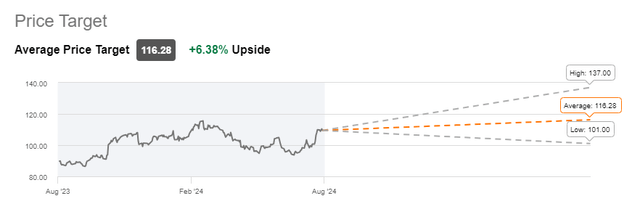
It is also worth noting that Cardinal Health has historically had very strong performance in the back half of the calendar year, making it a great time to add.
Trading Seasonality (TrendSpider)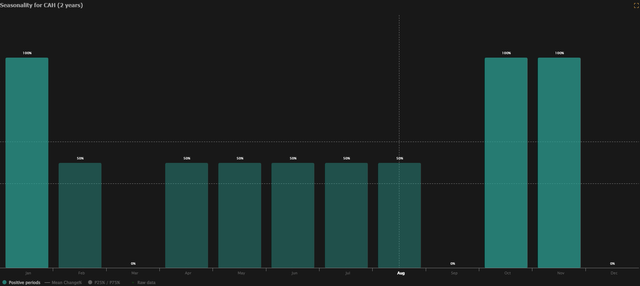
OptumRx and Inflation Are Priced In
Management seems to have a solid handle on the OptumRx impacts, especially as guidance ticks up the closer we get. While revenue will decline 4 to 6% in FY25, profit will grow which speaks to the strength of the business (and the lower margins of the deal Cardinal lost). Even better, management noted in the earnings call that the underlying pharmaceutical business, excluding OptumRx, is growing in the low-double digits.
FY25 Guidance – Pharmaceutical Segment (CAH Investor Relations)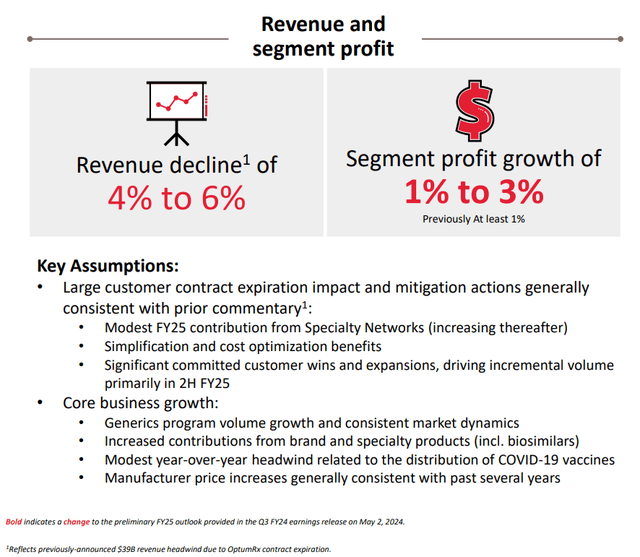
Inflation has been having a lagging effect on the healthcare industry, especially when it comes to skilled personnel. Cardinal Health will continue to see cost pressure in labor and supply chain. However, this is well priced into guidance, especially as inflation eased.
US Inflation Rate (Yahoo Finance)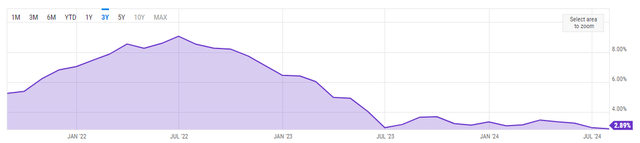
They have done a great job of managing S, G, & A, up only 4% for the year, with the biggest pressure coming through gross margin. Management has essentially guided flat margins net of OptumRx. I included 2ppt margin deterioration as a buffer for cost lag and still see 17% upside, so there is definitely room.
Industry Tailwinds Support Higher Valuation
The pharmaceutical industry, Cardinal’s core business, continues to see strong tailwinds across the globe. Worldwide pharmaceuticals are expected to grow at 4.71% through 2029, ahead of what I used in the valuation.
Global Pharmaceutical CAGR (Statista)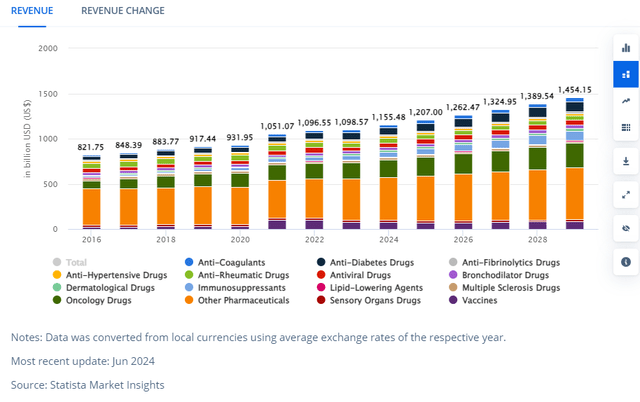
Even better for Cardinal Health, the specialty pharmaceutical market where they continue to innovate and drive share is expected to grow at a CAGR of 13.6%, well above both guidance and my DCF estimate. This provides a buffer for shortfalls in other parts of the business, and indeed management has called out this space as offsetting the margin losses from OptumRx.
Global Specialty Pharmaceutical CAGR (Technavio)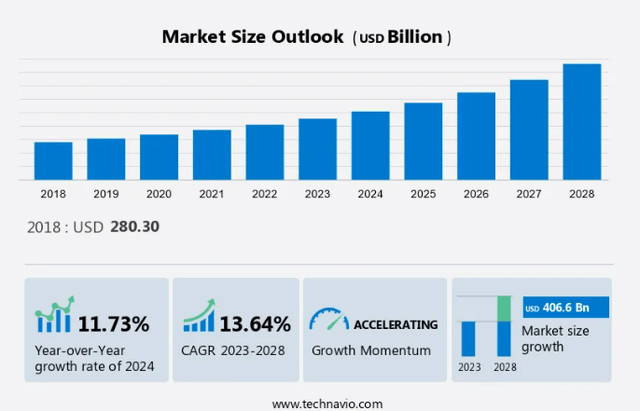
Downside Risk
The biggest downside risk for Cardinal Health is losing another major contract along the lines of OptumRx. Cardinal has pulled a lot of margin and growth levers to offset the impact, and it would be challenging to bounce back as quickly again.
The secondary risk is inflation accelerating again as Cardinal Health has pulled nearly every cost lever to grow margins, keep S, G, & A close to inflation and manage supply chain risks.
It is also worth noting that insider activity has been unfavorable throughout the month of August. I am not too concerned given the recent run-up in pricing and typical insider behavior in a run-up, but want to make sure you have the best information.
TrendSpider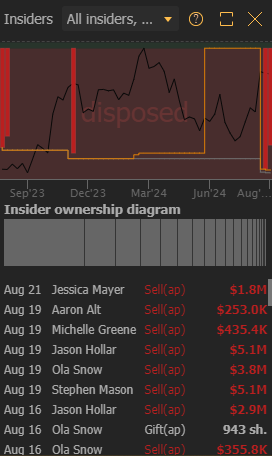
Verdict
I continue to be impressed by Cardinal Health’s growth strategy and ability to manage the cost base and unexpected events. Industry tailwinds bode very well for the business, especially in specialty pharmaceuticals, and provide a hedge against downturns in other areas of the business.
While there are risks if other major customers are lost or inflation begins rising significantly, they are mitigated by the strong upside potential of the core business.
I continue to rate Cardinal Health a buy at a price target of $128.
Credit: Source link