
JHVEPhoto
Thesis
Canadian Pacific Kansas City Limited (NYSE:CP) management has demonstrated in the past that they can drive growth and enhance operational performance. Following the combination of Canadian Pacific and Kansas City Southern, the company has truly transformed into a railroad business that can lead to strong shareholder returns in my view. Their unique assets, historic management execution, tailwinds and high valuation make CP a hold at these levels.
Introduction and Performance
CP operates in North America and is in my opinion, a well-run Class 1 railroad company. CP is now the combination of two railways, Canadian Pacific and Kansas City Southern, that was combined in April 2023. The combination of the two railway companies created the first and only rail operator that connects Canada, the United States and Mexico with a rail network of more than 20,000 miles. This combination was essentially Canadian Pacific acquiring Kansas City Southern for a total of $31bn, and the acquisition announcement was made in 2021. CP’s rail network is below indicating the span and connectedness across the continent that the company offers.
Canadian Pacific Kansas City Limited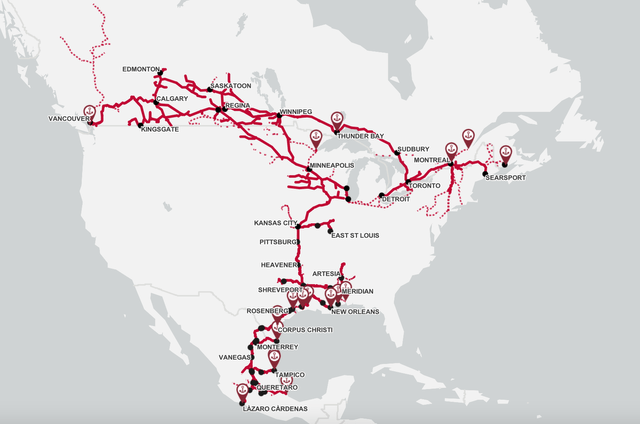
The creation of Canadian Pacific Kansas City Limited and the connectedness this offers was a smart move from CP’s management and in my opinion, is crucial in unlocking shareholder returns in the coming years. Given the debt that they had to raise to acquire Kansas City Southern management needs to stay disciplined in their capital allocation decisions and maintain good operational performance to capture industry tailwinds and unlock value for shareholders.
In my opinion, CP’s management has done a great job operationally for more than a decade. Looking at their metrics between 2011 and 2022 CP’s operational performance has improved materially.
Canadian Pacific Kansas City Limited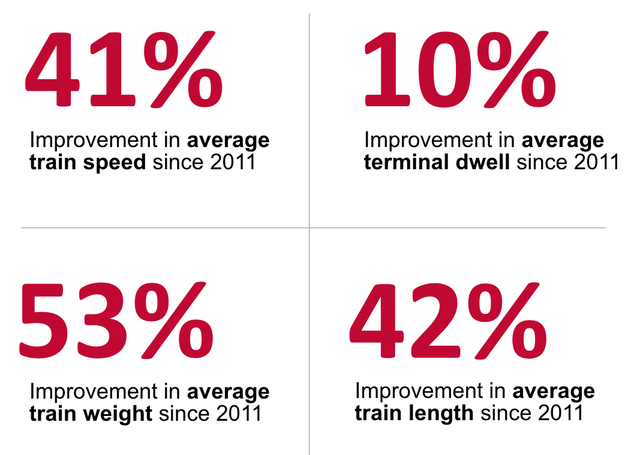
Why is this important for CP and railways in general? Railways are assets that can be flexed based on their operational efficiency, and this operational efficiency requires detailed planning and strong execution. Reducing average speeds by 41% and reducing the average dwell time by 10% means that assets are being utilized better, which reduces costs for the company. In addition, faster and longer trains mean that CP now has greater capacity and lower operating costs. A combination of their improved operational performance means greater productivity, lower costs and more flexibility to pursue growth opportunities. For shareholders, this translates to strong shareholder returns and market outperformance.
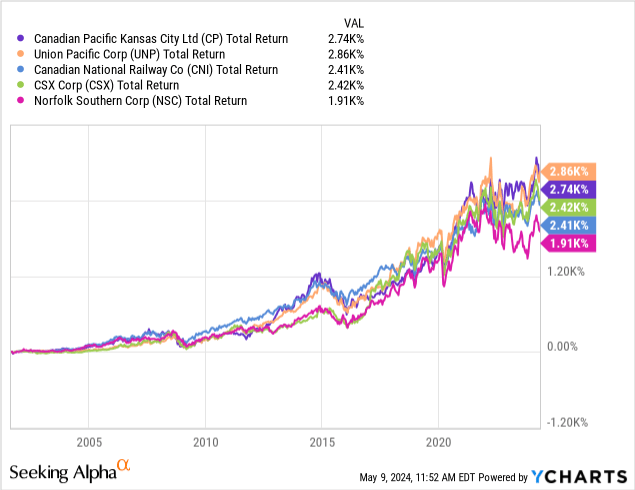
As we can see below, CP’s total return performance came second to Union Pacific Corporation (UNP) and ahead of Canadian National Railway Company (CNI), CSX Corporation (CSX) and Norfolk Southern Corporation (NSC). You can read about my opinion on UNP here.
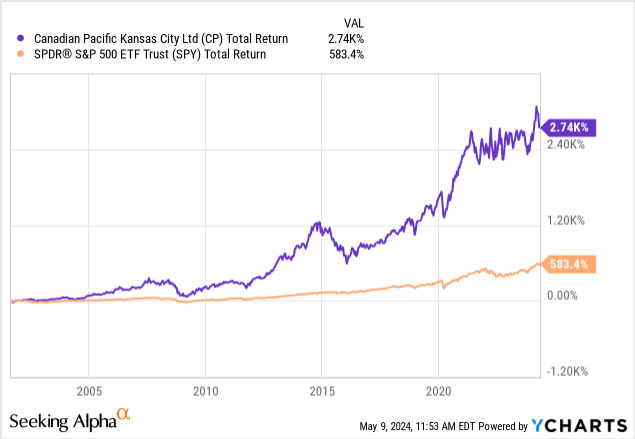
In addition, CP outperformed the market by more than four times.
Unlocking Value and Growth
As I mentioned earlier, management had to raise debt to acquire Kansas City Southern. As per the Q1 2024 earnings call, management is focusing on paying down debt and is targeting 2.5x adjusted net debt to adjusted EBITDA. Since the issuance of debt for the acquisition, leverage went from 4.0x to 3.4x. Management has signalled that the target leverage ratio is expected to be reached by late 2024 or latest early 2025.
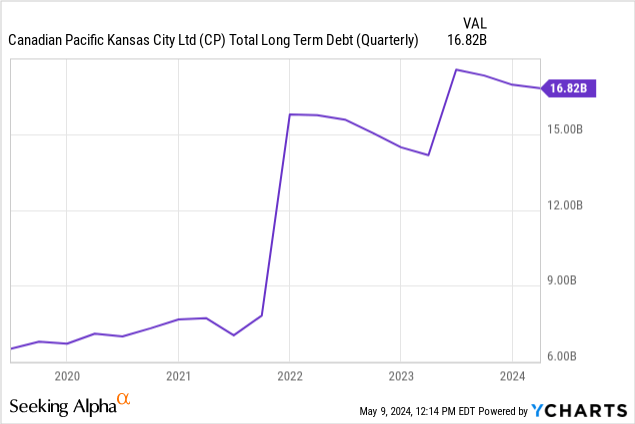
Management has also signalled that once the leverage ratio is reached, shareholder returns will be considered. I expect management to re-initiate their aggressive share buyback program. As we can see below, before the acquisition management bought back a good amount of shares and I expect the same approach from management.
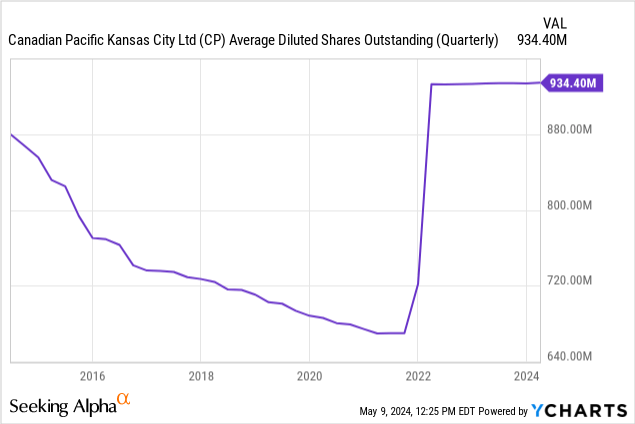
In my opinion, growth will come from the change in supply chains and industrial policies and the lack of sustainable alternatives. This will be enabled by CP’s interconnectedness and operational performance.
To start with, the United States Class 1 railroads are benefiting from the onshoring of the supply chains and the support of manufacturing to come back to the U.S. Years of offshoring supply chains are starting to reverse in an attempt to bring supply chains closer to home. A clear example is the infrastructure bill signed by the U.S. government for c.$1.2 trillion. Railroads will need to support these efforts and the new normal for supply chains. CP also benefits from owning undeveloped land that can be used if needed to further improve its operational performance and increase capacity.
In addition, the fact that people and businesses are becoming more sensitive to sustainability and green initiatives, railway companies stand to benefit. Not only are rails greener to alternative transposition methods, but CP is also at the forefront of sustainability. CP has already developed and delivered North America’s first hydrogen-powered line-haul freight locomotive. This means CP is already testing a zero-emission technology that can transform its assets and put the company well ahead of the competition.
Lastly, it is important to note that there are no alternatives when it comes to the combination of lower costs, greener transportation and interconnectedness. CP benefits from all these and in my opinion, they are well positioned to capture these tailwinds from other means of transportation. Their ability to transport materials from Mexico to Canada at a lower cost and less environmental impact is a unique competitive advantage and, in my opinion, it will further improve over time. Management seems well aware that they can take market share from trucks as they offer a cheaper and greener option to customers, which will lead to growth.
Overall, the combination of strengthening the balance sheet and capturing these growth opportunities will lead to good shareholder returns for decades to come. I do not consider this as a one-off impact but as the new normal where supply chains are closer, railways become greener and over time cheaper. Shareholders stand to benefit from this.
Relative valuation
Below I look at CP’s relative valuation compared to (CNI), (CSX), (NSC) and (UNP).
| CP | UNP | CNI | CSX | NSC | Rank | |
| P/E fwd | 27.0 | 21.8 | 21.6 | 17.6 | 24.3 | 1st |
| P/Cash flow fwd | 18.4 | 15.5 | 14.9 | 11.9 | 13.8 | 1st |
| EV/EBIT fwd | 22.1 | 18.4 | 18.2 | 14.9 | 16.8 | 1st |
| ROE 5-year average | 23.6% | 41.2% | 22.9% | 27.8% | 18.3% | 3rd |
| Operating ratio Q1, 24 | 64.0% | 60.7% | 63.6% | 63.2% | 69.9% | 4th |
As we can see above, CP is relatively overvalued. All forward price multiples are putting CP as the most relatively overvalued company when compared to its peers. In addition, the 5-year average return on total equity ranks CP as the third and operating ratio (operating expenses divided by revenue) fourth.
Looking at the absolute valuation multiples of price to earnings per share and price to free cash flow, we can see that CP’s price to earnings per share multiple was flat and price to free cash flow increased by 12% over the last three years respectively.
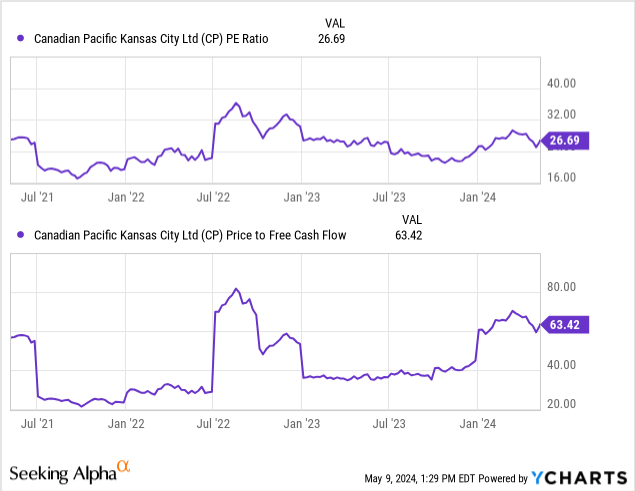
Overall, CP is overvalued when compared with its peers. I believe the company is going through a transition period following the acquisition of Kansas City Southern, and metrics should improve over time. Management has shown their ability to operationally perform well and set industry-leading metrics. I expect this performance to continue in the future.
Risk
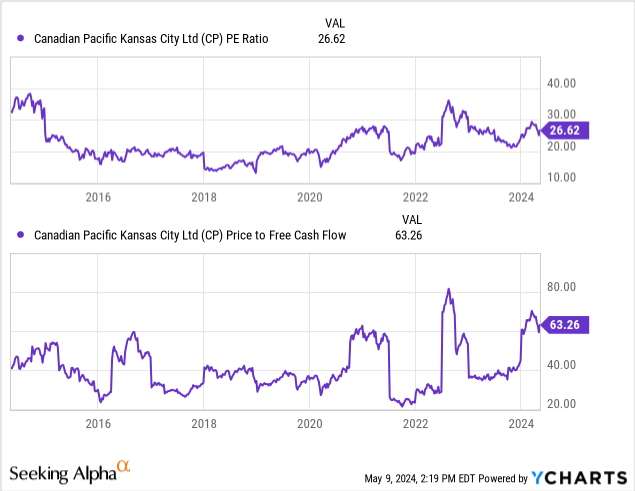
In my opinion, CP is a great company with strong assets and management. The acquisition of Kansas City Southern has positioned the company to uniquely benefit from several tailwinds, as I discussed above. However, I rate CP a hold at the current price level due to its relative valuation to peers and not enough margin of safety. The main risk for this thesis is to miss the opportunity to invest in CP due to its valuation. I expect CP to benefit and improve its fundamentals over time, but at the current price, there are better places to invest my money.
As per the below charts and CP’s price multiples, there are better times to invest in CP based on price multiples as long as investors remain patient and invest in opportunistic times. The risk is that CP’s management delivers growth that is above the market’s expectations, their fundamentals improve more rapidly and new investors have no opportunity of a pullback to initiate a position. I am comfortable waiting for the pullback, but there is a chance that the pullback never comes.
Conclusion
CP owns great assets and has good management with strong historical operational performance. I believe the acquisition of Kansas City Southern strengthens CP’s market position, as it makes the company better suited to capture some of the tailwinds on offer. The relative valuation is high, and the company is going through a transition post acquisition. I rate CP a hold at this price level and wait for a pullback before I invest in the company.
Credit: Source link