
z1b
I used to get FOMO when it comes to missing out on stock market rallies, but after having been an investor for many years, I’ve come to the realization that most stocks will give you a second (or third, fourth) chance if you missed out on an initial run-up.
Pullback opportunities are great for those who don’t want to put all of their capital to work at once. Instead, investors can opt for a lower-risk dollar cost average strategy.
Given that it’s a market for stocks rather than the stock market, there’s almost always something on sale, due to changing investor sentiment and market fluctuations that come with the territory.
This brings me to Brookfield Renewable Partners (NYSE:BEP) (TSX:BEP.UN:CA), which I last covered in March, highlighting its undervaluation despite having stable revenue sources from long-term contracts and inflation-indexed cash flows.
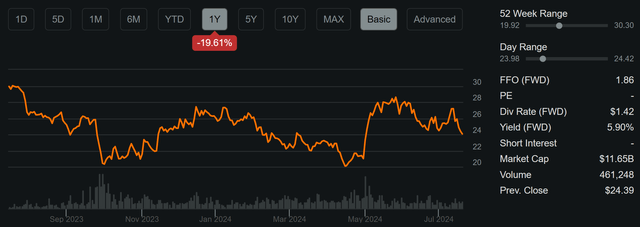
BEP has seen its ups and downs since my last piece, when it traded at $23.36, falling as low as $20 before rebounding to $28, and coming back down to $24.06 at present, as shown below.
BEP Stock 1-Yr Trend (Seeking Alpha)
In this article, I discuss why the pullback in price presents a great opportunity for income investors who have been sitting on the sidelines waiting for a better valuation, so let’s get started!
Too Cheap To Ignore, Buy The Dip
Brookfield Renewable Partners is a leading player in the emerging renewable energy sector with assets that include hydropower, utility-scale solar, wind, battery storage, and biofuels. It issues a Schedule K-1 (instead of a 1099) for tax purposes, and is externally managed by Brookfield Asset Management (BAM), a world renowned asset manager.
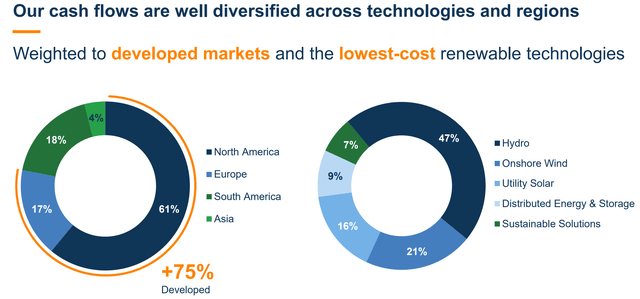
BEP benefits from a stable revenue stream due to the fact that 90% of its generation is contracted, with a portfolio average contract duration of 13 years. Plus 70% of its revenues are indexed to inflation. As shown below, BEP has exposure to all major geographies around the world, with 75% of cash flows coming from developed markets. Hydro makes up nearly half (47%) of cash flows, followed by wind and solar.
Investor Presentation
One of the hallmarks for investing in BEP is the global demand for renewable energy due to climate-related policies from both governments and corporations around the world. This has been supercharged (pun intended) by the rapid developments around AI over the past two years.
This is reflected by the recent PPA (power purchase agreement) between BEP and tech giant Microsoft (MSFT), as the latter seeks to ramp up its cloud and AI businesses. This agreement seeks to deliver 10.5 GW of renewable power capacity to support Microsoft’s AI and Cloud businesses, and represents continued catalysts to support BEP’s underlying growth.
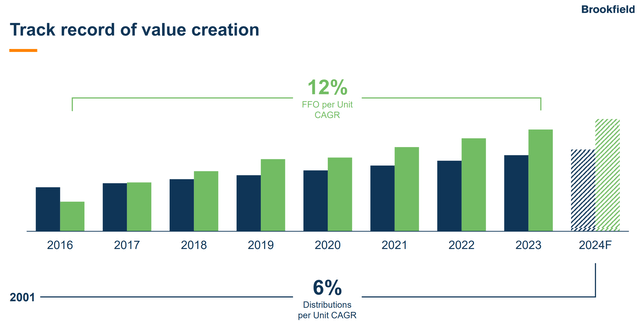
As shown below, BEP has a strong track record of value creation, with a 12% FFO per unit CAGR since 2016 and a 6% Distributions per unit CAGR over the same timeframe.
Investor Presentation
BEP continued this trend in Q1 2024, during which it grew FFO per unit by 8% YoY. This was driven by robust performance from its hydropower assets combined with growth and development initiatives. This includes continued progress toward bringing 7,000 MW of new renewable capacity this year.
Management is guiding for 10% FFO per unit growth this year due to the aforementioned capacity additions, the Microsoft agreement. This is further supported by the recently announced deal to acquire a majority stake in renewable power producer Neoen in France in a $6.5 billion deal.
This deal will significantly ramp up BEP production of solar, wind power, and its energy storage capabilities in France, Finland, Mexico, and Australia with a total portfolio of more than 8.3 GW power capacity.
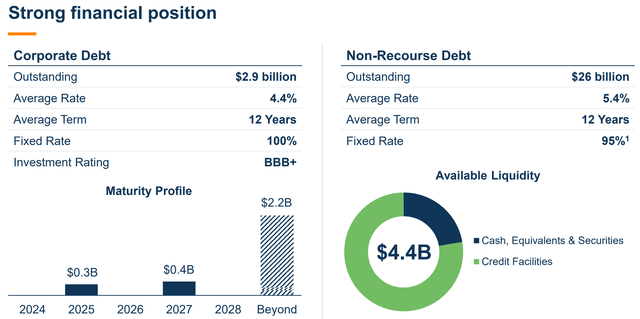
Funding for the deal is supported by portfolio recycling activities that are expected to generate $3 billion in proceeds this year. Moreover, BEP carries a strong balance sheet with BBB+ credit rating from S&P and $4.4 billion in available liquidity. It also has long weighted average debt term of 12 years, and as shown below, BEP has no debt maturities this year and limited maturities through 2028.
Investor Presentation
I find BEP to be attractive after the recent dip in price to $24.06, pushing the distribution yield back up to 5.9%. The distribution is covered by a 77% payout ratio based on expected FFO per share of $1.84 based on management’s guidance.
BEP trades at a forward P/FFO of 12.9, which appears to be too cheap considering its 5.9% yield and expected 10% FFO per unit growth this year. BEP could deliver at least market-level returns even if it misses guidance and delivers only 4% FFO per unit growth annually going forward, when combined with the 5.9% yield. As such, BEP carries a strong margin of safety at the current valuation.
Risks to the thesis include BEP’s tilt toward hydropower. Moreover, all renewable energy sources are intermittent and dependent on climate patterns that are unpredictable from quarter to quarter, which can lead to lump results. Moreover, competition from natural gas, which is a cheap and abundant natural resource, could make renewable power less attractive from an investment and cash flow perspective.
Investor Takeaway
Brookfield Renewable Partners currently presents a fantastic buy-the-dip opportunity for income investors with a 5.9% yield. BEP’s robust portfolio, which spans hydropower, solar, wind, battery storage, and biofuels, is bolstered by long-term contracts and inflation-indexed cash flows.
The company’s global reach, solid financials, and strategic partnerships, including a recent agreement with Microsoft and deal for Neoen, underscore its growth potential.
With a history of consistent value creation and solid liquidity profile, BEP’s current valuation provides a strong margin of safety, making it an attractive dividend stock for potentially market-beating total returns from here.
Credit: Source link