Just_Super
American Tower Stock Remains Resilient
Investors in multi-tenant communications operator American Tower Corporation (NYSE:AMT) have done reasonably well over the past few months, even though AMT suffered a sharp selloff in April 2024. However, AMT’s subsequent recovery has been robust, helping AMT stock’s performance to align with the market since my previous bullish AMT update in March 2024. I argued that the selloff in AMT attributed to its dividend cut shouldn’t alarm investors. The company’s prudent approach in a higher-cost environment makes sense, as American Tower seeks to return to its targeted leverage ratio. As a result, AMT management must assure investors that AMT’s dividend payout remains relatively secure to keep income investors onside.
American Tower revenue segments (Seeking Alpha)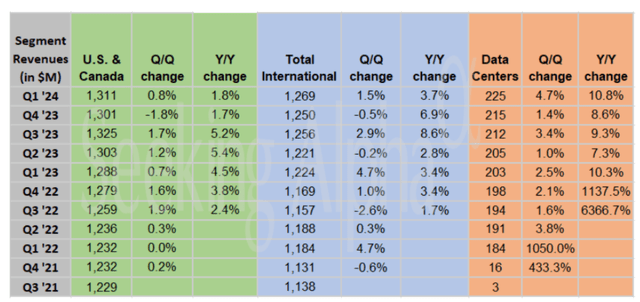
American Tower’s Q1 earnings release likely gave investors more confidence about the anticipated recovery in its 5G business throughout the year. Accordingly, American Tower’s international business delivered a solid 3.7% revenue growth in the first quarter. AMT’s data center business also posted a robust performance, with revenue growth exceeding 10% in Q1.
Furthermore, American Tower’s organic tenant billings growth has remained highly resilient, increasing 5.4% in Q1. Therefore, I assess that the recovery in AMT over the past two months is justified. American Tower’s upgraded guidance for FY2024 has likely bolstered AMT’s buying momentum, suggesting that the worst headwinds that impacted its premium valuation might be over.
American Tower Rebalances Its Portfolio
Notwithstanding my optimism, AMT investors will likely await more clarity on the REIT’s growth investments in the US and Europe. Following AMT’s challenges in India, management implemented a strategic “portfolio rebalancing.” As a result, AMT aims to “rebalance its portfolio and reduce exposure to emerging markets like India.” Given AMT’s growth premium baked into its assessed international expansion, a strategic reallocation of capital could intensify execution risks as the 5G rollout growth normalizes.
Despite that, American Tower emphasized its conviction that while 5G growth has slowed, US “mobile data usage is expected to grow by 20% to 30% annually.” Therefore, the “significantly larger user base in 5G” should continue to underpin attractive growth prospects for AMT, as “the absolute volume of data being consumed is exponentially higher.”
In addition, American Tower is still investing selectively in international growth markets. Management alludes to AMT’s growth potential in Latin America and Africa. While near-term churn challenges could impede its momentum in Latin America, 5G is expected to remain a secular growth opportunity for emerging markets as they attempt to catch up with the developed ones. Given AMT’s massive footprint and scale as a leading communications REIT, its fundamentally strong business model and secure dividend payout should help maintain robust buying sentiments.
In addition, American Tower also has a growing data center business that has benefited from the growth momentum of hybrid cloud deployments. AMT highlighted that the impact of AI is still nascent, suggesting that there could be potential earnings accretion moving ahead.
AMT Growth Premium Must Be Justified
AMT Quant Grades (Seeking Alpha)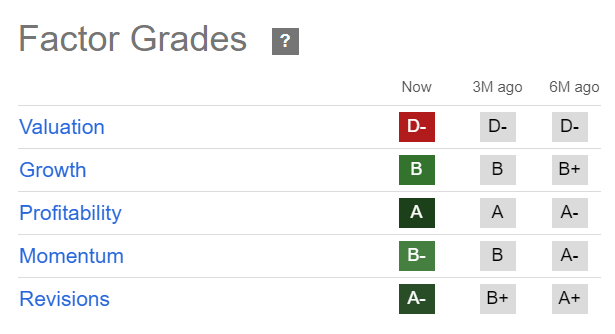
AMT is rated with a premium valuation (“D-” valuation grade), which behooves solid execution. AMT’s upgraded guidance has likely assured investors about its near-term growth opportunities.
Therefore, management must explore higher potential growth prospects outside its core markets to provide clearer visibility of its medium-term growth trajectory. AMT’s India market challenges have likely weakened that outlook somewhat. Despite that, with Europe’s interest rate cuts expected to come soon, it should bolster the timing of AMT’s portfolio rebalancing into the developed markets. Also, with the Fed’s rate hikes likely peaked, investors could be assured of higher macro clarity in AMT’s core markets, where it can execute with more confidence.
Hence, it could boost AMT’s re-rating potential as income investors reallocate their exposure to growth-oriented REITs like AMT. AMT’s forward AFFO per share multiple of 19x is below its 10Y average of 21.8x, underscoring the potential for a valuation re-rating.
Is AMT Stock A Buy, Sell, Or Hold?
AMT price chart (weekly, medium-term, adjusted for dividends) (TradingView)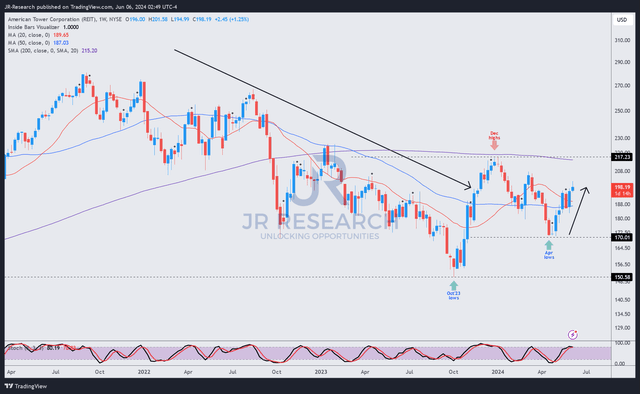
AMT stock remains in a downtrend, but the tide could be turning. As seen above, AMT buyers have stoutly held on to its October 2023 lows, which preceded a strong recovery toward its December 2023 highs.
However, AMT’s recovery fizzled out as long-term yields bottomed and recovered. Therefore, observing the solid recovery from AMT’s April 2024 lows is pivotal, corroborating my thesis that the worst is likely over.
The coast isn’t clear yet, as AMT investors must clear the $215 hurdle for the uptrend continuation thesis to pan out decisively. With AMT valued markedly below its long-term average, AMT stock’s more robust price action demonstrates an increasingly bullish thesis.
Rating: Maintain Buy.
Important note: Investors are reminded to do their due diligence and not rely on the information provided as financial advice. Consider this article as supplementing your required research. Please always apply independent thinking. Note that the rating is not intended to time a specific entry/exit at the point of writing unless otherwise specified.
I Want To Hear From You
Have constructive commentary to improve our thesis? Spotted a critical gap in our view? Saw something important that we didn’t? Agree or disagree? Comment below with the aim of helping everyone in the community to learn better!
Credit: Source link