
funky-data
Growth stocks are great, until the growth slows down. Then you have a relatively stagnant company trading at bad premiums to its underlying value.
Today, we’ll be looking at one of those growth stocks that has seen some slowing of its growth in recent quarters, Dropbox (NASDAQ:DBX). The software company has some interesting multiples which may make it worth our attention.
We will be looking at Dropbox not just for its lack of shareholder equity, but also from a potential value and growth perspective, particularly after they came in with earnings last week which beat estimates.
Understanding Dropbox
Dropbox has a service which allows the storing and sharing of digital data among various users. The company has substantial market penetration already, and reports that it is storing multiple exabytes of data.
The company offers products related to the Dropbox service like Dropbox Passwords, Dropbox Sign, DocSend, Dropbox Capture and FormSwift. The various services are premiums which are offered through subscription fees. As of the end of 2023, Dropbox reported in its annual reports that they have 18.12 million paying users for their services.
Dropbox also reported that they are investing in artificial intelligence technology, with an eye toward incorporating it into their services. They are a fairly substantially sized service, so it makes sense that they want to retain a comparative advantage that could be offered by AI.
The Earnings
After close on Thursday, Dropbox reported their earnings. The company came in at $634.5 million and 60¢ earnings per share, both of them beating estimates. The company also reported that they now have 18.22 million paying users for subscriptions.
With admissions by the company that their growth has been slowing recently, coming in ahead of the estimates is a very good thing. Beating the earnings could, if it continues on a regular basis, show that Dropbox still has room for substantial growth.
Consolidated Balance Sheet
|
Cash and Equivalents |
$515 million |
|
Total Current Assets |
$1.23 billion |
|
Total Assets |
$2.72 billion |
|
Total Current Liabilities |
$1.18 billion |
|
Senior Notes |
$1.38 billion |
|
Total Liabilities |
$3.09 billion |
|
Shareholder Equity |
($371 million) |
(source: most recent 10-Q from SEC)
Like a lot of growth companies, Dropbox has more liabilities than assets, and therefore a negative shareholder equity. That’s not good if the growth doesn’t start to pick up again. If the company is growing consistently going forward, the senior notes, which are paying in 2026 and 2028, respectively, will be readily manageable. Even as it stands, the debt isn’t too scary.
The Risks
As mentioned above, the rate of growth of Dropbox has been declining recently. That’s a potential issue, especially because data storage and sharing is such a competitive market, and customers have a lot of alternatives if Dropbox no longer seems like the en vogue thing to use.
To maintain the view as a growth company, what they really need to do is continue to convert their new users of free services into paying users. The company makes a very nice gross margin, as we’ll see later, but there’s only that sort of margin for end users who are actually paying for some subscription service.
Important in maintaining the company as it currently stands, Dropbox needs to find ways to retain existing users and ideally to convince them to upgrade into higher premium services than what they already have.
Statement of Operations
|
2021 |
2022 |
2023 |
2024 (1H) |
|
|
Revenue |
$2.1 billion |
$2.3 billion |
$2.5 billion |
$1.3 billion |
|
Gross Profit |
$1.7 billion |
$1.9 billion |
$2.0 billion |
$1.1 billion |
|
Operating Income |
$274 million |
$181 million |
$539 million |
$270 million |
|
Net Income |
$336 million |
$553 million |
$454 million |
$243 million |
|
Diluted EPS |
85¢ |
$1.52 |
$1.31 |
73¢ |
(source: most recent 10-K and 10-Q from SEC)
Dropbox has been growing, but as mentioned, it is growing slower than it had been previously. The thing I really like about the company is how high its gross margins are, which gives them a lot of room to offer discounts to try to grow their paid user base.
As reported in 2023, the company would have a P/E ratio of 17.17. That’s not a terrible premium for a company that is growing like Dropbox has the potential to, but if the growth continues to slow, it’s a bit rich from my perspective.
Still, estimates are that the company will be growing in the years to come. In 2024, the company is expected to come in at $2.55 billion with an earnings per share of $2.24. That gives us a forward P/E of a very reasonable 10. In 2025, the estimates predict things to continue about at the same pace, with revenue of $2.60 billion and earnings of $2.38.
Conclusion
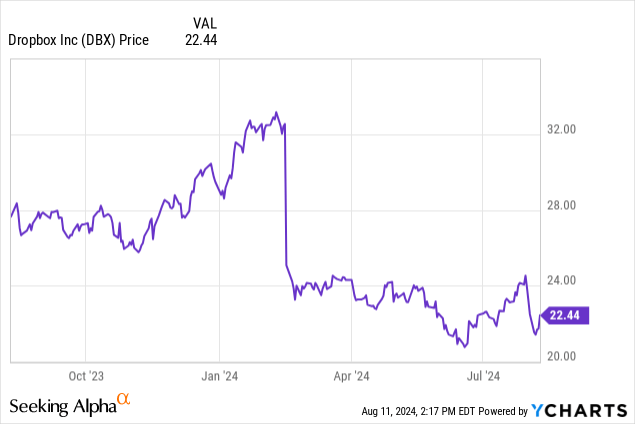
Dropbox is trading at a fairly modest multiple to earnings, if the growth continues at an appealing enough rate. That’s a big if, unfortunately, and to me, that’s the difference between this being a buy at current levels, and what I view it, which is a hold.
I believe the company does have a possibility of being at a justifiable price at these levels, and after last week’s earnings beat I think it is important to keep a close eye on it, as it is possible that the company will keep up its growing that we’ve come to expect.
If the stock does test its 52-week lows again, I would definitely be interested in the possibility of revising the stock to a buy. Dropbox is a solid company that would make a nice fit in a lot of portfolios, and at prices around or below $20 per share, I’d be very interested in adding some.
Credit: Source link