
deberarr/iStock via Getty Images
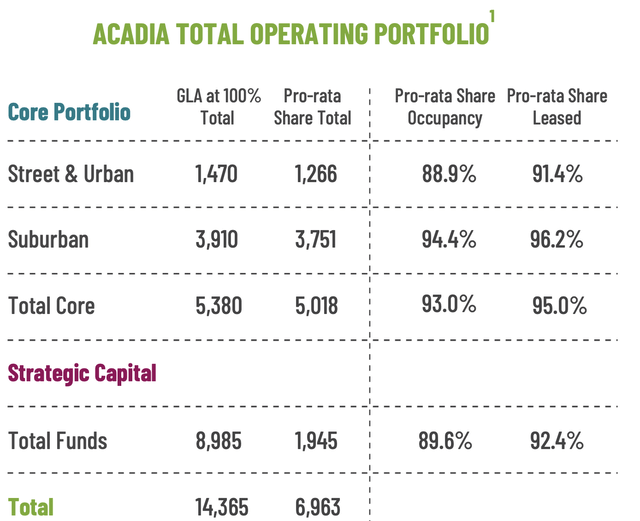
Acadia Realty Trust’s (NYSE:AKR) focus on street retail has made the ticker one of the more unique retail REITs in the space. The internally managed REIT is pursuing growth through its core portfolio of 139 operating properties spread across 5.4 million square feet of gross leasable area as of the end of the fourth quarter of 2023. AKR’s pro-rata share of this at 5 million square feet was also 93% occupied and 95% leased at the end of the fourth quarter. The REIT also aims to generate additional growth through its Funds, which co-invest with institutional investors. These dual investment platforms form AKR’s investment strategy, with the Funds owning and operating 50 properties spread across roughly 9 million square feet. AKR’s pro-rata share of this was 2 million, with this share 89.6% occupied and 92.4% leased at the end of the fourth quarter.
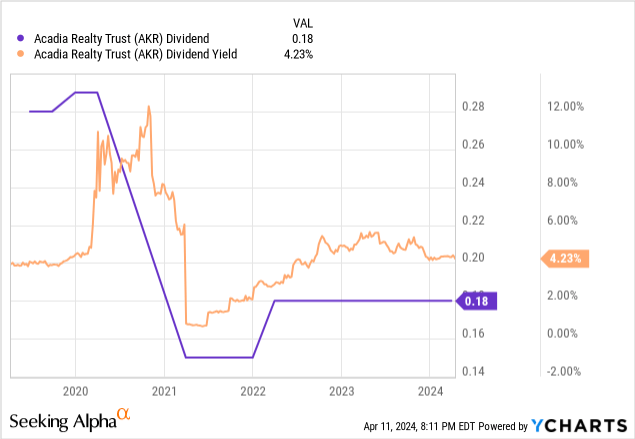
The REIT last declared a quarterly cash dividend of $0.18 per share, kept unchanged sequentially and $0.72 per share annualized, for a 4.2% dividend yield. Critically, the quarterly distributions still sit 38% below their 2019 pre-pandemic level. AKR generated a fourth-quarter FFO of $0.28 per share, up by $0.01 over its year-ago comp and providing 156% coverage for the dividend. Hence, a core part of the REIT’s investment thesis is the growth outlook of the dividend. AKR’s 11% discount to the GAAP book value of its high-quality properties when I last covered the ticker has closed. This set the backdrop for a January stock offering of six million common shares that would eventually raise $113 million in proceeds after the underwriters exercised a 30-day option to purchase an additional 900,000 shares.
Revenue, NOI, And Book Value
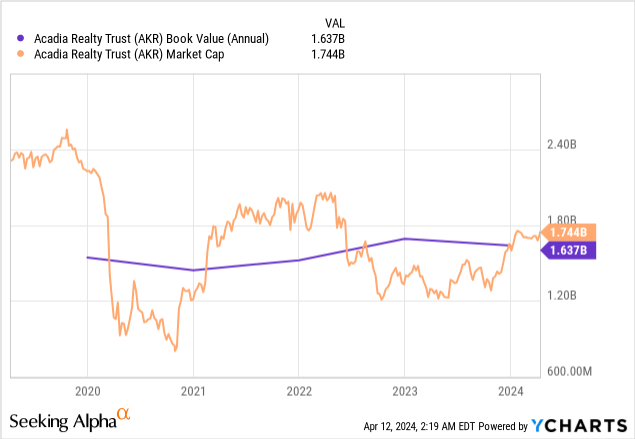
AKR is currently trading at a small 6% premium to book value at the end of the fourth quarter. The REIT recorded fourth-quarter revenue of $85.51 million, up 6.1% over its year-ago comp and beating consensus by $8.15 million. Same-property net operating income grew by 4.2% for the fourth quarter and 5.8% for the full year 2023, with the REIT’s street retail portfolio realizing 10% same-property NOI growth on the back of new core cash rent spreads of 44% for the full year and 25% for the fourth quarter. This growth was driven by the recapture and re-lease of a space in Soho, New York, as the city continues to rebound from the pandemic and visitor numbers keep growing.
Acadia Realty Trust March 2024 Investor Update
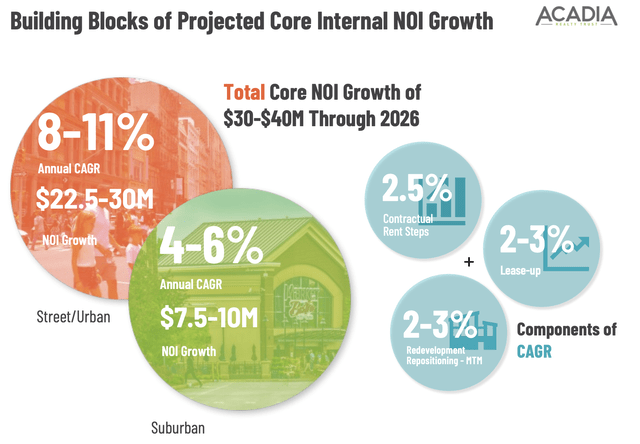
AKR’s focus on retail properties located predominantly in areas with a strong barrier to entry, with high density like Soho, New York, and Melrose Place, Los Angeles has formed a distinct driver of NOI growth. The REIT expects multi-year annual growth in excess of 10% on the back of rent spreads ranging from 10% to 50%. AKR expects a total core NOI growth of $30 million to $40 million through 2026.
Acadia Realty Trust March 2024 Investor Update
Dividend Growth Outlook And The Fed
AKR is currently paying out roughly 64% of its FFO as a dividend. This comes as the REIT faces no significant core debt maturities until 2026 and is projecting an FFO of $1.28 at the mid-point for its fiscal 2024, roughly 5% growth over its year-ago comp with projected same-property NOI growth of 5% to 6% set to be the main driver of this. However, I think future near-term returns could be relatively flat as pending Fed rate cuts get pushed back later into 2024. A start of summer cut would have provided a catalyst for the common shares, but inflation has remained stickier than consensus, dampening the need for the Fed to loosen monetary policy.
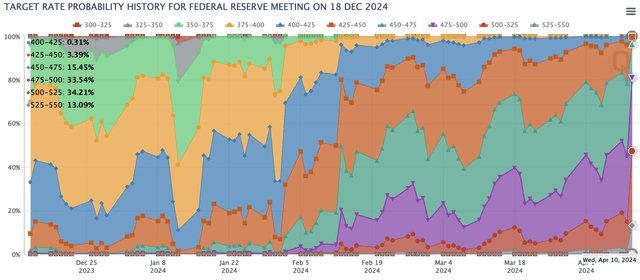
CME FedWatch Tool
The odds of this most salient catalyst have dramatically reduced in recent weeks with the market now expecting the Fed to essentially keep rates at 22-year highs for the entire year until the December FOMC meeting. According to the CME FedWatch Tool, the odds of rates remaining where they are exiting 2024 have jumped from around 0.1% to 13.09% with a single 25 basis points cut now the base expectation, down from at least three rate cuts of 75 basis points at the start of 2023. Fundamentally, AKR is a high-quality REIT currently trading above book value with a lower dividend yield than larger retail REITs like Agree Realty (ADC) and Kimco (KIM), but with a distinctive portfolio set to realize double-digit NOI growth for the next few years. While AKR is less of a buy on a relative basis than these other two investment grade rated REITs, the street retail focus is set to power double-digit NOI growth and a possible continued recovery of a dividend recovery stalled since early 2022. AKR is now being rated as a hold.
Credit: Source link