
Abstract Aerial Art
Ares Capital (NASDAQ:ARCC) reported better than expected results for the second fiscal quarter at the end of July and the business development company continues to see good balance sheet quality as well as a dividend that is well-supported by net investment income. Shares sold off this week, on fears over a recession, but Ares Capital’s results for Q2’24 were solid in more ways than just one. New investments boomed, and I believe, from a fundamental point of view, that Ares Capital is a solid yield play for income investors. The BDC’s strong dividend coverage and good asset quality especially make the BDC a top investment even during times of heightened volatility!
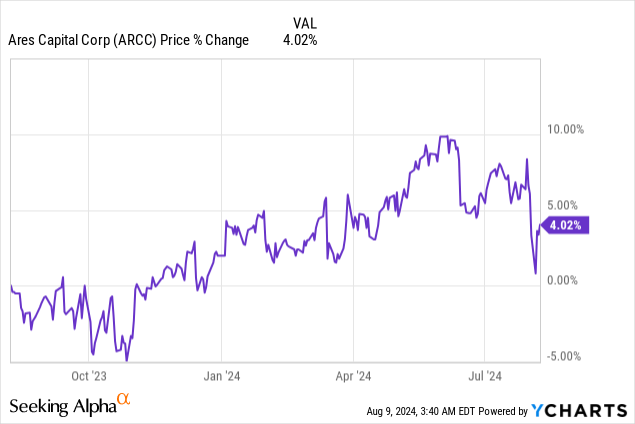
Previous rating
I rated shares of Ares Capital a buy earlier in 2024 due to growing debt yields in the BDC’s portfolio and a well-supported dividend that implied recurring dividend income for shareholders (although no dividend growth). I managed to get my hands on a few shares earlier this week when the market dipped, and I generally believe that the value proposition remains very strong for income investors.
Strong asset quality, good dividend coverage
Ares Capital’s portfolio value grew $1.85B in the second fiscal quarter as the BDC is seeing positive momentum in new loan commitments. The BDC’s investments at the end of the June quarter totaled $25.0B and the portfolio continued to consist mainly of Senior Secured investment of the first and second lien variety (a combined 62%). I like the BDC’s Senior Lending focus as it reduces portfolio risks for income investors should the U.S. economy have to deal with a recession later this year or at some point in 2025.
Ares Capital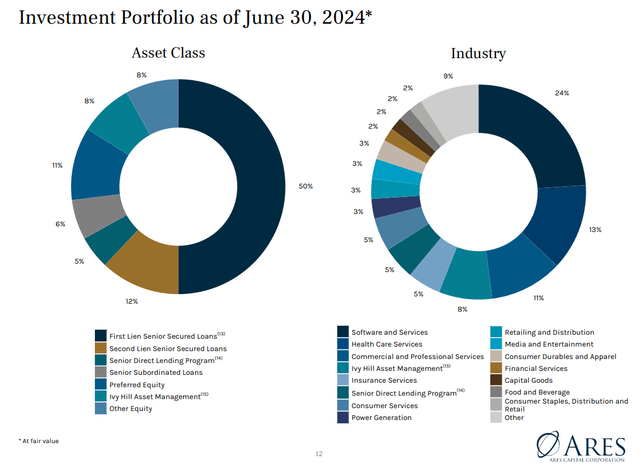
The biggest take-away for the BDC was that Ares Capital’s net commitments surged to $2.5B in the second-quarter, largely due to a lower commitment exits. It was by far the highest amount of net commitments for the BDC in the last year and a key driver behind Ares Capital’s investment growth in the second-quarter.
| in $M | Q2’23 | Q3’23 | Q4’23 | Q1’24 | Q2’24 |
| Gross Commitments | $1,218 | $1,598 | $2,384 | $3,554 | $3,857 |
| Exits of Commitments | ($1,138) | ($1,280) | ($1,427) | ($3,414) | ($1,376) |
| Net Commitments | $80 | $318 | $957 | $140 | $2,481 |
(Source: Author)
Turning to portfolio quality.
Ares Capital’s non-accrual percentage remained unchanged in the second fiscal quarter and therefore continued to indicate a high level of asset quality. The BDC had a Q2 non-accrual percentage of only 0.7%, which was steady quarter-over-quarter. A focus on Senior Secured lending, a high degree of balance sheet quality and consistent excess dividend coverage make Ares Capital a top holding for dividend income even if economic conditions should deteriorate going forward.
|
Portfolio, Non-Accrual Trend |
Q2’23 |
Q3’23 |
Q4’23 |
Q1’24 |
Q2’24 |
|
Portfolio Value, fair value |
$21,496 |
$21,929 |
$22,874 |
$23,124 |
$24,973 |
|
Non-Accrual Amount (cost, $M) |
$444 |
$266 |
$295 |
$397 |
$360 |
|
In Percent |
2.1% |
1.2% |
1.3% |
1.7% |
1.5% |
|
Non-Accrual Amount (fair value, $M) |
$239 |
$136 |
$136 |
$168 |
$177 |
|
In Percent |
1.1% |
0.6% |
0.6% |
0.7% |
0.7% |
(Source: Author)
Ares Capital generated $358M in net investment income in the second-quarter, showing 14% year-over-year growth. This growth came chiefly from higher interest income from Ares Capital’s loan investments, the majority of which are linked to variable rates. Interest income from investments totaled $539M in Q2’24, showing 13% year-over-year growth. According to Ares Capital’s portfolio summary sheet, 69% of the company’s loans made variable rate payments in the second-quarter.
Ares Capital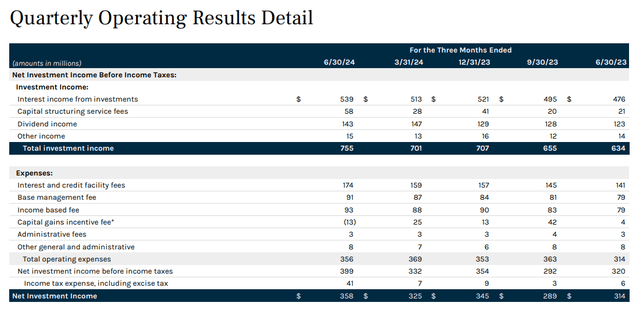
Ares Capital generated $0.58 per-share in net investment income in the second fiscal quarter which calculates to a dividend coverage ratio of 1.21X. This coverage ratio compares to dividend coverage ratios of 1.15X in Q1’24 and 1.19X in Q2’23. The dividend coverage ratio has remained fairly steady in the last year and Ares Capital managed to support its dividend well with distributable earnings on a consistent basis. Although the dividend is not growing, the current payment of $0.48 per-share is sufficiently protected, in my opinion.
Ares Capital’s valuation
The three largest BDCs in the sector are Ares Capital, Blackstone Secured Lending (BXSL) and Blue Owl Capital (OBDC). Ares Capital is currently trading at a 1.04X P/B ratio, which is lower than the average P/B ratio in the last 3-years, due to the market sell-off last week and on Monday of this week. Blackstone Secured Lending is also a top income play, in my opinion, due to the company’s strong asset quality and good dividend coverage. BXSL is trading for the highest P/B ratio in the industry group below, chiefly because the BDC has one of the lowest non-accrual ratios in the market (less than 0.1%). Blue Owl Capital is trading at a 5% discount to net asset value, due to its higher ratio of non-accruals.
Given the quality of Ares Capital’s portfolio and dividend coverage, I believe the BDC could easily trade at a fair value P/B ratio of 1.10X (as I indicated in my last work on ARCC in May 2024). Ares Capital’s net asset value as of the end of the June quarter was $19.61 per-share which I tend to use as my low-case estimate for intrinsic value. A 1.10X multiplier implies a fair value in the neighborhood of $21.60 at which point I would consider selling.

Risks with Ares Capital
One risk that I see, especially after this week’s massive sell-off in the market, is a potentially faster decline in the federal fund rate. With recession fears lingering in the market and now irritating investors, calls may grow for the Federal Reserve to implement emergency rate cuts in a bid to restore investor confidence and counter a potential recession. Since Ares Capital is mainly lending on a variable-rate basis, this would likely be a setback for Ares Capital. What would change my mind about Ares Capital is if the BDC were to see a significant decline in its dividend coverage ratio.
Final thoughts
Ares Capital reported better than expected Q2 results at the end of last month due to strong asset performance and a resurgence of new investments. As a result, Ares Capital grew its portfolio, supported its dividend easily with net investment income and maintained good balance sheet quality, with the non-accrual percentage not changing quarter-over-quarter. Shares of Ares Capital are currently also priced below the 3-year average price-to-book ratio and trade at only 1.04X P/NAV. I don’t see any immediate risks to the dividend for Ares Capital and should more rocky times be ahead, ARCC is the kind of BDC I would want to own in my portfolio!
Credit: Source link