
Luis Alvarez
ETF Overview
Fidelity MSCI Communication Services ETF (NYSEARCA:FCOM) owns a portfolio of 25 U.S. communication services stocks. The fund has a low expense ratio of 0.08%. Its fund price has almost recovered to the previous peak reached in 2021 and is on a rising trend. The fund has a high concentration risk and the fund’s performance can be impacted heavily by the cyclicality of the economy. FCOM’s long-term growth outlook remains bright. Although its valuation is elevated, it is still well below the peak reached during the pandemic. Given FCOM’s strong long-term growth outlook, the fund deserves a buy-rating.
Fund Analysis
FCOM has walked out of the cyclical low reached in late 2022
Let us first review how FCOM has performed in the past few years. The fund has done very well during the initial outbreak of the pandemic thanks to the strong demand for communication services. Unfortunately, FCOM experienced a significant decline in much of 2022 due to rising inflation as well as declining demand. Fortunately, FCOM has gradually walked out of the low reached in late 2022 and its fund price has almost fully recovered from the peak reached during the pandemic.
YCharts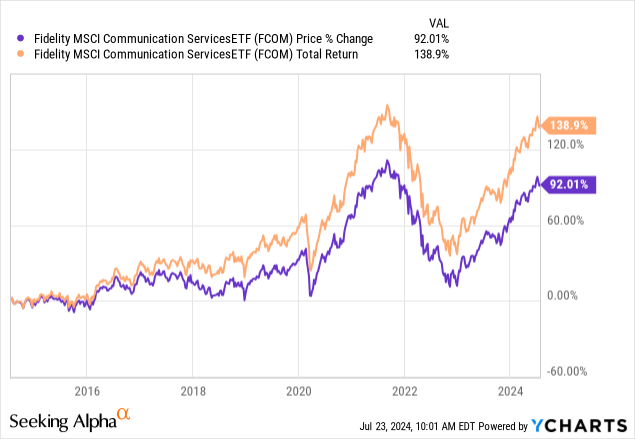
A concentrated portfolio
FCOM has a concentrated portfolio. As can be seen from the table below, its two largest holdings, Meta Platforms (META) and Alphabet (GOOGL) consist of about 44.2% of the total portfolio. This high concentration is a concern, especially because the majority of the revenues of these two stocks come from advertising revenues. As we know, advertising incomes can be very cyclical. In economic recessions, businesses typically are less willing to spend on advertising, and vice versa. Therefore, FCOM’s performance can be quite cyclical and volatile.
Morningstar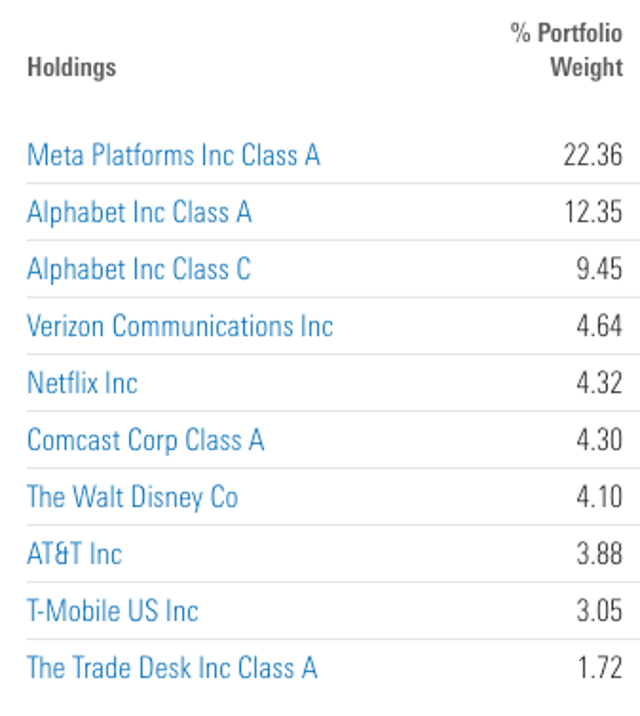
Higher volatility and downside risk
This is exactly the case for FCOM in the past. Its 5-year average monthly beta ratio of 1.13 is much higher than the S&P 500 index’s 1.0. In addition, FCOM also has higher downside risk in economic turmoil due to its higher exposure to stocks that depends on advertising revenue. As can be seen from the chart below, FCOM typically experienced much higher downside than the S&P 500 index in harsh situations. For example, in the rapid rate rising environment in 2022, the fund has declined by more than 45%. In contrast, the S&P 500 index only declined by about 23%.
YCharts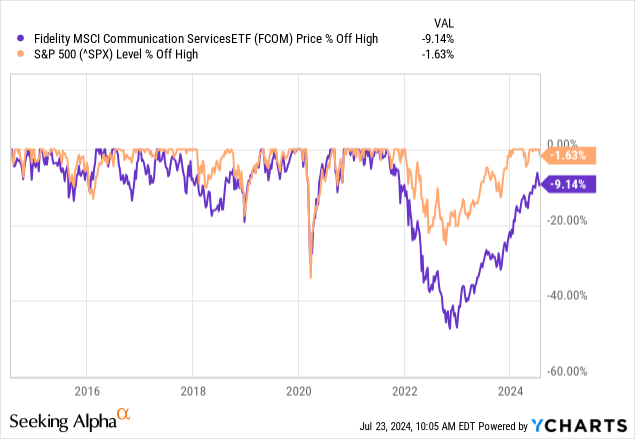
Growth outperforming many other sectors
FCOM has better short-term and long-term earnings growth rate than the S&P 500 index. Below is a table that shows the short-term earnings growth (STEG) and long-term earnings growth (LTEG) rates of communication services stocks and the S&P 500 index. For reader’s information, STEG refers to next 12 month earnings growth, and LTEG refers to average annual earnings growth rate in each of the next 5 years. As can be seen from the table below, communication services stocks have STEG and LTEG rates of 16.1% and 18.2% respectively. These growth rates are slightly higher than the S&P 500 index’s growth rates. Therefore, we like FCOM’s growth outlook.
|
Earnings Growth |
STEG |
LTEG |
|
Communication Services |
16.1% |
18.2% |
|
S&P 500 Index |
13.2% |
16.9% |
Source: Yardeni Research, Created by author
In addition, the growth rate for communication services stocks in the next two years are expected to be in the double digits. As can be seen from the table below, the sector’s earnings growth rates are expected to be 12.7% and 13.7% in 2025 and 2026 respectively. These rates are comparable to the S&P 500 index’s earnings growth rate of 14.9% in 2025 and 12.5% in 2026.
|
Earnings Growth |
2025 |
2026 |
|
Communication Services |
12.7% |
13.7% |
|
S&P 500 Index |
14.9% |
12.5% |
Source: Yardeni Research, Created by author
Valuation not cheap
Below is a chart that shows the average forward P/E ratio of communication services stocks in the S&P 500 index. As can be seen from the chart, these stocks currently trade at an average forward P/E ratio of 18.8x. This ratio is below the peak of 23~24x reached during the height of the pandemic in late 2020 and early 2021, but still quite elevated relative to the sector’s valuation range in the past 2 decades.
Yardeni Research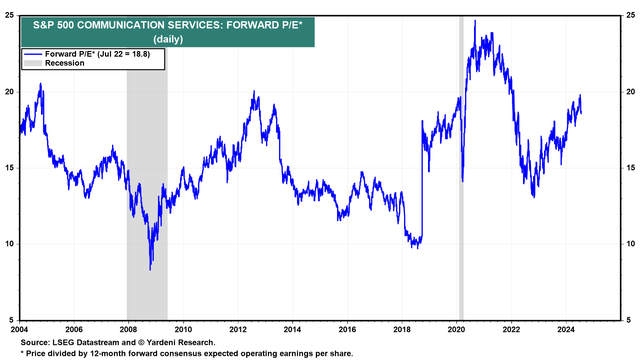
Investor Takeaway
We like FCOM’s growth outlook and its valuation is not particularly expensive. Therefore, we are willing to give it a buy-rating. However, as we have shown in our analysis, investors should embrace for volatility. Conservative investors may want to wait for a pullback.
Additional Disclosure: This is not financial advice and that all financial investments carry risks. Investors are expected to seek financial advice from professionals before making any investment.
Credit: Source link