
Paul Bradbury
Today I’d like to discuss a niche software company that went public back in 2021. This company has a strong founder-led CEO and has been growing revenue and clientele in recent years. The company’s stock price is up over 12% YTD and is up nearly 40% year-over-year.
However, this is still an unprofitable company, one that hasn’t done much for shareholders yet as the stock is still down since going public.
The company is Procore Technologies, Inc. Let’s dig into the company to see if this business can continue to grow and provide returns to shareholders in years to come.
The Company
Procore Technologies (NYSE:PCOR) was founded back in 2002 by Craig “Tooey” Courtemanche. At the time Courtemanche was working in Silicon Valley but had a house being built in Santa Barbara. Courtemanche was having various issues surrounding the communication of the job with the numerous parties involved and so Courtemanche created a way in which all these parties could communicate with one another more effectively and thus Procore was born.
The company’s mission is simple, “To connect everyone in construction on a global platform.” Procore is the leader in providing cloud-based construction management software. The construction industry is a complex one with many key players depending on the job or task at hand. Procore’s technology helps connect those involved in a construction job such as owners, general and specialty contractors, architects, and engineers so tasks can be completed in a timely and efficient fashion.
The below graphic illustrates Procore’s offering as the company’s software has five different product categories, Preconstruction, Project Execution, Workforce Management, Financial Management and Construction Intelligence:
Investor Presentation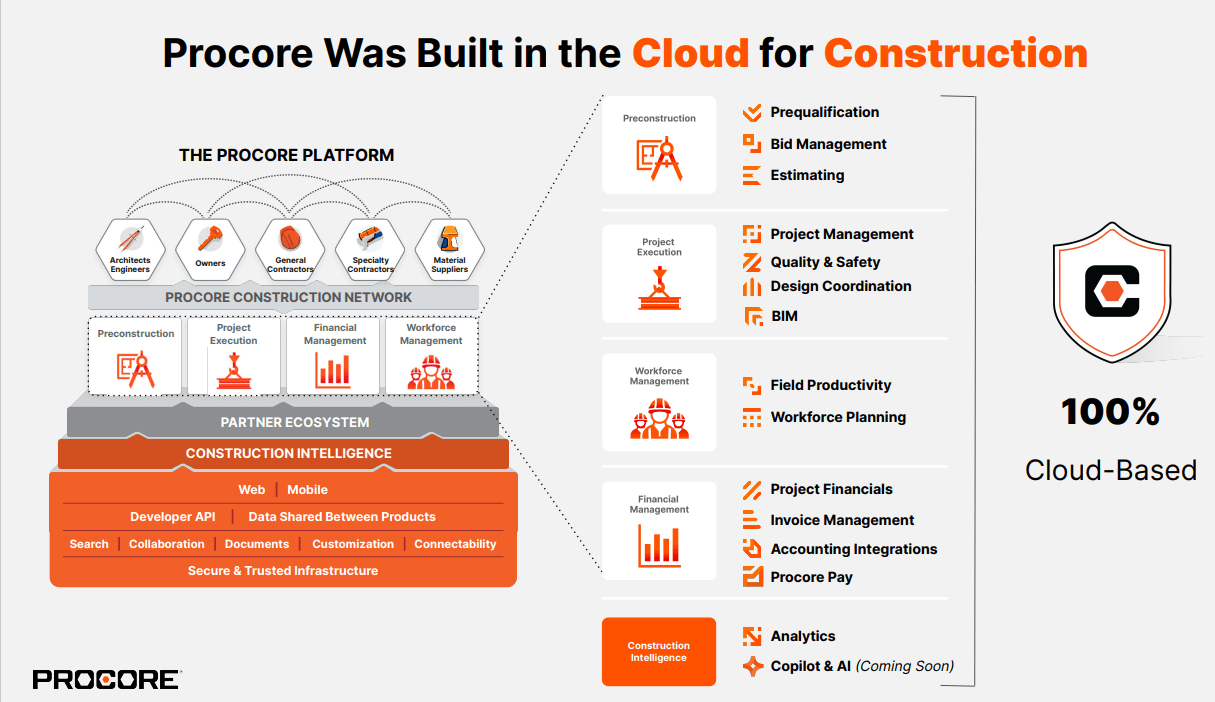
The Construction Intelligence product isn’t out yet, but Procore will utilize Microsoft’s Copilot for AI capabilities such as creating a virtual assistant.
Additionally, Procore has also recently launched Procore Pay which will enhance the company’s financial suite. On the company’s latest earnings call, although it’s still very early into the launch, Courtemanche stated, “…We are excited about payments and the early feedback has been very positive. It’s important to note that we are the only solution in the market that connect estimating to contracts to compliance documents to invoices to payment workflows, all on a single platform.”
Moat and Opportunity
Procore believes they have a large opportunity as the construction industry is “one of the oldest, largest, and least digitized industries” as stated by the company in their most recent 10K filing. The industry is fragmented and can be quite specialized in particular areas.
Construction is still a huge industry as Procore stated on a recent investor presentation, $11 trillion was spent on global construction in 2020 and it’s estimated that number will climb to $15 trillion by 2030. Furthermore, in 2017 13% of United State GDP came from the construction industry and 7% of the global workforce came from the construction industry.
As shown below, Procore believes they have a domestic opportunity of approximately $1.8 trillion and an international opportunity of approximately $2 trillion:
Investor Presentation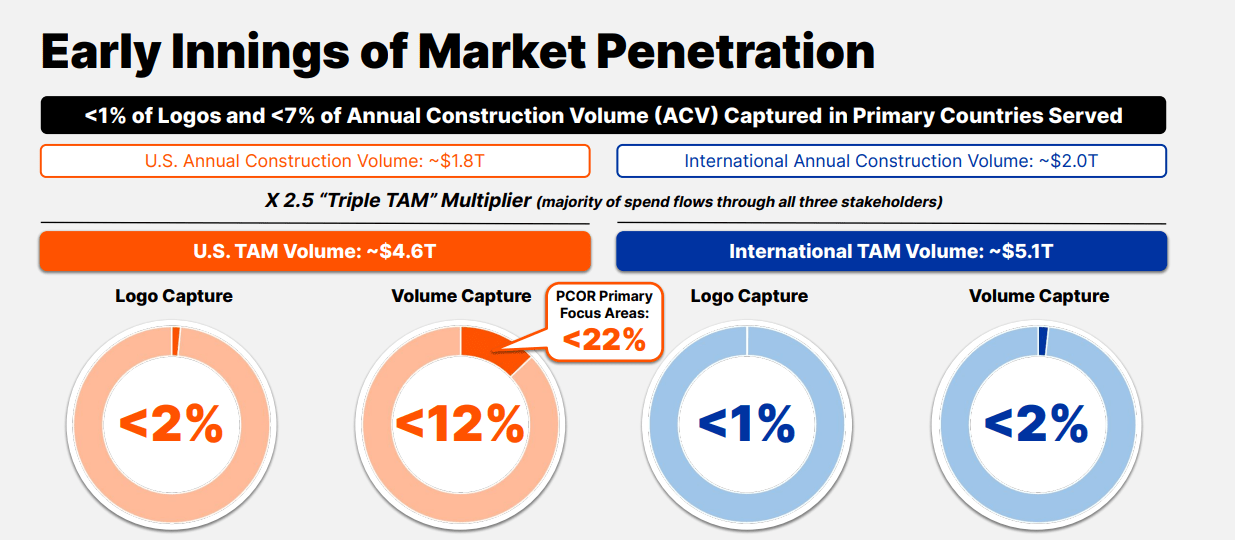
As noted on the company’s recent 10K, key competitors include, Oracle (ORCL), Autodesk (ADSK), and Trimble (TRMB). While these are some serious players in the technology space, Procore seems to be leader in this market, and I do believe Procore has a moat. As I was researching the top software for construction industries Procore was frequently the top software listed. Procore even shows their ratings on their website which illustrates how much companies like their software.
The point is further illustrated with this graphic I pulled from Finchat.io. Procore has steadily been growing their number of customers (as shown by the black line) and the number of customers with annual recurring revenue of 100K or more (as shown by the blue line) is increasing as well:
Finchat.io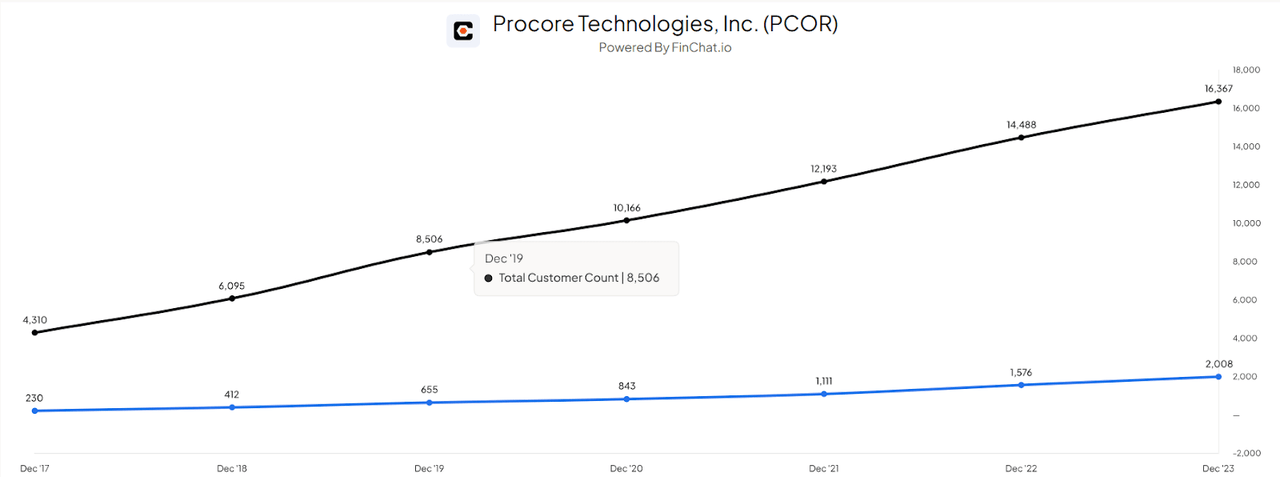
Also as Courtemanche noted on the company’s latest earnings call, Procore’s net retention rate is at 114% which shows the strength of the software. Currently, I do think Procore seems to be market leader and their technology has given them a competitive advantage.
Management
As noted above, Craig “Tooey” Courtemanche is the Founder, President and CEO of Procore.
Howard Fu is the company’s current CFO. Fu has worked at Procore since 2021. He came over from DocuSign where he was a key part of the organization’s finance team. Fu has also worked at Salesforce as well.
The Glassdoor ratings show that Procore is a truly great place to work as it was awarded as being one of the best places to work in 2017, 2019, 2022, and 2023. Most recently in 2024 Procore was ranked by Glassdoor as fifth best place work to work which is quite the accomplishment.
Below are the current Glassdoor reviews. Procore is viewed as an excellent place to work, and the employees there clearly approve of Courtemanche:
Glassdoor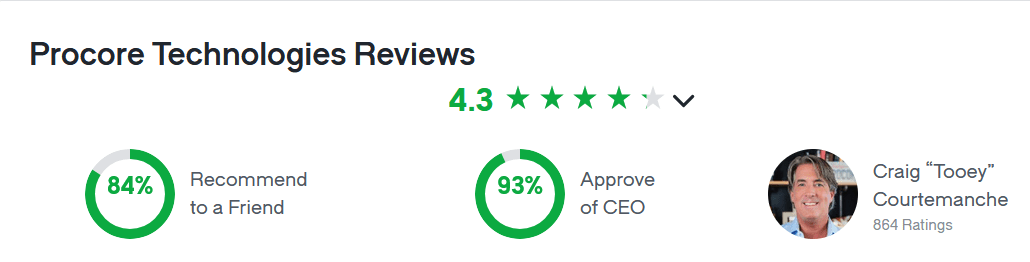
As I’ve stated in the past, I’m a big believer in founder CEOs due to their propensity to focus on the long term and I like when senior leadership has skin in the game. Procore’s current year proxy will come out shortly but as of the company’s last proxy statement Courtemanche held over 5% of the company’s common stock which I like to see.
Financials
Procore has yet to become GAAP profitable but the company has been making impressive strides as you can see below in the company’s most recent 10K filing:
SEC.gov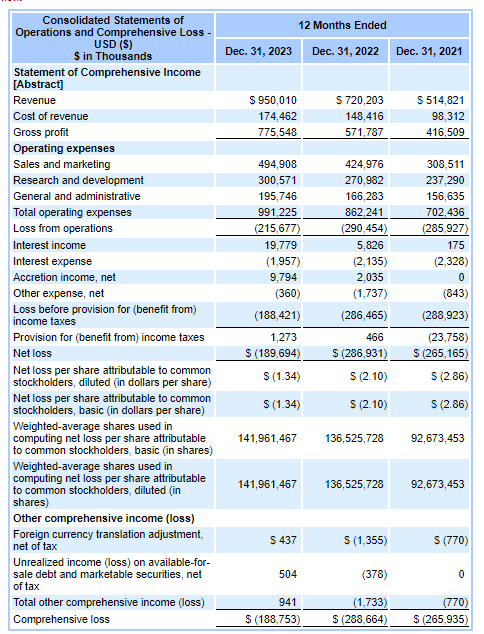
Procore delivered revenues of roughly $950 million for the latest fiscal year which is a 29% increase compared to the prior year. Furthermore, Procore’s GAAP gross margin is at an impressive 82%.
From a cash flow perspective, Procore delivered operating cash inflow of roughly $92 million in 2023 which is far greater than $12 million of operating cash inflow in 2022. Free cash flow for 2023 came in at roughly $47 million.
Procore does have a solid balance sheet as well as you see below:
SEC.gov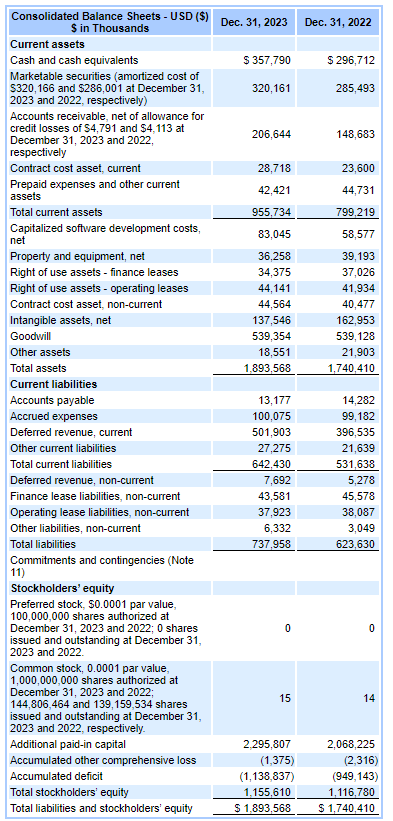
The company’s cash balance has grown to is nearly $358 million, and their current assets balance can cover all of the organization’s current liabilities.
Risks
Procore lists numerous risks to the business on their most recent annual report. I’m going to discuss two risks which I believe could hurt the organization.
As Courtemanche touched on in the company’s recent earnings call, the construction business is cyclical and is closely connected with the economy as well as interest rates. Here is an portion of Courtemanche’s opening remarks which really reflect how Procore’s business is effected by these factors:
“So, I’d like to start by acknowledging that 2023 proved to be a challenging year amid a tough economic environment. Much of the commentary we shared on our last earnings call is still relevant to what we’re seeing today. 2022 and 2023 were very different years for our industry.
In 2022, our customers demonstrated optimism in their sentiment and their buying behavior. This optimism largely stemmed from the strength of our customers’ backlogs and their confidence in the future pipeline of work, however, 2023 brought a notable shift. While backlogs remain strong, sentiment shifted partially due to rapidly rising interest rates and the industry began to hedge against future work just in case.
Sentiment drove conservatism for the future and led the industry to be cautious about future volume commitments should future demand weigh in. As we all recognize, construction and our economy are cyclical.”
The US economy has remained resilient lately but should the country go into a recession, as some predict will occur, this would hurt the construction industry and in turn Procore.
As noted earlier, Procore competes with several large companies such as Oracle, Autodesk, and Trimble. Procore must continue to innovate and create exceptional technology so customers will remain loyal. If Procore fails to do so their position as the leader within this niche software industry would certainly be in jeopardy.
Valuation
As you can see from the below valuation metrics from Seeking Alpha, the overall value grade for Procore is a “D-.”
Seeking alpha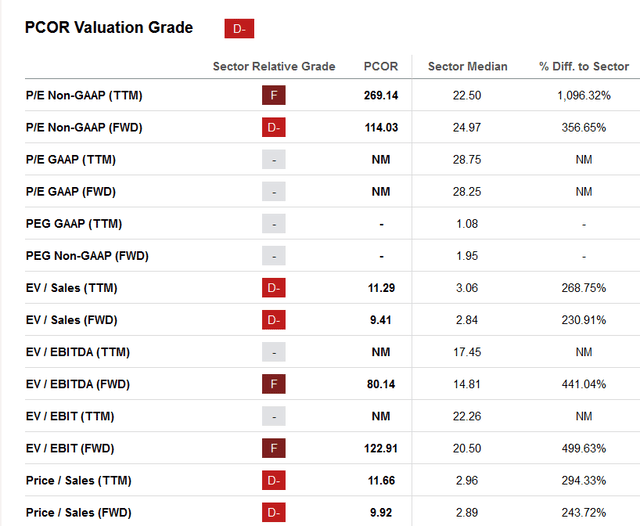
As Procore is unprofitable, I think price to sales is the best metric to view this organization.
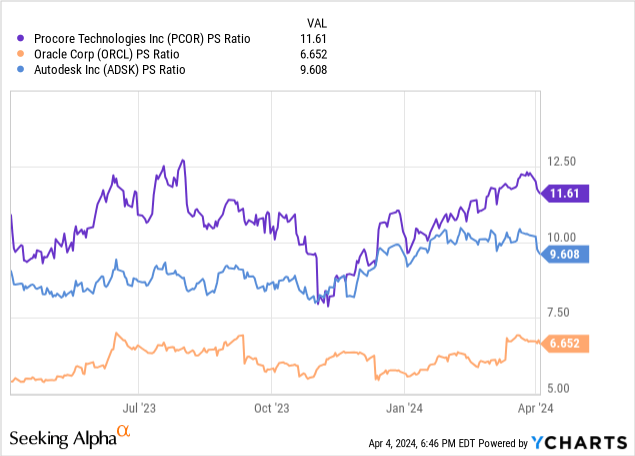
In this case, Procore does appear to be trading at a premium compared to the competitors I’ve mentioned above as this graphic illustrates.
However, as Procore is the market leader, I’m willing to pay a premium for industry leader. I would initiate a position at these levels and would happily add should this metric drop.
Conclusion
Procore is a leader within a niche marketplace and is growing revenue as well as client count.
Procore has a founder-led CEO with years of experience in the construction industry and who has a considerable stake in the business. Employees seem to really approve of Courtemanche too and the working environment he and the management team have created as Procore is viewed as one of the top companies in the country to work for according to Glassdoor.
As the construction industry isn’t as “digitalized” as other industries and is highly fragmented Procore seems to a large opportunity to continue to grow as long as the company can continue to deliver stellar technology and retain clientele.
I believe Procore can be an excellent opportunity for long-term investors as I think this founder-led company can continue to grow in the years to come.
Credit: Source link