
Carsten Koall/Getty Images News
Elevator Pitch
Tuya Inc. (NYSE:TUYA) [2391:HK] shares are rated as a Buy.
I wrote about TUYA’s financial performance for Q3 2023 and the company’s approach towards capital allocation in my earlier update published on November 29, 2023. For the latest article, I analyze Tuya’s valuations, its near term prospects, and its long term growth potential.
My analysis leads me to the conclusion that TUYA’s outlook for the short term and long run is favorable, which isn’t reflected in its current valuation metrics. Therefore, I have made the decision to raise my rating for Tuya from a Hold to a Buy.
Valuations Haven’t Factored In Financial Performance Improvement
At Tuya’s investor call hosted by Water Tower Research on January 11, 2024, the company commented that valuations for “U.S. listed (software) companies” on average has de-rated from 13 times price-to-revenue to 5 times price-to-revenue in the past couple of years despite the “recovery of both the economy and the capital markets.”
The company’s comments at this recent investor event highlighted above send a clear message that there is a disconnect between the valuations and financial performance of IT businesses such as TUYA.
Tuya’s consensus next twelve months’ price-to-sales or P/S valuation multiple had compressed from above 30 times in May 2021 (the time when sell side coverage had begun) to 3.9 times now as per S&P Capital IQ. The consensus next twelve months’ Enterprise Value-to-Revenue ratio, which adjusts for the company’s net cash ($961 million as of September 30, 2023), for TUYA is an even more appealing 0.85 times (source: S&P Capital IQ).
TUYA’s financial performance has become better in recent quarters, but this doesn’t appear to have been factored into the stock’s valuation metrics.
The company recorded YoY top line contraction for six straight quarters running between the first quarter of 2022 and the second quarter of 2023. But Tuya turned the corner in Q3 2023 with a +7% QoQ and +36% YoY growth in revenue for that quarter. TUYA also achieved a gross profit margin of 46.7% for both Q2 2023 and Q3 2023, which represent the highest gross margin for the company in its history.
I am of the view that Tuya will be able to trade at a higher valuation multiple in due course. This assumes that TUYA’s upcoming fourth quarter results release is positive and the market has a better appreciation of the company’s long term growth runway which are detailed in the subsequent sections.
Q4 2023 Financial Results Preview
TUYA will release its Q4 2023 results next week on Tuesday, February 27, 2024 after trading hours.
The market thinks that Tuya would have done well in the final quarter of 2023. TUYA’s revenue and normalized net profit are estimated to increase by +36.3% and +282.0% (source: S&P Capital IQ), respectively on a YoY basis for Q4 2023. TUYA’s actual Q3 2023 top line and bottom line grew by +35.7% YoY and +163.3%, respectively. In other words, the sell side analysts see Tuya reporting a better set of results for Q4 2023 as compared to Q3 2023.
Tuya’s management commentary at the Water Tower Research investor presentation in January 2024 offers favorable read-throughs for the company’s performance in Q4 2023.
With respect to the top line growth outlook, TUYA indicated at the January 11, 2024 investor call that the company’s revenues prospects have been boosted by its observation that the “destocking inventory cycle has come to an end globally.” As a validation of Tuya’s views that the worst is over for the IoT (Internet of Things) market, Impinj (PI), which Barron’s describes as a “internet-of-things chip” businesses, recently announced above-expectations top line with its revenue expanding by +8.7% QoQ in Q4 2023.
Tuya’s Historical Quarterly Gross Margins
Tuya’s Investor Presentation Slides
TUYA’s Historical Quarterly Operating Costs
Tuya’s Investor Presentation Slides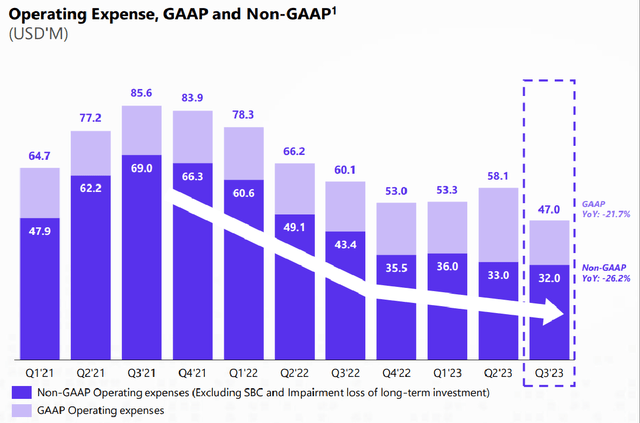
In terms of the expectations for future profitability, Tuya stressed at the January 2024 investor event that it remains committed to the “continuous improvement of gross margin” and emphasized it will stay “disciplined on managing the operating expenses.”
In a nutshell, I share the analysts’ optimism regarding TUYA’s Q4 2023 financial results.
Growth Prospects For The Long Run
TUYA calls itself “the largest Internet-of-Things cloud development platform provider” in the company’s investor presentation slides.
Tuya’s claim to be the biggest player in its space is supported by the size of its client base and the number of developers it works with as presented in the chart below.
TUYA’s Key Statistics At A Glance
Tuya’s Investor Presentation Slides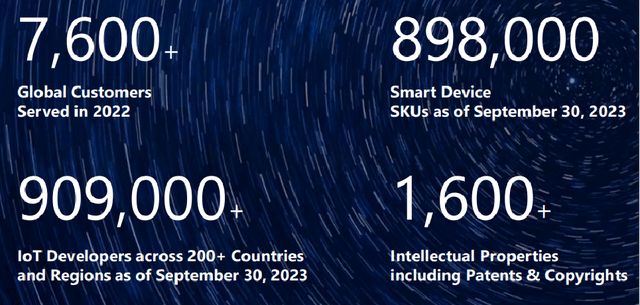
Also, TUYA boasted a 14.9% of share of global IoT PaaS (Platform-as-a-Service) sales in 2021, based on data provided by China Insights Industry Consultancy or CIC.
The Revenue Share For Tuya And Its Rivals In The IoT PaaS Sector
Tuya’s Hong Kong Listing Prospectus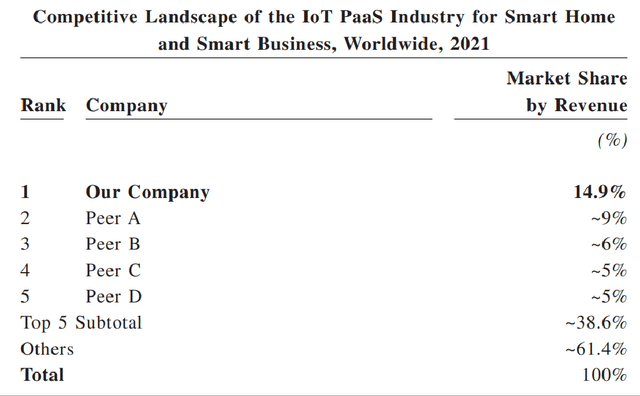
International Data Corporation or IDC projects that the amount of monies invested in IoT globally will expand at a CAGR of over +10% for the 2023-2027 time frame and exceeded the $1 trillion mark by 2026. IDC’s bullish growth forecasts are consistent with the low penetration rates for IoT. According to research conducted by China Insights Industry Consultancy or CIC, the IoT penetration rates for “smart industries and smart home & business” devices are at the low-teens percentage and mid-single digit percentage levels, respectively.
Apart from the potential for an increase in the IoT penetration rate in the future, another positive long-term growth driver for Tuya is reduced competitive intensity. TUYA shared at the company’s investor event organized by Water Tower Research in the prior month that many “competitors have decided to quit this IoT Cloud business” which translates into a “better competitive landscape for us for the next 10, 20 years.” Specifically, Tuya mentioned that “Google (GOOG) (GOOGL), SAP (SAP), IBM (IBM) and Ericsson (ERIC) (OTCPK:ERIXF)” are among those companies that have exited the IoT cloud space.
In summary, a favorable competitive environment and low industry penetration rates point to a positive long term growth outlook for Tuya.
Final Thoughts
TUYA’s valuations and growth outlook are misaligned. I have a positive opinion of Tuya’s prospects for the short term and long term, and I think that TUYA deserves to command higher valuations. A growth-adjusted price-to-sales multiple (like the PEG ratio but using sales rather than earnings) target of 0.5 times (7.5/15) implies Tuya can be valued by the market at as high as 7.5 times P/S based on its consensus FY 2024-2025 top line CAGR forecast of +15% (source: S&P Capital IQ). In contrast, the stock is trading at a much lower P/S ratio of 3.9 times now.
Credit: Source link