
muratkoc/E+ via Getty Images
The Becoming of A Legacy Bitcoin Miner
About a year ago in July 2022, HIVE Blockchain (NASDAQ:HIVE) was our prime go-to crypto mining company to invest in. It had many advantages over other Bitcoin mining companies. It operates with 100% renewable energy, sub $20,000 total mining cost per Bitcoin (including all business costs), growing Bitcoin (BTC-USD) and Ethereum (ETH-USD) reserves, attractive valuations (trading below adjusted net asset value, NAV), and more. The only major risk we identified was ‘The Merge’, which is Ethereum’s transition to Proof-of-Stake (‘PoS’). Hence, we maintain our strategy to HODL Bitcoin.
Although ‘The Merge’ was imminent, Ethereum’s transition had been delayed for many years. There was no saying how long HIVE can enjoy the high margins from mining Ethereum. Then 2 months later in September, Ethereum’s pivot to PoS is completed. Still, HIVE was adamant about optimistic opportunities to mine other Proof-of-Work (‘PoW’) coins and tokens should Ethereum switch to PoS. We studied and outlined 3 ways we expect HIVE to navigate. So it will be interesting to see how has HIVE fared since ‘The Merge’.
HIVE’s Post-Merge Bitcoin Production
On a high level, Bitcoin production is a function of 2 things: mining capacity and Bitcoin network hash rate (or mining difficulty). We predicted that the production (revenue) will decline by more than 32% due to the mining difficulty differential between Bitcoin and Ethereum.
In 2022Q4 and 2023Q1, HIVE’s Bitcoin production fell by 43%, 10% more than our estimation. In this sense, the 10% additional decline can be attributed to the increase in Bitcoin mining difficulty. HIVE also seemed to agree. In all of HIVE’s monthly updates in 2022Q4, HIVE seemed very conscious about the mining difficulty of Bitcoin to attribute the decline in Bitcoin production to the increased mining difficulty. For example:
The Bitcoin network difficulty saw a total 17% increase during the month of October…
Bitcoin mining difficulty had increased substantively for the month of October relative to the month of September…
The Bitcoin network difficulty was consistent throughout the month of November, with less than +/- 1% variance…
But when mining capacity increased in 2023Q1, HIVE no longer mentioned mining difficulty. We just think that HIVE could be more explicit in attributing the decline in production to mining capacity (Table 1) as well.
Referring to Table 1, HIVE’s production has yet to recover to the pre-Merge level. We think that it is unlikely for HIVE to regain the pre-Merge production level anytime soon. On one hand, the Bitcoin mining difficulty has been increasing by 93% annually since 2021H1. On the other hand, HIVE missed its mid-2023 6.2 EH/s target, and may not have the balance sheet to expand willfully.
In May 2022, HIVE stated that:
HIVE is pleased to provide a market update on the Company’s growth plans for the year ahead. The Company will be at 6.2 Exahash BTC equivalent hashrate in one year, based on contracted monthly deliveries of ASIC and GPU hardware (with deposits in place), up from 3.4 Exahash of BTC equivalent hashrate today.
Note that HIVE used the term ‘equivalent hashrate’, meaning the 6.2 EH/s target also includes Ethereum mining capacity. Since the Ethereum mining capacity is worth less in terms of Bitcoin-equivalent capacity post-Merge, 2022Q3 and 2022Q4 saw a 40% drop (2.06 / 3.4 EH/s, Table 1) in mining capacity. It is not until May that HIVE recovered pre-Merge mining capacity. Even so, Bitcoin production remains below pre-Merge levels due to the increase in mining difficulty. Hence, HIVE’s concern about increasing mining difficulty is well justified.
Table 1. HIVE’s Historical Bitcoin Production and Mining Capacity
|
Quarter (‘CY’) |
Bitcoin-Equivalent Production |
Mining Capacity (EH/s) |
|
2023Q2 |
913.8* |
3.32 |
|
2023Q1 |
792 |
3.08 |
|
2022Q4 |
787 |
2.06 |
|
2022Q3 |
1380.2 |
2.28 |
Source: Author (* indicates estimation extrapolated from May Production)
In June 2023, HIVE resumed its 6 EH/s year-end target. Whether HIVE can realize this target remains to be seen. HIVE currently has $8.6mil in cash and $15.7mil in deposits. We previously estimated that it requires $23mil to add 1 EH/s of mining capacity. Hence, adding another 2.7 EH/s would require about $46mil. Hence, we do not think that HIVE has the balance sheet to meet this expansion target at the moment. Else, we expect to see an increase in liability or outstanding shares (about 13%). In any of the 3 cases, shareholder value will decline.
Implications of HIVE’s Shareholder Equity Decline
If HIVE does not meet the 6 EH/s target, production will decline due to the increased mining difficulty. This lowers the intrinsic value of the company. A decrease in production also increases the mining cost per Bitcoin as many of HIVE’s expenses are fixed expenses. Either HIVE has to offload its Bitcoin reserves to cover expenses or HIVE has to raise equity or liability to cover expenses. These lead to the death spiral.
If Hive raises funds through equity, HIVE’s shareholder equity will decline further. Table 2 showed that HIVE’s book value and book value per share has been declining even before ‘The Merge’. Book value decreased a lot but book value per share decreased even more. An attempt to fund expansion through equity offerings will further decrease HIVE’s book value per share.
Table 2. HIVE’s Declining Shareholder Equity
|
QR(CY) |
Shares Outstanding (mil) |
Equipment ($mil) |
Total Assets ($mil) |
Total Liability ($mil) |
Total Equity ($mil) |
Book Value Per Share ($) |
|
2022Q4 |
82.7 |
93.9 |
189.4 |
48.5 |
140.9 |
1.70 |
|
2022Q3 |
82.53 |
132 |
278.4 |
50 |
228.5 |
2.77 |
|
2022Q2 |
82.2 |
172 |
319 |
60 |
319 |
3.88 |
|
2022Q1 |
77.7 (Post reverse split) |
177.5 |
452 |
63 |
389 |
5.05 |
|
2021Q4 |
388,433,985 |
107 |
487 |
55.1 |
432 |
Source: Author
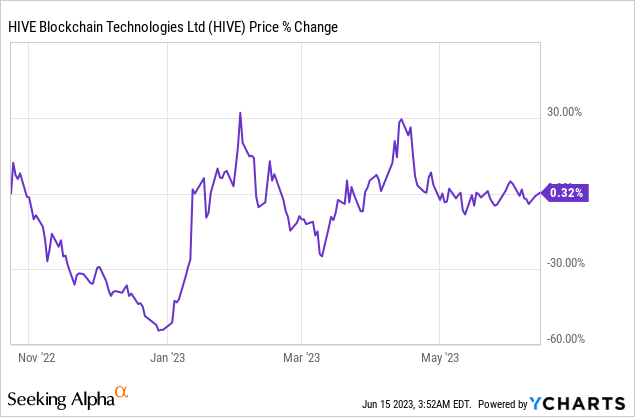
Currently, HIVE’s market cap ($262mil) is 86% higher than its book value. Using our conservative measurement (adjusted NAV) to include only cash, prepaid, equipment, and Bitcoin reserve, HIVE is trading 115% higher than its 2022Q4 book value. Comparatively (Figure below), HIVE’s shares were trading at similar prices back as today in Oct 2022 but it was below book value. In addition, HIVE shareholders lost 68% of shareholder equity since 2021Q4. It is observable that the decline in shareholder equity is caused by the decline in HIVE’s asset value. This implies that HIVE has lesser wiggle room to survive a prolonged Bitcoin downturn and expand mining capacity.
These observations further cement that HIVE shareholder is quickly losing equity. The same can also be applied to funding through liability, which also ultimately reduces shareholder equity.
Mining Efficiency
We’ve previously provided evidence to show that HIVE’s cost basis had de-anchored from the optimal historical average. We also estimated an increase in HIVE’s cost basis due to an increase in energy prices, risk of lesser curtailed energy, and differential of energy usage between Bitcoin and Ethereum mining. In the press release for the 2023Q3 quarter, HIVE has confirmed that HIVE is not likely to regain pre-Merge mining efficiency:
We (HIVE) are sad to see the higher margin from mining Ethereum gone and now will be more easily compared to our Bitcoin mining peers…
We estimated that the total mining cost per Bitcoin would rise to $66,000. Fortunately, HIVE’s total mining cost per Bitcoin only increased to $48,000.
HIVE’s total mining cost is worse than CleanSpark ($33,276, CLSK), Marathon Digital Holdings ($32,100, MARA), and Riot Platforms ($46,200, RIOT). Only Hut 8 Mining (HUT) was found to be worse than HIVE so far due to unsystematic energy woes.
Table 2. HIVE’s Historical Total Mining Cost per Bitcoin
Source: Author
When HIVE’s total mining cost per BTC is observed along with its declining asset value, it could mean that HIVE cannot afford to replace its mining rigs. Furthermore, Bitcoin is currently trading near its total cash expense per Bitcoin ($19,000, excluding depreciation and Stock-based payments). Should the SEC’s lawsuit against Binance and Coinbase (COIN) take a turn for the worse, HIVE might be able to survive another Bitcoin shock.
Given enough time, based on HIVE’s Q2 production update trajectory, we expect HIVE’s total mining cost per Bitcoin to steadily decline to the $30,000 – $35,000 benchmark over time as production slowly picks up. But we do not expect it to go back to pre-Merge levels because operating cost (including depreciation) per Bitcoin alone already stands at $39,000 in 2022Q4.
Valuation & Verdict
As mentioned earlier, HIVE has lost a significant amount of book value since 2021. HIVE is also now trading well above its book value even though HIVE was trading at similar price levels 3 quarters ago. This implies that HIVE has to compensate for this high valuation with a higher level of profitability.
Assuming the 6 EH/s expected capacity, our model suggests that Bitcoin has to trade above $54,414 to justify HIVE’s current valuation. This is not too bad given that Bitcoin has to trade above $50k, $68k, and $62k to justify MARA, RIOT, and HUT’s respective market cap. We maintain that CLSK is still the most attractive undervalued Bitcoin mining company so far, according to our model.
It is very unfortunate that HIVE has to take a few steps back just to pivot away from Ethereum. During this period, CLSK, RIOT, and MARA have expanded aggressively, especially MARA (Table 3). With the industry rapidly expanding mining capacity, HIVE might be left behind. Remember that a Bitcoin miner’s production performance is relative to another other. Unless HIVE finds ways to beef up its balance sheet and expand, HIVE risks becoming a legacy Bitcoin miner that will struggle to survive.
For these reasons, we cannot recommend an investment in HIVE. It is also because of risks like these that we recommend direct investment in Bitcoin over Bitcoin mining companies. Else, you might like to consider CLSK. It’s the only Bitcoin mining company our model currently looks at favorably. We hope that HIVE can recover and prove us wrong. HIVE’s survival can help keep the Bitcoin network as decentralized as possible, which is good for the overall crypto industry.
Table 3. Bitcoin Mining Companies Capacity Comparison
Source: Author (* indicate February Figures)
Credit: Source link