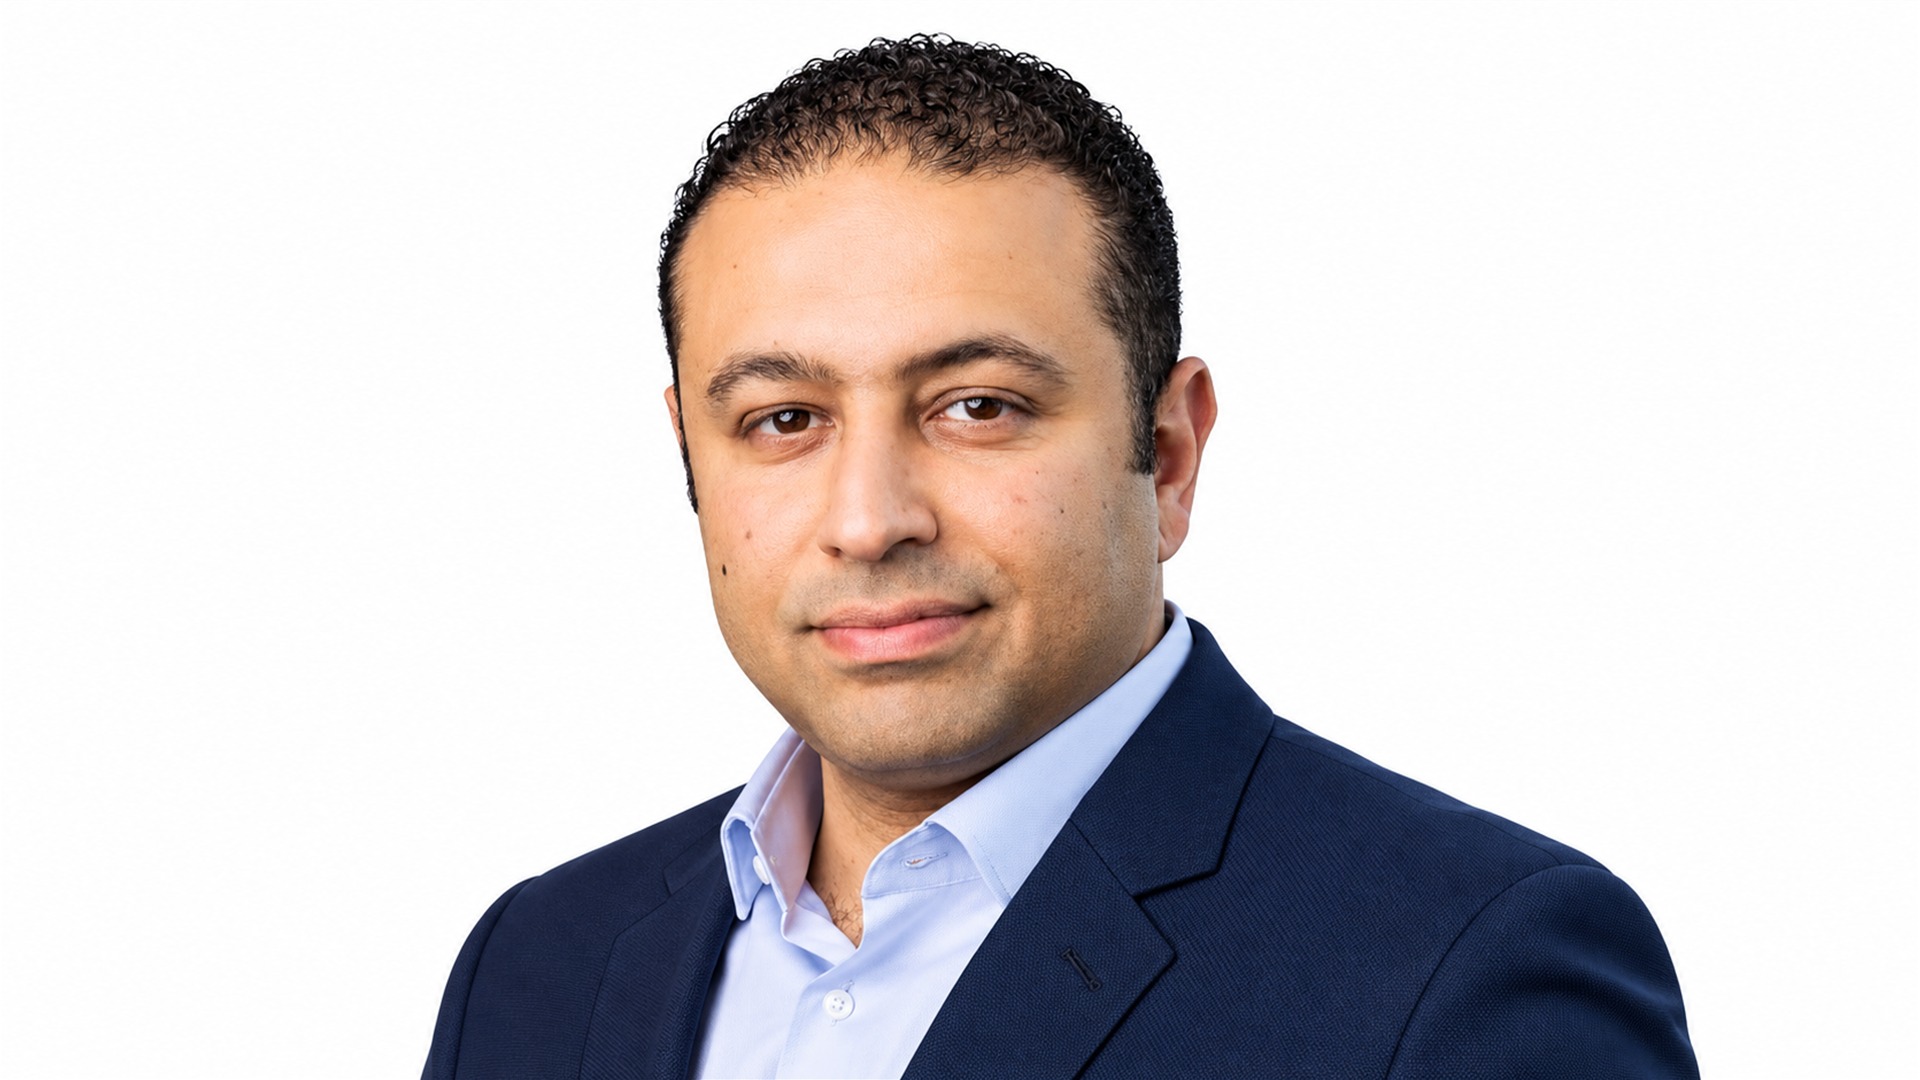

Fady Saad is Founder and General Partner of Cybernetix Ventures, where he invests in early-stage robotics, automation, and industrial AI companies. He also co-founded MassRobotics, helping develop its corporate partnerships and support robotics startups as they moved toward commercialization. His experience connects engineering, business development, and the practical challenges of bringing machines into real operating environments, with an investment approach centered on customer needs and commercially viable deployment.
Cybernetix Ventures is a Boston-based venture capital firm investing in robotics, automation, and industrial AI startups in North America and Europe. Its focus includes manufacturing, logistics, healthcare, construction, and enabling technologies such as perception, autonomy, sensors, and cybersecurity for robotics. In this interview, Saad discusses the opportunities and limits of physical AI, the economics of specialized and humanoid robots, and the reliability, data, and infrastructure needed to turn promising technology into scalable businesses.
You co-founded MassRobotics in 2014, helping build one of the world’s leading robotics innovation ecosystems, before founding Cybernetix Ventures in 2021. What inspired your transition from supporting robotics startups to investing directly in them, and how did your experience at MassRobotics shape your investment philosophy?
I didn’t plan to become an investor. I came into robotics through Vecna, working on R&D and commercialization strategy, and I learned fast that robotics doesn’t follow the software playbook. You can push a software prototype out to users in six months. A robot needs manufacturing, a supply chain, testing, safety work, and a customer willing to let it onto their floor.
That’s why we started MassRobotics in 2014. We called it a startup accelerator because the hard part isn’t building the prototype. It’s getting from a working prototype to a product someone can buy. I ran corporate partnerships, and for over six years I sat in more than 300 corporate meetings and helped build over 40 partnerships. I kept seeing the same picture: corporates with real problems, startups with real technology and almost no investors who understood both.
By 2018 and 2019, it was obvious. VCs were clustered around SaaS or biotech, and robotics founders were the misfits. Too much hardware for software investors, and not enough biology for biotech investors. Good teams were stalling because the right capital didn’t exist. Mark Martin, who I met in 2017 when we brought Analog Devices into MassRobotics, saw the same gap from the corporate side. So we built Cybernetix, a fund that treats robotics as its own asset class, and launched it in 2021.
MassRobotics shaped how we invest in a simple way. We start from the customer’s problem, not the technology. We like teams with at least one founder from the industry they sell into. And we bring our corporate network into every deal, because in this sector the right introduction to a buyer can be worth more than the check.
Physical AI is emerging as one of the most transformative areas of artificial intelligence, bringing intelligence into machines that interact with the real world. What technological breakthroughs are accelerating its adoption, and why do you believe the industry is reaching an important inflection point?
Two things moved at the same time. The brains got much better, and the bodies got much cheaper.
On the software side, foundation models gave robots something they never really had: the ability to take an instruction and handle situations they weren’t explicitly programmed for. Simulation lets teams train and test thousands of scenarios before a robot ever touches a real factory. On the hardware side, sensors, edge compute, actuators, and batteries keep getting cheaper and better, so a startup can build a full-stack robot without being an industrial giant.
Then there’s demand: labor shortages in manufacturing, logistics, agriculture and construction, an aging workforce, and a real push to bring production back home. I always say the labor shortage is an economic problem, not an engineering problem, and boards are treating it that way now.
So yes, it’s an inflection, but I’d be precise about where. Capability and capital have inflected; deployment at scale has not. ChatGPT runs on 20 or 30 years of digitized human knowledge and there’s no equivalent for the physical world. No dataset tells a robot that you need to hold an egg, a sheet of paper, or a piece of cloth differently. The companies that close that data gap, by deploying in real environments and learning every shift, will define the next phase.
Investment in robotics and physical AI has accelerated, driven by advances in AI, labor shortages, and growing demand for automation. What is fueling investor enthusiasm, and how much of this momentum reflects genuine commercial opportunities versus speculative excitement?
I think it’s both and investors don’t help anyone by pretending otherwise.
The demand is real. Deloitte and the Manufacturing Institute project U.S. manufacturers could need up to 3.8 million workers by 2033, with about 1.9 million of those jobs at risk of going unfilled. That’s not hype. That’s a hole in the economy.
The capital is a different story. Crunchbase counted $18.8 billion invested in robotics startups in the first half of 2026, more than all of 2025. But PitchBook saw deal count drop in the second quarter while dollars hit a record, which tells you a handful of mega rounds are absorbing most of it. A lot of that money is buying a narrative: mostly humanoids and general-purpose robot models.
My filter is boring on purpose. Does the customer buy again after the pilot? Does the robot hit the reliability the job needs, which on a production line is 99.99%, not 90%? Is there real revenue within a year or so? If the answers are yes, that’s a business. If the pitch is mainly about what the robot might do in 2030, that’s speculation priced like a certainty. Robotics has been through this cycle before, and the companies with paying customers come out of the shakeout stronger.
Cybernetix Ventures is raising its second fund to expand investments in early-stage robotics and AI companies. How has your investment thesis evolved since launching your first fund, and which emerging technologies or industries are attracting the greatest interest from institutional investors?
The core belief hasn’t changed. Value in physical AI is captured where software meets real-world deployment, and the best robots are built backward from a specific problem. Fund II doubles down on that.
What’s changed is the map. Fund I focused on manufacturing, logistics, construction, and healthcare. Fund II keeps those and adds agriculture, energy and climate infrastructure, space, and defense as well as dual-use technology. The mix stays roughly two-thirds full-stack robotics companies and one-third enabling technology, things like AI models, perception and machine-to-machine cybersecurity. Our first Fund II checks went into a space robotics company and a perception model company, which tells you where the new generation is heading.
We also look hard at things that barely came up in 2021 – like where the components come from, how exposed the supply chain is to China, and how secure the robot is once it’s networked.
From institutional and corporate investors, I hear two questions most. First, corporates ask how to get a window into a market they can’t build internally, which means scouting, market intelligence, and co-investment. Physical AI has become a CEO-level priority at a lot of these companies. But family offices and institutions ask something more direct: why not just get into one of the big humanoid or robot model rounds through an SPV? My answer is that those are crowded, expensive, capital-hungry bets. The asymmetric returns are earlier… in companies the generalists haven’t found yet. That’s where a specialist earns its keep.
Humanoid robots have attracted enormous attention and investment, with companies such as Tesla and Figure AI pursuing increasingly ambitious capabilities. You’ve expressed skepticism about their commercial viability. Where do you believe investors are overestimating their near-term potential, and do specialized robots offer a more compelling investment opportunity?
I’m skeptical of the timeline, not the technology. My rule is form follows function. If the job is moving parts or pick and place, ask whether you need a very complex, very expensive two-legged machine, or an arm, or two arms on a mobile base. On a flat warehouse or factory floor, legs don’t buy you much. They add cost, draw power, and rely on a robot that can fall.
Where investors overestimate humanoids is the near-term math. Valuations assume broad deployment soon, but the hard problems are still open – such as dexterous hands, touch and force feedback, batteries that last a few hours, and an AI stack that’s repeatable and traceable. A 10% error rate is fine in a chatbot. In a plant, one wrong move can hurt someone or cost a customer millions. I expect meaningful volume shipments in five to 10 years, not next year.
Humanoids make sense where the environment was built for people and can’t be redesigned. Space is my favorite example. NASA charges commercial users about $130,000 for one hour of astronaut time, so a robot that can work inside a station designed for humans pays for itself fast. Nuclear sites, disaster response and some defense work follow the same logic.
So in the near term, yes, specialized robots are the better risk-adjusted bet. They’re shipping and getting paid today.
While humanoid robots dominate headlines, Cybernetix Ventures focuses on practical applications across manufacturing, healthcare, logistics, and construction. Which industries offer the greatest near-term economic impact from physical AI, and where are you already seeing measurable returns on automation investments?
The fastest impact shows up where three things meet: an expensive problem, a labor gap, and a buyer who measures results in dollars.
Manufacturing comes first, especially existing plants. Most factories can’t be rebuilt around robots. A company with hundreds of sites needs automation that fits the building it already has. That’s why AI vision that lets existing robot arms pick messy, shiny or transparent parts is so valuable. It upgrades what’s already on the floor.
Logistics is the most mature market, with clear ROI (return on investment) in picking, moving and loading. Even so, reliably picking any single item out of a mixed bin still isn’t fully solved.
Healthcare and life sciences are underrated. Automated labs turn slow, manual work into faster, reproducible results, and drug developers already know how to pay for faster answers.
Construction is at an earlier stage, but it has one of the worst labor shortages of all. Narrow jobs like layout and material hoisting are where robots are earning their keep.
Where I see measurable returns, it’s almost always the same pattern: one narrow job, done more reliably, with payback the customer can see in its own numbers, not in a five-year slide.
Advances in foundation models, computer vision, reinforcement learning, and simulation are transforming robotics capabilities. Which AI innovations do you consider most consequential over the next five years, and what technical limitations still prevent widespread deployment in unpredictable real-world environments?
Over the next five years, I’d watch four things.
Robot foundation models, especially those connecting vision, language, and action. But I expect them to win domain by domain, not as one model for everything. The path is a single purpose, then a scope of use cases, then maybe a whole domain — say, single-family home construction. I don’t believe one model will run construction, manufacturing and healthcare.
Simulation, because it makes training cheap. But simulation gets you to 80% or 90%. The last 10% is where robots drop things and hit things.
Touch. Vision is great for understanding the environment. But if you want to change the world, you have to feel it. Tactile sensing and better hands matter because manipulation is where most real work happens.
Data infrastructure. In autonomous vehicles, a generation of companies like Scale AI built big businesses collecting and labeling data, and Applied Intuition built one on simulation. Physical AI will produce its own version, and it’s one of the biggest opportunities in the space.
What still blocks deployment in messy, unpredictable environments is reliability and trust. Factories need 99.99%. Safety standards, certification and insurance haven’t caught up for mobile robots working around people. And every connected robot is a cybersecurity problem that very few people are pricing in yet.
Cybernetix Ventures has invested in companies such as Cambrian Robotics, Dash Bio, and Rugged Robotics. What attracted you to these companies, and what distinguishes a promising robotics technology from a commercially scalable business?
All three started from a customer’s problem, not from a cool demo.
Cambrian Robotics. Machine vision is crowded, but Cambrian reliably picks small, shiny and transparent parts that trip up most systems. It works with the major industrial robot brands, installs in about half a day, and was already being tested and deployed with manufacturers like Toyota, Audi and Electrolux when we co-led its seed round in 2024.
Dash Bio. Drug developers send a lot of their bioanalysis to outside labs that still run largely by hand. Dash built a highly automated lab, compliant with GLP (Good Laboratory Practice) standards, that combines robotics, AI and software to run key assays up to 10 times faster. They aren’t selling robots. They’re selling faster answers, which customers already know how to buy.
Rugged Robotics. On a construction site, someone still marks by hand where every wall, pipe and fixture goes. It’s slow, and mistakes get expensive once the walls go up. Rugged’s robot prints the drawings directly onto the floor. One narrow job, done faster and more accurately, on sites that can’t find enough skilled people.
What separates a promising technology from a scalable business? Ninety-nine percent of the time, starting with a shiny technical achievement and then hunting for a use case is a formula for a struggling company. The ones that scale start with the problem and work backward to the machine, the way Kiva, Locus and Universal Robots did. After that, I look for a customer who buys again after the pilot, deployment that doesn’t need a PhD on site, unit economics that hold at volume and a team that hits its milestones. Plenty of robots are impressive. Far fewer are businesses.
As physical AI becomes more capable, concerns about workforce displacement, safety, and human oversight are growing. Do you see robotics primarily addressing labor shortages and augmenting human workers, or do you anticipate significant workforce disruption as adoption accelerates?
In the near term, it’s mostly filling gaps. In the factories, warehouses, labs and job sites we work with, the constraint is people, not demand. Jobs sit open for months.
Verve Motion, one of our portfolio companies, is the example I come back to. They make a soft exosuit that takes much of the strain off workers who lift heavy loads all day. A warehouse worker told the team that he finally had energy to play with his kids when he got home. That’s robotics doing good in the world, and it isn’t replacing anyone.
I won’t pretend there’s no disruption. The most repetitive roles will shrink, and work will change faster than our training systems are built for. The honest answer is to invest in reskilling now, for technicians, operators and the people who maintain robot fleets. Every robot that ships creates work for someone who installs, programs and fixes it.
On safety, robotics actually has a head start on software AI. Industrial robots have lived under safety standards and certification for decades. As robots get smarter, that culture has to carry over: clear accountability, secure machines and people in control of critical decisions.
Looking ahead to 2030 and beyond, which developments in physical AI and robotics do you believe will have the greatest impact on the global economy? Are there any overlooked investment opportunities or emerging applications that deserve considerably more attention?
By 2030, I think three things will matter most for the global economy.
Robots that learn on the job will finally bring automation to small and midsize manufacturers who could never afford custom integration. That’s where most of the industrial base actually sits.
Automated labs will speed up science, with biology and drug discovery running around the clock.
And the supply chain for robot components — actuators, motors, sensors and gears — will become strategic. Most humanoid makers don’t build those parts. They design, integrate and assemble, and much of that supply sits in China and Japan today. Whoever builds that base in the U.S. and allied countries will matter a lot.
What’s overlooked is the plumbing: physical-world data collection, simulation and testing, fleet management, perception, and machine identity and cybersecurity, so robots can trust each other and the networks they run on. Also, the vertical applications in labor-starved industries nobody writes headlines about, like agriculture and construction.
The headlines will be about humanoids. A lot of the money will be made in the plumbing. And in the end, what counts is the societal impact, not the technological impact.
Thank you for the great interview, readers who wish to learn more about robotics, physical AI, and early-stage investment in automation should visit Cybernetix Ventures.
Credit: Source link