alexsl/iStock via Getty Images
By Elisa Mazen, Michael Testorf, CFA & Pawel Wroblewski, CFA
Tilting Toward Domestic Business Models
Market Overview
International equities maintained positive momentum in the second quarter as Europe signaled progress on fiscal stimulus and reform measures and investment flows into the region increased. The benchmark MSCI EAFE Index advanced 11.8%, besting its U.S. counterpart, the S&P 500 Index (+10.9%), for the second-straight quarter. Non-U.S. currencies continued their rally against the dollar with developed market currencies up anywhere from 4% for the Japanese yen to 11.5% for the Swiss franc with the U.S. Dollar Index nearing a three-year low. In a sign of strengthening local market conditions outside the U.S., the MSCI EAFE Small Cap Index jumped 16.6% while the MSCI Emerging Markets Index advanced 12.0%.
Improving sentiment over global trade following President Trump’s early April Liberation Day U.S. tariff announcement raised investor appetite for risk, helping international growth stocks outperform their value counterparts for the first time since the first quarter of 2024. The MSCI EAFE Growth Index gained 13.5% for the period, besting the MSCI EAFE Value Index by over 340 basis points (Exhibit 1).
Exhibit 1: MSCI Growth vs. Value Performance
As of June 30, 2025. Source: FactSet.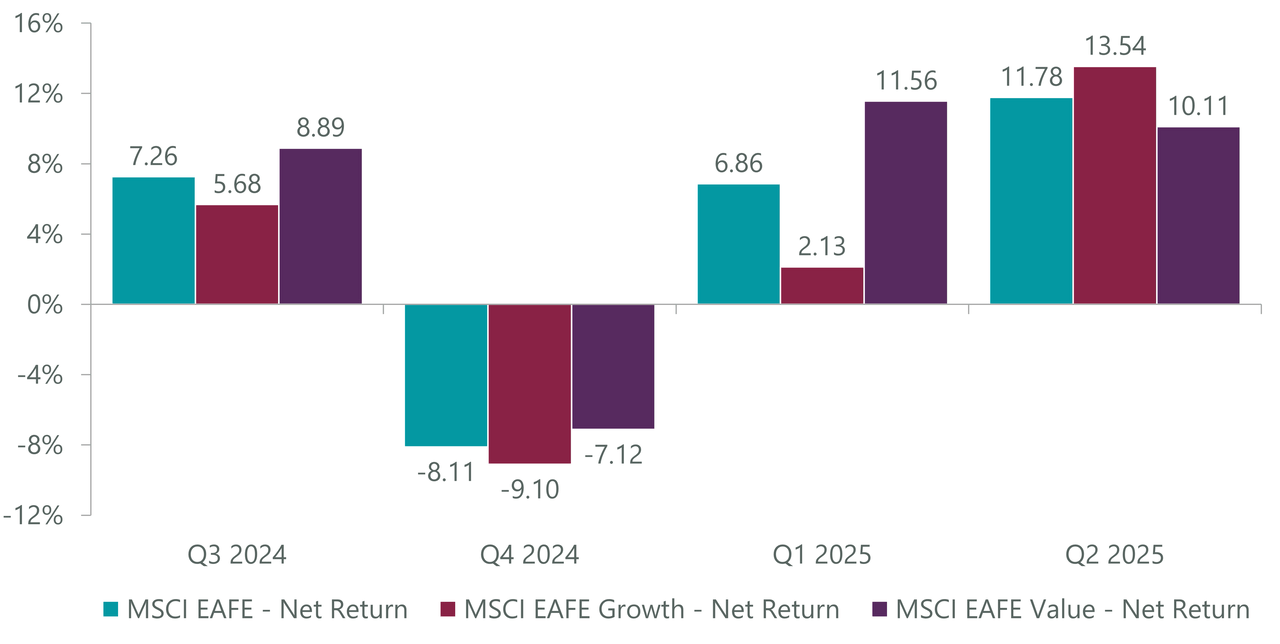
The ClearBridge International Growth ADR Strategy performed mostly in line with its MSCI EAFE benchmark in the second quarter, boosted by solid contributions in Japan, Canada and Europe Ex U.K. that offset weakness among our U.K. holdings.
Global macro conditions were supportive during the quarter. Eurozone GDP expanded at a 2.5% annualized rate in the first quarter, its best pace since 2022, while inflation continued to moderate, with the annual rate slowing from 2.2% in April to 1.9% in May, edging below the European Central Bank’s 2% target. This allowed the ECB to continue its monetary easing cycle with two rate cuts during the quarter, which brought its key deposit rate to a two-year low of 2%. Compared to the U.S. federal-funds rate of 4.25%, financial conditions remain meaningfully more accommodative on the Continent (Exhibit 2). Meanwhile, rising employment and real income supported consumer spending.
Exhibit 2: Non-U.S. Central Banks Lead Monetary Easing
Note: Future expectations based on futures/OIS market pricing for mid-year 2025. As of June 30, 2025. Sources: Federal Reserve, ECB, BOE, BOC, BOJ, RBA, Bloomberg. There is no assurance that any estimate, projection or forecast will be realized.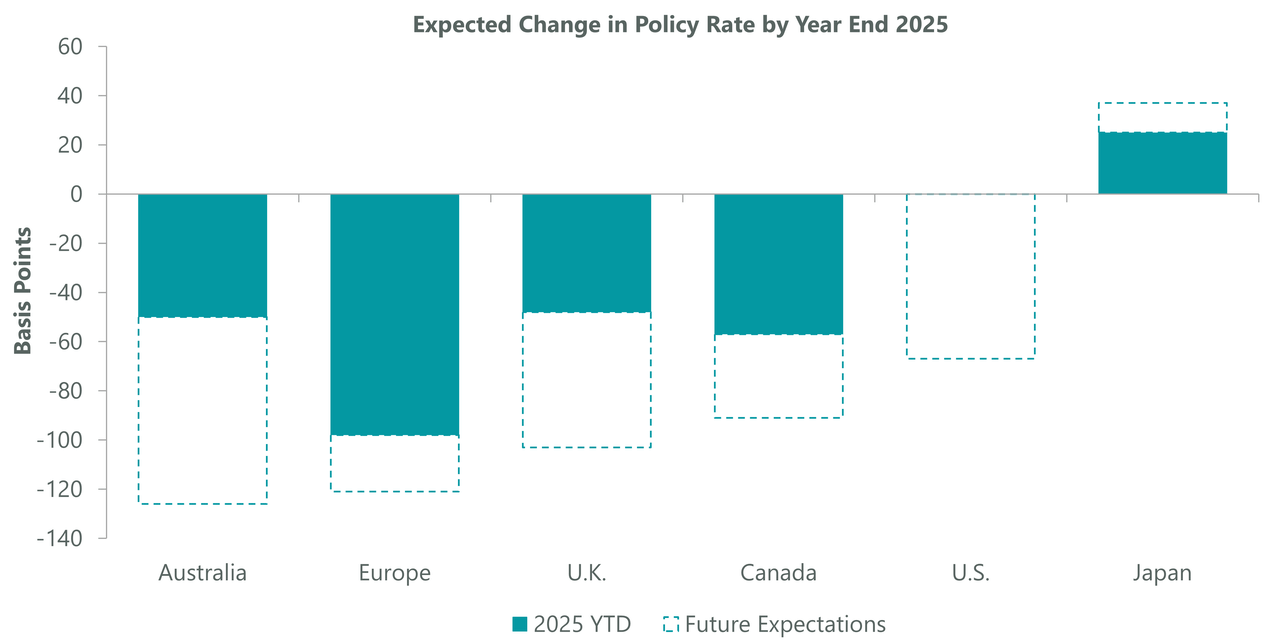
These tailwinds, along with a greater commitment to fiscal spending led by Germany’s new coalition government, whose agenda is expected to include tax cuts and labor reforms, have made Europe a more attractive destination for investors. Inflows of more than $46 billion into European stocks in the first half of 2025 were the second largest on record, according to Bank of America Global Research.
Japan continued a secular shift away from decades-long deflation and negative interest rates, as healthy wage growth and labor market imbalances drove inflation above 2% and government bond yields to their highest levels in 15 years. This macro normalization, in tandem with an acceleration in corporate governance reforms and growing buyback activity, should be beneficial to financials holdings Mitsubishi UFJ (OTCPK:MBFJF)(MUFG) and Tokio Marine (OTCPK:TKOMY)(OTCPK:TKOMF).
Well positioned for the seismic changes underway outside the U.S., the Strategy’s industrials holdings drove relative performance. German electricity equipment and services provider Siemens Energy (OTCPK:SMEGF)(OTCPK:SMNEY) saw its shares rerate thanks to robust second-quarter results as its grid technologies and gas services divisions saw record volumes, its order backlog reached new highs, and the company raised its full-year revenue and margin forecasts.
Companies tied to increasing defense spending in Europe and Japan were also among the Strategy’s leading contributors. Mitsubishi Heavy Industries (OTCPK:MHVYF)(OTCPK:MHVIY) rose on the back of strong fiscal-year revenue and profit gains as well as a healthy outlook for the year ahead. The Japanese conglomerate maintains leading share in the secular growth areas of energy transition, infrastructure investment and the growing security responsibilities of U.S. allies. European aerospace and defense contractors Safran (OTCPK:SAFRF)(OTCPK:SAFRY) and Airbus (OTCPK:EADSF)(OTCPK:EADSY) also rose meaningfully on enhanced defense commitments across their core markets. At a June summit, NATO members pledged to increase defense spending to 5% of GDP, with Germany, France and the U.K. committing to raise defense outlays as the U.S. pulls back from its lead military role in the region.
Companies supporting the buildout of generative AI capabilities also did well, led by semiconductor equipment maker Tokyo Electron (OTCPK:TOELF)(OTCPK:TOELY) and contract manufacturer Taiwan Semiconductor (TSM).
In addition, we were pleased with the rebound in the Strategy’s consumer staples holdings, where we are finding attractive opportunities in the grocery industry such as Tesco (OTCPK:TSCDF)(OTCPK:TSCDY), the leading grocery chain in the U.K., which we added during the quarter.
Financials did well for the portfolio overall, but our Japanese bank Mitsubishi UFJ trailed the market, as did our exchange holdings. With inflation continuing to rise in Japan and the Bank of Japan avoiding raising rates too fast, we believe rate increases will inevitably happen, resuming performance for this part of our portfolio.
One of the hardest-hit areas has been health care. Funding cuts at the National Institutes of Health and academic institutions, the risk of implementation of MFN (most-favored nation) pricing on prescription drugs, turnover at the Department of Health and Human Services, the Food and Drug Administration and other agencies, combined with a weak dollar, have pressured the entire space, most notably pharmaceuticals and medical equipment. Continued weakness due to the presence of GLP-1 compounders and a lack of uptick in prescriptions kept diabetes and obesity drug maker Novo Nordisk (NVO)(OTCPK:NONOF) flat through the quarter. We are approaching a period this upcoming quarter that should give us strong signals as to whether the company can regain its share of this market.
Portfolio Positioning
We continued to actively reposition the portfolio, initiating nine new positions while closing seven others, with many of the changes motivated by concerns over the U.S. economy and U.S. dollar. This led us to sell higher dollar-weighted companies at high prices, including Irish building materials supplier CRH (CRH), and redeploy the proceeds into more domestic businesses that can benefit from the fiscal stimulus in Europe.
U.K. supermarket chain Tesco, in the secular growth bucket, is a good example of a company focused on its home markets of the U.K. and Ireland. Shares sold off in March following widespread price cuts by a U.K. competitor, providing an attractive entry point into a company we believe is best positioned in an industry facing accelerating food inflation. While U.K. discounters have increased competition, Tesco can expand margins through investments in loyalty programs, scale-driven efficiencies and optionality from its wholesale distribution business.
New purchase E.On (OTCPK:EONGY)(OTCPK:ENAKF), a diversified German utility, should benefit from the government’s political consensus for higher investment in grid infrastructure. This commitment should also drive an improved regulatory environment for electricity networks with higher allowed returns to attract capital. In addition to higher returns, E.On should see accelerating asset growth as capex is increasing at a robust pace. We believe a strong balance sheet should further transform the company into a credible structural growth story in utilities underappreciated by investors.
Similar to E.On, new buy BAE Systems (OTCPK:BAESF)(OTCPK:BAESY) should enjoy the tailwind of increased non-U.S. government spending commitments, in this instance for defense. The U.K.’s BAE designs and manufactures a wide range of air, land and naval weapons and defense systems. The company should continue to see its revenues and order intake surprise to the upside while new military programs are expected to increase backlog visibility.
Canada’s Agnico Eagle Mines (AEM) is a best-in-class gold miner that gives provides direct exposure to appreciating gold prices. The company operates only in stable jurisdictions, has industry-best cost inflation management, long-lived assets and balanced production growth financed with internal cash flows. Structural names like Agnico Eagle provide a unique growth exposure as gold is an attractive store of value that protects against uncertainty and inflation and that we believe can serve as a hedge against a weak dollar and geopolitical tensions.
The repurchase of digital services conglomerate Tencent (OTCPK:TCEHY)(OTCPK:TCTZF) is part of our cautious return to China as Beijing becomes more active in supporting economic growth. The company’s valuation is attractive again, with its core gaming business doing well on new game launches. Due to the reach of its content/data ecosystem on WeChat and other platforms, we believe Tencent is well-placed to use AI solutions to accelerate growth through better user experience and advertising growth.
Luxury goods is a meaningful weight in our growth benchmarks within the consumer discretionary sector. Here we exited longtime holding LVMH (OTCPK:LVMHF)(OTCPK:LVMUY) to fund the purchase of Switzerland’s Richemont (OTCPK:CFRHF)(OTCPK:CFRUY). We believe LVMH’s restructuring efforts will take some time, while Richemont’s are recently completed and should lead to improving performance. Additionally Richemont, known for its Cartier, Van Cleef, Buccellati and ultra luxury watch brands, has been an outlier in the luxury industry by not yet aggressively raising prices.
We exited French advertising firm Publicis Groupe (OTCQX:PGPEF)(OTCQX:PUBGY) as our investment thesis has been dampened by increased economic uncertainty and a very challenged advertising industry. The company also faces possible regulatory changes against pharma advertising, and a new existential threat from AI, which can replace thousands of employees at global ad agencies.
Outlook
The regions where we invest across the globe continue to make progress on growth and equity-friendly policies. While still early days in the development of more stimulative economic and regulatory policies, earnings growth among stocks in the pan European Stoxx 600 has begun to improve with forecasts for double-digit EPS growth over the next year.
Exhibit 3: Non-U.S. Earnings on the Rise
Japan represented by the MSCI Japan index, Europe represented by the MSCI Europe index, Emerging Markets represented by the MSCI Emerging Markets index, and United States represented by the MSCI USA index. Data as of June 30, 2025. Sources: FactSet, MSCI. Investors cannot invest directly in an index, and unmanaged index returns do not reflect any fees, expenses or sales charges.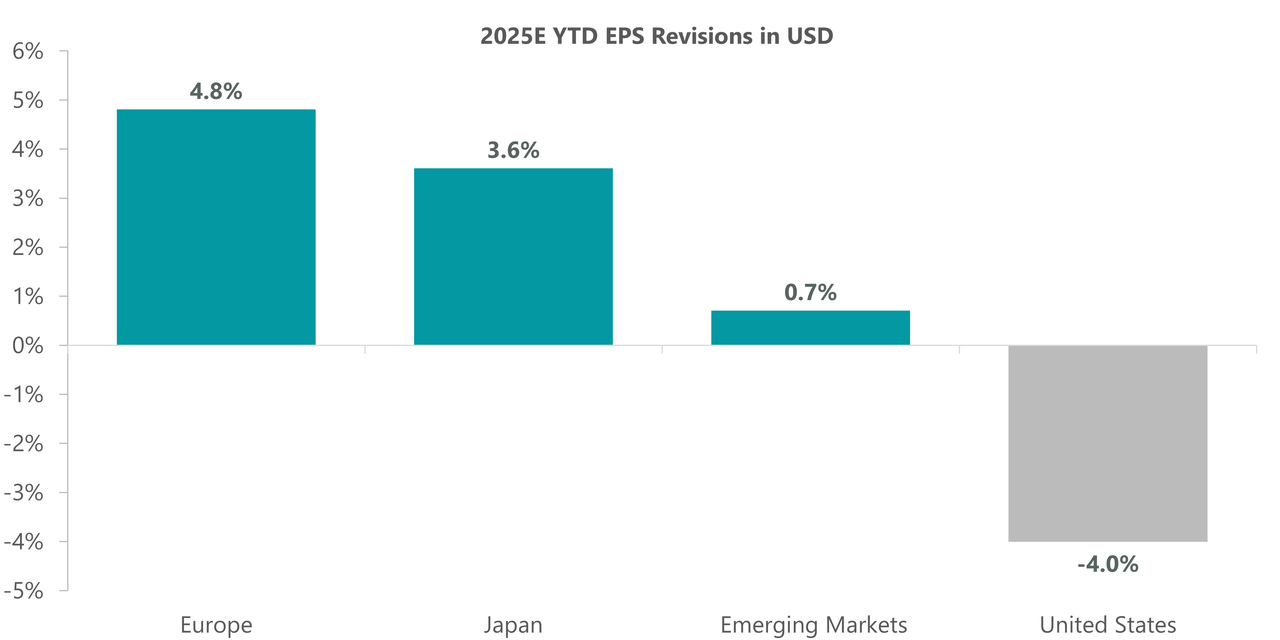
In addition to a more independent EU that has pledged to improve its competitiveness through governance reform and greater investment in research and development, Japan is also taking steps to modernize its economy. Despite its leadership in consumer electronics and robotics, the country has traditionally lagged other regions in digitizing its broader economy. The Japanese government is leading a massive push to transform business functions still done on paper to the cloud and has instituted deadlines for this transition. Companies like IT consulting and software company Nomura Research Institute (OTCPK:NRILY)(OTCPK:NURAF) are helping lead the move to the cloud.
We believe China is also becoming more investable, with its push to develop a self-sufficient health care system leading to a burgeoning homegrown biotechnology industry. As we detail in a new blog, the world’s second-largest economy has the necessary institutional commitment to R&D and life sciences infrastructure to become a profitable global competitor to Western biopharmaceutical companies. We are actively looking at the key players in this rapidly developing market.
Portfolio Highlights
During the second quarter, the ClearBridge International Growth ADR Strategy performed mostly in line with its MSCI EAFE Index benchmark. On an absolute basis, the Strategy produced positive contributions across eight of the nine sectors in which it was invested (out of 11 total), with the industrials, financials and information technology (IT) sectors the top contributors and health care the lone detractor.
On a relative basis, overall sector allocation contributed to performance but was partially offset by negative stock selection effects. In particular, stock selection in industrials and consumer staples, an overweight to IT and a lack of exposure to the energy sector drove results. Conversely, stock selection in the financials, communication services, health care and consumer discretionary sectors detracted the most from performance.
On a regional basis, stock selection in Japan and Europe Ex-U.K. and an overweight to North America contributed to performance while stock selection in the U.K. and overweights to the U.K. and emerging markets proved detrimental.
On an individual stock basis, the largest contributors to relative returns in the quarter were Siemens Energy, Mitsubishi Heavy Industries and Trane Technologies (TT) in industrials, Tokyo Electron in IT and Tesco in consumer staples. The greatest detractors from relative returns included positions in argenx (ARGX)(OTCPK:ARGNF), Novo Nordisk and AstraZeneca in health care, London Stock Exchange Group (OTCPK:LDNXF)(OTCPK:LNSTY) in financials and LVMH in consumer discretionary.
In addition to the transactions mentioned above, we repurchased MercadoLibre (MELI) in the consumer discretionary sector while initiating new positions in AXA (OTCQX:AXAHF)(OTCQX:AXAHY) in financials and Coca-Cola FEMSA (KOF)(OTCPK:COCSF) in consumer staples. Additional sales included Atlas Copco (OTCPK:ATLKY)(OTCPK:ATLCY) and ABB (OTCPK:ABBNY) in industrials and Deutsche Boerse (OTCPK:DBOEY)(OTCPK:DBOEF) and Lloyds Banking Group (LYG)(OTCPK:LLDTF) in financials.
Elisa Mazen, Head of Global Growth, Portfolio Manager
Michael Testorf, CFA, Portfolio Manager
Pawel Wroblewski, CFA, Portfolio Manager
|
Past performance is no guarantee of future results. Copyright © 2025 ClearBridge Investments. All opinions and data included in this commentary are as of the publication date and are subject to change. The opinions and views expressed herein are of the author and may differ from other portfolio managers or the firm as a whole, and are not intended to be a forecast of future events, a guarantee of future results or investment advice. This information should not be used as the sole basis to make any investment decision. The statistics have been obtained from sources believed to be reliable, but the accuracy and completeness of this information cannot be guaranteed. Neither ClearBridge Investments, LLC nor its information providers are responsible for any damages or losses arising from any use of this information. Performance source: Internal. Benchmark source: Morgan Stanley Capital International. Neither ClearBridge Investments, LLC nor its information providers are responsible for any damages or losses arising from any use of this information. Performance is preliminary and subject to change. Neither MSCI nor any other party involved in or related to compiling, computing or creating the MSCI data makes any express or implied warranties or representations with respect to such data (or the results to be obtained by the use thereof), and all such parties hereby expressly disclaim all warranties of originality, accuracy, completeness, merchantability or fitness for a particular purpose with respect to any of such data. Without limiting any of the foregoing, in no event shall MSCI, any of its affiliates or any third party involved in or related to compiling, computing or creating the data have any liability for any direct, indirect, special, punitive, consequential or any other damages (including lost profits) even if notified of the possibility of such damages. No further distribution or dissemination of the MSCI data is permitted without MSCI’s express written consent. Further distribution is prohibited. Performance source: Internal. Benchmark source: Standard & Poor’s. |
Original Post
Credit: Source link