
ugurhan
Obsidian Energy’s (NYSE:OBE)(TSX:OBE:CA) Q2 2024 results were solid, with production averaging 35,773 BOEPD despite a negative impact of 1,550 BOEPD from blockades.
Obsidian’s dispute with the Woodland Cree First Nation has been resolved with an agreement that lasts until the end of 2025. This clears Obsidian to achieve significant heavy oil production growth during the second half of the year, although weaker oil prices may limit its free cash flow.
Obsidian appears to be a pretty solid value now, with estimated upside to US$8.50 per share in a longer-term US$75 oil scenario. Risks include the reduced near-term free cash flow (due to weaker oil prices) and relatively high credit facility utilization after its Peace River acquisition.
This report uses US dollars unless otherwise noted, along with an exchange rate of US$1.00 to CAD$1.35.
Dispute Resolution
Obsidian was in a dispute with the Woodland Cree First Nation, but ended up reaching an agreement in early-to-mid June with the aid of a mediator. The terms of the agreement were not released, but the agreement ended the blockades and allowed Obsidian to restart the affected Peace River production. The agreement runs until the end of 2025.
The blockades ended up reducing Obsidian’s Q2 2024 production by around 1,550 BOEPD, which translates into approximately 385 BOEPD of full-year impact.
Obsidian had previously incorporated a 200 BOEPD full-year impact from the blockades in its production guidance. I had noted that the blockades would need to be lifted by the end of May to limit the impact to 200 BOEPD and that there was a risk of a greater impact to full-year production.
2H 2024 Outlook
Obsidian averaged 35,773 BOEPD in Q2 2024 despite the impact of the blockades. I am currently modeling its 2H 2024 production at 37,400 BOEPD, which would get it to near 200 BOEPD below the mid-point of its full-year guidance. That 200 BOEPD difference reflects the additional impact of the blockades lasting into early-to-mid June.
2024 Production (obsidianenergy.com (August 2024 Presentation))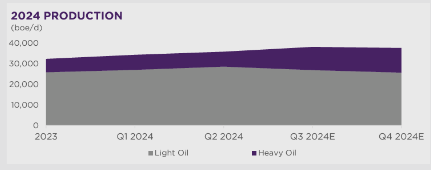
Obsidian’s production growth is being fueled by heavy oil, which may grow to around 11,400 barrels per day in 2H 2024 due to its Peace River acquisition plus development efforts.
The current strip for 2H 2024 is approximately $71 to $72 WTI oil. At that oil price, Obsidian may be able to generate around US$291 million in 2H 2024 revenues after hedges. Obsidian was unhedged on oil after August, but has some AECO hedges until March 2025.
|
Type |
Units |
$ US/Unit |
$ Million US |
|
Light Oil And NGLs [BBLs] |
2,774,720 |
$60.00 |
$166 |
|
Heavy Oil [BBLs] |
2,097,600 |
$49.00 |
$103 |
|
Natural Gas [MCF] |
12,055,680 |
$1.20 |
$14 |
|
Hedge Value |
$8 |
||
|
Total Revenue |
$291 |
This results in a projection of US$155 million in 2H 2024 EBITDAX for Obsidian.
|
$ Million US |
|
|
Revenue |
$291 |
|
Less: Operating Expense |
$72 |
|
Less: Transportation |
$19 |
|
Less: Royalties |
$37 |
|
Less: Cash G&A |
$8 |
|
EBITDAX |
$155 |
Based on Obsidian’s full-year capex budget, it expects around US$120 million in 2H 2024 capex. Obsidian also expects approximately US$20 million in combined decommission expenses and interest costs for 2H 2024.
Thus Obsidian may be able to generate around US$15 million in 2H 2024 free cash flow. It had around US$320 million in net debt at the end of Q2 2024, so the free cash flow could reduce its net debt to around US$305 million by the end of 2024. This does not take into account potential spending to repurchase more shares.
Obsidian’s net debt at the end of 2024 is expected to be around 1.0x annualized 2H 2024 EBITDAX, which appears reasonable. However, Obsidian had over 80% utilization of its credit facility at the end of Q2 2024 after paying for its Peace River acquisition, so it will likely want to reduce that u.
Estimated Valuation
I now estimate Obsidian’s value at approximately US$8.50 per share. This is based on US$75 WTI oil after 2025 and a roughly 3.0x EV/EBITDAX multiple at Obsidian’s 2H 2024 production levels.
This also assumes current strip (of about US$66 WTI oil in 2025), with Obsidian’s value adjusted for the relatively lower projected free cash flow next year.
At 2H 2024 production levels, Obsidian should be able to generate around US$340 million EBITDAX over a full year at US$75 oil.
Obsidian had discussed ramping up production to 42,000 BOEPD in 2025 and 50,000 BOEPD in 2026, but due to the lower strip prices I have assumed that it will reduces its growth plans in favor of more free cash flow generation.
Obsidian’s Peace River results continue to be encouraging, with its Dawson 5-27 Pad averaging an IP-30 of 293 barrels of oil per day per well (over two wells). Early results for its three well Dawson 13-13 Pad involved IP-15 of 336 barrels of oil per day per well.
Conclusion
Obsidian Energy is expected to grow its heavy oil production to around 12,000 barrels per day by Q4 2024. It previously expected to grow heavy oil to 24,000 barrels per day by 2026, but may reduce its growth expectations to prioritize free cash flow generation if oil prices remain weak. At current 2025 strip of around US$66 WTI oil, Obsidian may realize in the mid-$40s (US dollars) for its heavy oil.
Obsidian’s stock should have decent upside even without significant production growth though. I estimate its value at US$8.50 per share in a long-term US$75 WTI oil scenario based on 2H 2024 production levels.
Credit: Source link