
bjdlzx
The last article focused on the beginning of Spartan Delta (OTCPK:DALXF) after the company sold a major portion of the business to Veren (VRN) and then spun off Logan Energy (OTCPK:LOECF). The result was a company the fraction of its original size with a core business that it could concentrate on developing. However, this fiscal year is likely to feature a fair amount of optimization as these properties likely did not get the attention that was needed when the company was much larger.
Earnings comparisons are not going to mean a lot just yet, although the properties retained did have cash flow. Clearly, the comparison to the previous fiscal year is largely irrelevant because the company was materially different. But whenever a company reorganizes itself as this one did, then several quarters are needed for the one-time items to fade away.
Existing Production
Much of the existing production is likely obtained from drilling and completion methods that are antique. This is an area that is undergoing a revival because technology advances have “revolutionized the play”.
(Note: Spartan Delta is a Canadian company that reports using Canadian Dollars unless otherwise noted.)
Spartan Delta Deep Basin Business Summary (Spartan Delta Corporation Presentation August 2024)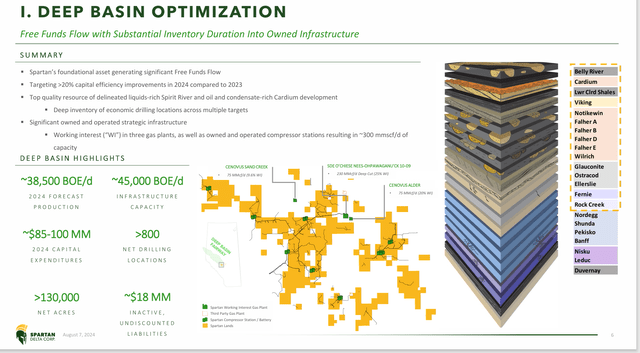
As shown above, that is exactly what management intends to do first. Shown above is the likely cash flow machine that has growth prospects as well, depending upon how the future unfolds. Optimization comes first and then comes drilling using the latest completion methods as well to get a more valuable production mix.
It was mentioned that the pace of drilling will slow due to lower natural gas prices. However, this company, like many gas producers, intends to find liquids-rich areas to drill in the future. The dependency on dry gas production is steadily lessening throughout the industry.
There are many natural gas producers with dry gas acreage. But the price level of natural gas for about 10 years now has been anything but good. Brutal is probably a far better word, with brief interruptions of pleasant surprises. Therefore, many of these producers are looking for a production stream that is more valuable so it can provide a better cash flow during fiscal downturns.
New Core Area
In addition to what is shown above, the company has acreage in another area that is virtually undeveloped compared to the acreage shown above.
Spartan Delta Description Of New Core Area Duvernay West (Spartan Delta Corporation Presentation August 2024)
This particular group of leases represents a major departure from the existing business. The talk about oil and condensate rich means that these liquids are likely to become a major part of the business, with a production mix percentage far in excess of the current beginning situation.
The other thing to note is the exceedingly low cost of the acreage acquired. In the United States, Permian acreage sells for closer to $50K an acre. Given the cheaper Canadian dollar, that acreage is dirt cheap. It is even better when management mentions that there is transportation nearby.
The cheap location cost will show as a more profitable company. Land itself does not depreciate. However, capital is spent to buy land. Many wells in Canada are every bit as competitive as the ones in the United States. Therefore, less capital for the same returns results in higher profitability.
Latest Acquisition
In May, the company closed on some additional acreage in this area.
Spartan Delta Latest Acquisition (Spartan Delta Corporation Presentation August 2024)
The company intends to be a consolidator. So, it will be growing through a combination of acquisitions and organic growth. Since this management had a much larger company in the recent past, the growth should not pose much of a challenge.
Updated Guidance
It is likely the lower natural gas prices shifted the strategy in the fiscal year towards more liquids. As a result, there is change in the production forecast made necessary by the acquisition combined with industry conditions.
Spartan Delta Revised Guidance (Spartan Delta Corporation Presentation August 2024)
Management previously announced that a fair number (if not most or maybe all) of the new wells drilled in the second half would be in the oil window or at least liquids-rich. That increase in oil and condensate production may well be revised further as the fall campaign gets underway.
The “name of the game” when heading towards liquids-rich or hopefully even better is to keep the very low natural gas costs when possible while adding the more valuable liquids-rich products to the production mix. At this point, the natural gas producer sees most of the additional production value head straight to the bottom line, with only a few additional deductions along the way. The increase in profitability would be fairly significant quickly.
Canada also has some amazingly low-cost dry gas acreage that is profitable under some very extreme conditions. That means that the current strategy is designed to allow the company to thrive under a wider variety of conditions. Depending upon how the future unfolds, the company’s production mix is likely to be very different from what is currently being reported.
Summary
The original Spartan Delta management has basically split into two parts. Where the better part of management is would be up for discussion. Right now, both parts look fairly encouraging.
Spartan Delta Management History (Spartan Delta Corporation Presentation August 2024)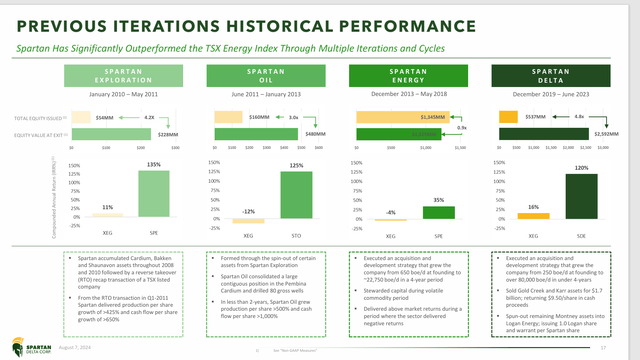
It should be noted that both boards of directors have members from the other company. In any case, the management took part in the past history shown above that really takes a lot of the new company risk out of the equation.
Risks that are normally a concern about really any growth (organic or by acquisition) are sharply reduced when a management has this kind of experience.
The other thing to consider is that this management began with a fair amount of cash and has borrowed money as well. But an experienced management will generally move pretty fast in the beginning to get the company where it needs to be. Therefore, negative cash flow from all the expenditures is generally not a worry when there is a new beginning.
Investors can get an idea of the potential of this company from the successes of the past, as shown above. Generally, a management like this would aim to triple the stock price over five years to make up for the risks incurred in the process of building a company. Actual results can vary widely, of course. The past record, shown above, is pretty encouraging in this respect compared to much of the industry.
The strong buy for this elevated risk idea comes really from management experience. It is hard (at this point) to tell where the company will be other than to state that management has been successful in the past and therefore has a good chance to be reasonably successful in the future.
Risks
The industry had a very rough 2015-2020 period when oil prices declined sharply at the beginning of the period. There was a lot of “house cleaning” as evidenced by climbing bankruptcies and really not a lot of profits for anyone in the industry. While such an event seems remote now, commodities do have those periods (fortunately infrequently).
Any upstream company is subject to the volatility and low visibility of future commodity prices. A severe and sustained commodity price downturn could change the outlook of the company materially. Management has so far maintained a very low debt ratio that should keep the worst possibilities at out of consideration. However, the commodities business moves fast. Therefore, conditions can change without a lot of warning. The move into more oil and condensate should mitigate the effects of something like this.
The loss of key personnel could materially delay the company’s plans.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link