Wirestock
Introduction
ageas (OTCPK:AGESF) (OTCPK:AGESY) is the largest insurance company in Belgium. It was created during the Global Financial Crisis when Fortis Bank was dismantled and sold to French banking conglomerate BNP Paribas. BNP Paribas recently acquired the stake of Fosun in ageas and is now the insurance company’s largest shareholder with a 9.8% stake and this could perhaps be the prelude of trying to acquire ageas as a whole. As part of carving up the business in the Global Financial Crisis, BNP Paribas already owns 25% of AG Insurance, the operating company, with ageas owning the remaining 75%. By acquiring the 9.8% of ageas, BNP Paribas is further increasing its direct and indirect stake in the business.
Yahoo Finance
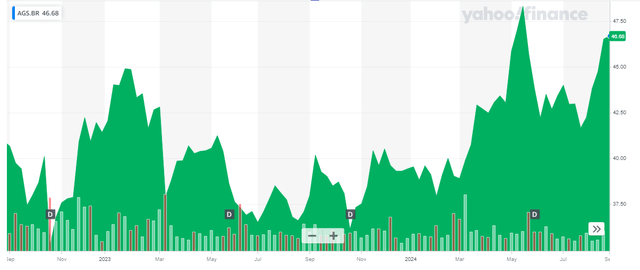
ageas has its primary listing on Euronext Brussels where the stock is trading with AGS as its ticker symbol. The average daily volume in Brussels exceeds 250,000 shares per day, making it the most liquid listing and best trading venue to trade in the company’s stock. I will refer to the Belgian listing and will use the Euro as base currency in this article.
The net results in the first half of the year were excellent
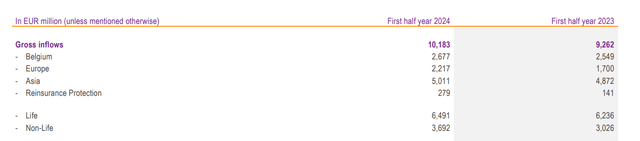
In the first half of the year, the Belgian insurance company achieved an inflow of 10.2B EUR in premiums, which is the very first time it breaches the 10B EUR mark (the full-year result was 17.1B EUR in 2023).
ageas Investor Relations
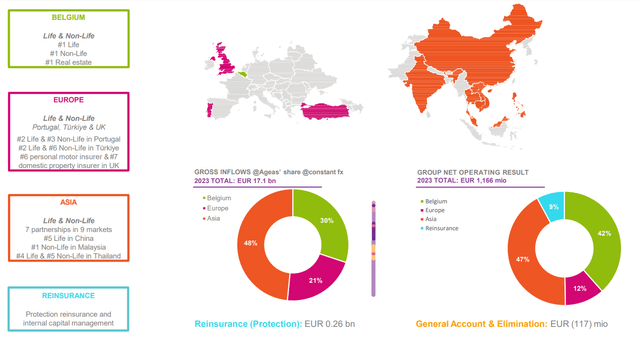
The main contributor to this rather strong increase is the non-life division. And as you can see below, although this is a Belgian company, it very much is a call option on growth in Asia as the Asian market represents almost 60% of the gross inflows. The exposure to Asia also is one of the main reasons why I do like ageas better than most other European insurance companies in the same market cap segment around the 10B EUR mark.
ageas Investor Relations
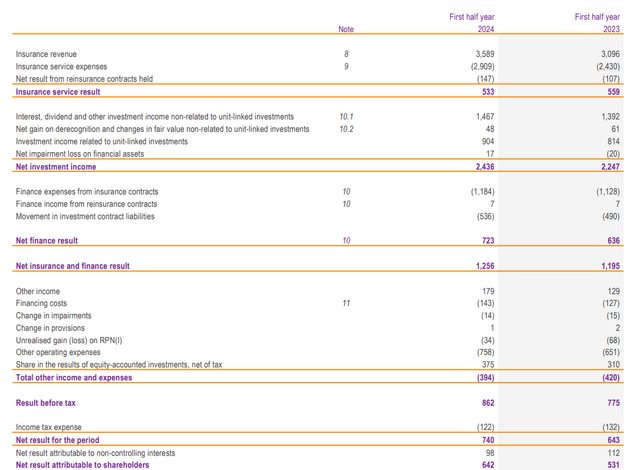
The gross inflows result in a net insurance revenue of almost 3.6B EUR (as shown below) while the insurance-related expenses came in at 2.9B EUR and there was a negative 147M EUR, resulting in a net insurance result of 533M EUR. Slightly lower than in the first half of last year, mainly due to the reinsurance difference.
ageas Investor Relations
On the other hand, the insurance company definitely benefited from higher interest rates on the financial markets. As you can see above, the net investment income increased by almost 10% while the investment-related expenses increased at a similar pace, resulting in a 87M EUR increase in the net finance result. And that definitely helped to completely wipe out the lower insurance result, resulting in a combined contribution of 1.26B EUR compared to 1.2B EUR in H1 2023.
The total amount of other net expenses decreased slightly as well, and this boosted the pre-tax result to 862M EUR, resulting in a net profit of 740M EUR of which 642M EUR is attributable to the shareholders of ageas. Divided over the current share count of just over 183M shares, this represented an EPS of 3.50 EUR.
While the second half of the year may be slightly more difficult than the first half, I do think ageas may see its full-year EPS exceed 6.50 EUR per share, and I’m currently aiming for 6.75 EUR per share. That would be a rather substantial increase from the 5.19 EUR per share in FY 2023 and that increase will mainly be caused by the improved performance on the “float” as the net investment result should continue to increase.
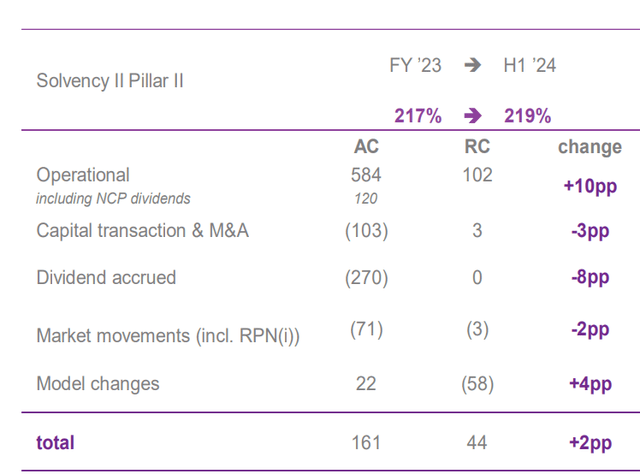
Another important element for an insurance company is the solvency ratio, and ageas also scores pretty good on that. As shown below, the solvency ratio increased to a very healthy 219% mainly thanks to the solid operational performance.
ageas Investor Relations
This further emphasizes ageas is a well-run insurance company with a healthy balance sheet and solid exposure to Asia.
Expect dividend increases as well as share buybacks
Shareholders will definitely see a positive impact with the strong results. ageas has announced a stable interim dividend of 1.50 EUR per share and that was widely expected as the insurance company will likely increase its final dividend once it has the full-year results in hand. The FY 2023 dividend was 3.25 EUR per share which represented an 8% YoY increase as ageas has initiated a “progressive dividend” policy as part of its Impact24 program. I don’t think we’ll see another 8% increase as some of the cash will be used to fund a share repurchase program, but I think a 3%-5% dividend increase to 3.35-3.40 EUR per share is realistic. Based on the current share price of almost 46.7 EUR this would represent a 7.2% dividend yield (subject to the standard 30% dividend withholding tax in Belgium, which can be reduced due to existing double taxation treaties).
And due to the strong results, ageas is now in a position to also start a 200M EUR share buyback program. At the current share price, this should be sufficient to buy back approximately 4M shares, reducing the share count by 2-2.5%. That will provide a further boost to earnings and will open the door to future dividend hikes.
Investment thesis
ageas is one of the largest positions in my portfolio, as I like the company’s focus on Asia in combination with running a robust balance sheet and generous dividend policy. The stock is currently trading at a premium of approximately 15% to the book value, but that’s not a major issue. Due to the company’s ability to retain earnings while decreasing interest rates on the financial markets will increase the fair value of its investment portfolio, I expect ageas’ book value to increase to the mid-40 EUR range by the end of next year.
I have a long position and I continue to write put options that are slightly out of the money, collecting the option premiums. I’m planning to remain overweight in ageas in my portfolio.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link