We Are/DigitalVision via Getty Images
Investment Thesis
SoundHound AI, Inc. (NASDAQ:SOUN) strives to make voice interactions and voice-operated decisions seem seamless and more human-like.
While the company is undoubtedly in growth mode and came out early in the year with strong growth guidance for 2025, I look beyond its narrative and revenue line and see a significantly unprofitable business.
And yet, I’m less bearish on SOUN than I’ve been for a while, and so I upward revise my rating to neutral.
Rapid Recap
Back in April, I said,
I maintain that this stock is not the best way to invest in the hottest area of the market, AI.
In fact, I know from experience that backing the hottest area of the market leads to significant capital losses more often than not.
I recommend that investors avoid this stock.
Author’s work on SOUN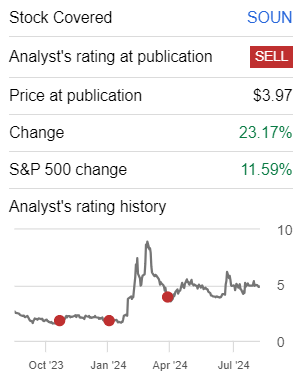
SOUN has been a very volatile stock. And investing in this stock has not been for the faint-hearted. And yet, I am no longer as bearish on SOUN as I previously was.
SoundHound AI’s Near-Term Prospects
SoundHound AI specializes in developing voice and conversational AI technology. They create platforms and solutions that allow people to interact with devices and systems through natural, spoken language. Their technology is used in various applications, including in-car assistants, customer service solutions, and voice-enabled commerce.
Next, SoundHound AI is experiencing significant growth, with Q2 2024 delivering a 54% increase in revenue and a doubling of subscriptions and bookings y/y.
Their technology, particularly in the automotive and customer service sectors, is gaining traction, leading to increased adoption and higher revenue per unit. With the recent acquisition of Amelia, a leader in conversational AI, SoundHound AI expects to further expand its market presence across various industries.
Incidentally, the acquisition is projected to support substantial consolidated revenue growth in 2025.
Nonetheless, SoundHound AI faces challenges. The integration of Amelia, while strategic, may initially slow down profitability due to the costs of merging the two companies.
Furthermore, SoundHound states that its Amelia acquisition will not be accretive to earnings until the second half of 2025, meaning that until then, SoundHound will most likely continue operating at a loss, with significant investments required to maintain its growth trajectory.
Given this background, let’s now discuss its fundamentals.
SoundHound’s 2025 Is Expected to be Very Strong
SOUN revenue growth rates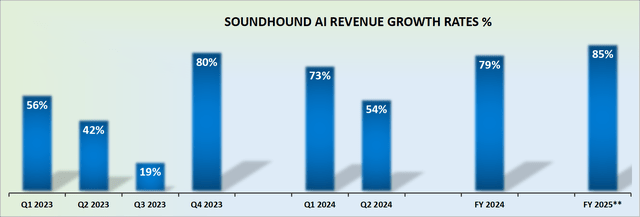
Growth companies must grow. Accordingly, in an attempt to get investors on board with its growth prospects, SoundHound AI has been early to guide its revenues for more than 85% y/y growth in 2025.
Getting to $150 million in revenues, after SoundHound AI previously guided that 2025 would see $100 million of revenues, is undoubtedly a strong show of confidence that Amelia and SoundHound AI will be stronger together.
In fact, the issues that keep me cautious of SoundHound AI have little to do with its lack of growth. On the contrary, SoundHound is growing at scale, without much in the way of hiccups.
The issue I have, is that growth for the sake of growth, without having to focus on profitability, is something that investors typically pay small multiples for. But that’s not the case with SoundHound AI, Inc.
SOUN Stock Valuation — +10x Next Year’s Sales
As an inflection investor, you must always think about the company’s financial footing, as that dictates its ability to get a strong multiple on its stock. Why?
Because a company with a strong balance sheet has ample flexibility to reinvest in its growth operations if the business hits a hard time.
On this front, the debt-free SoundHound scores highly. After all, more than 10% of its market cap is made up of cash.
And yet, the biggest concern I have, is that the bulk of its capital has come from diluting shareholders.
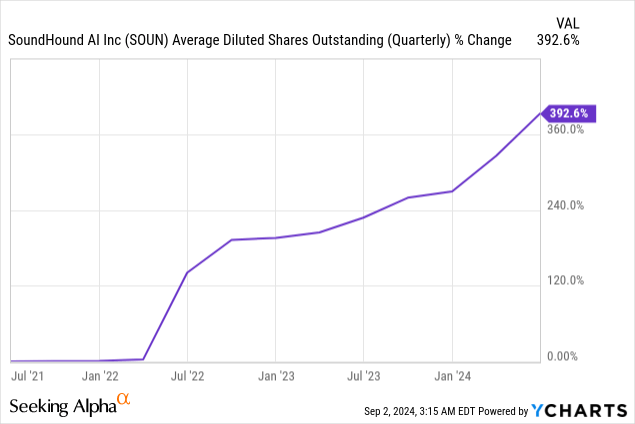
As you can see above, in the past 3 years, SoundHound’s share count is up nearly 4x. That’s a very high dilution level, which means that investors are not exactly participating in the company’s increase in intrinsic value.
And then, what complicates matters further, is that even if SoundHound improves its free cash flow burn, I still estimate that SoundHound will burn through about $60 million of free cash flow in the coming twelve months.
Indeed, for SoundHound to deliver about $130 million in revenues, it must incur about $60 million of free cash flow losses. In more simple terms, to deliver $1 of revenue, SoundHound must burn about 40 cents of free cash flow.
Consequently, this makes SOUN a very tough call to make at this point. That is even though there are positive aspects that could see this company become a more established and profitable business in the long term.
After all, investors are already paying 10x next year’s sales for SoundHound AI. That’s commensurate with some of the biggest, brightest, and best SaaS businesses, including businesses that some investors believe to be richly priced such as Palantir (PLTR) and CrowdStrike (CRWD).

The graphic above is only looking out to the end of this year. So, when I say 10x next year’s sales, I’m referring to 2025 sales. Though, my point remains, that investors’ expectations are incredibly high, and that compared with the highly profitable CrowdStrike and Palantir, SoundHound AI is even pricier.
In sum, I’m struggling to believe that this stock is undervalued.
The Bottom Line
Reflecting on SoundHound AI’s journey, I find myself in a nuanced position. While the company’s growth and innovation, particularly with the Amelia acquisition, signal strong potential, the persistent challenges around profitability and shareholder dilution cannot be ignored.
My optimism for the company has grown slightly, but not enough to be outright bullish. The high valuation, at the same time as ongoing cash burn and the significant dilution of shares, makes SoundHound AI a difficult investment decision.
When it comes to SoundHound AI, Inc. stock, I’ll keep my ear to the ground waiting for clearer signals of its potential.
Credit: Source link