
DNY59
We previously covered Novo Nordisk (NVO) (OTCPK:NONOF) stock in April 2024, discussing why we had maintained our Buy rating then, attributed to the multiple expansions in its manufacturing/fill finish capacities, with the ongoing shortages still implying immense consumer demand.
We believed that these capex would eventually be accretive to its top/bottom lines, especially since the Pfizer’s (PFE) CEO, Albert Bourla, had estimated an obesity market size of up $150B.
Since then, NVO has charted new heights before dramatically pulling back as the market rotated from high-growth stocks. Even so, the bulls continue to defend its 2024 bottom with the easing supply issues likely to trigger robust FQ3’24 numbers, as observed in the management’s raised FY2024 guidance.
With the competitors still a few years away from US FDA approval, we believe that NVO along with Eli Lilly and Company (LLY) are still poised to enjoy a two horse race in the obesity/diabetes market.
The GLP-1 Investment Thesis Remains Robust For Opportunistic Investors
NVO YTD Stock Price
TradingView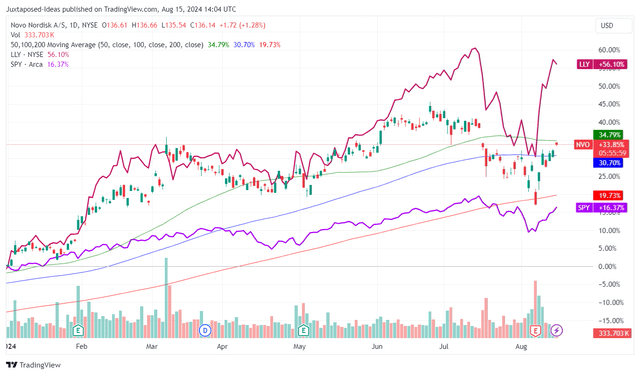
NVO has had a volatile YTD performance indeed, attributed to the market rotation from high-growth stocks since late June 2024 and the subsequent bullish support observed by early August 2024.
This volatility is partly attributed to the previous Semaglutide shortages since the start of the year, with it also contributing to the pharmaceutical company’s slower sales growth for Wegovy (weight loss) at 11.65B DKK in FQ2’24 (+24.3% QoQ/ +55.1% YoY) and Ozempic (diabetes) at 28.87B DKK (+3.8% QoQ/ +30.6% YoY)
This is compared to the therapies’ historical growth recorded in FQ2’23 at +543% YoY and +59% YoY, respectively.
When compared to NVO’s direct competitor, LLY’s recent performance with Mounjaro (diabetes) recording robust +71.1% QoQ/ +215.5% YoY sales growth and Zepbound (weight loss) at +138.4% QoQ in FQ2’24, we can understand why the market may have been disappointed with the former’s recent performance.
At the same time, LLY has had greater success in International growth for Mounjaro sales, with it growing by +136.6% QoQ/ +1,058.1% YoY, compared to NVO’s Ozempic at +10.4% QoQ/ +9.5% YoY in the same Q2’24 quarter.
Aside from the supply issues, perhaps part of the headwinds may also be attributed to “patients receiving tirzepatide (Mounjaro) were significantly more likely to achieve weight loss,” compared to semaglutide (Ozempic), with “on-treatment changes in weight were larger for patients receiving tirzepatide at 3 months.”
On the other hand, readers must note that NVO’s next-gen candidate, CagriSema, already offers a -15.6% of weight loss by Week 32, well exceeding Wegovy at -7% at Week 13/ -15.2% at Week 68 and LLY’s Mounjaro at -15.7% at Week 72, by the inherent virtue of speed.
With CagriSema’s first Phase 3 results for REDEFINE 1 expected in H2’24, we believe that we may see NVO emerge stronger ahead, significantly aided by the ongoing capacity expansion of its API facilities and fill-finish networks, some of which are already “up and running.”
At the same time, readers must note that these headwinds are attributed to the previous supply issues, with NVO’s FQ3’24 potentially bringing forth a robust sequential growth, since Ozempic/ Wegovy are no longer in shortage.
Most importantly, the management has already raised their FY2024 net sales growth guidance to +25% YoY and operating profit growth at +25% YoY at the midpoint, up from the original guidance of +22% YoY and +25% YoY offered in the FQ4’23 earnings call, respectively, lending strength to its high-growth investment thesis.
Lastly, NVO has highlighted exemplary market share gains in North America for Ozempic at 56% in FQ2’24 (in line QoQ/ +1 points YoY) and globally at 46.6% (-0.6 points QoQ/ +1.6 YoY), along with the increase in its global diabetes value market share to 34.1% (+0.1 points QoQ/ +1.4 YoY).
While LLY has raised their FY2024 revenue guidance to +34.8% YoY growth, up from the original number of +20.1% YoY, along with the ongoing ramp up of its global presence with the aim to enter more markets in 2025, we believe that NVO remains well positioned to compete moving forward.
The Consensus Forward Estimates (in $)
TIKR Terminal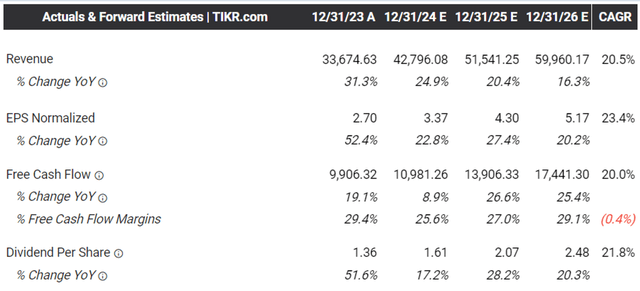
The same optimism has also been observed in the consensus raised forward estimates, with NVO expected to generate an accelerated top/ bottom-line growth at a CAGR of +20.5%/ +23.4% through FY2026, respectively.
This is compared to the previous estimates of +11.1%/ +11.5% and its historical growth of +8%/ +8.5% between FY2016 and FY2022, respectively.
NVO Valuations
TIKR Terminal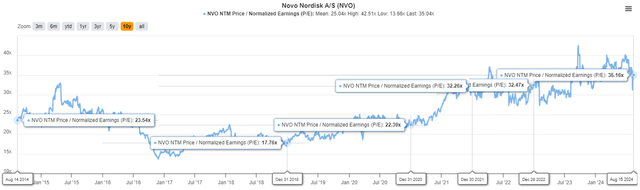
The recent market wide pullback has also moderated NVO’s FWD P/E valuations to 35.16x, down from the recent peak of 40.17x in June 2024 and nearer to its 1Y mean of 36.09x.
Even when compared to its direct obesity/ diabetes therapy pharmaceutical peer, LLY at FWD P/E valuations of 58.71x with the projected adj EPS growth at a CAGR of +65.4% through FY2026, it is undeniable that NVO is the value buy at current levels.
So, Is NVO Stock A Buy, Sell, or Hold?
NVO 5Y Stock Price
TIKR Terminal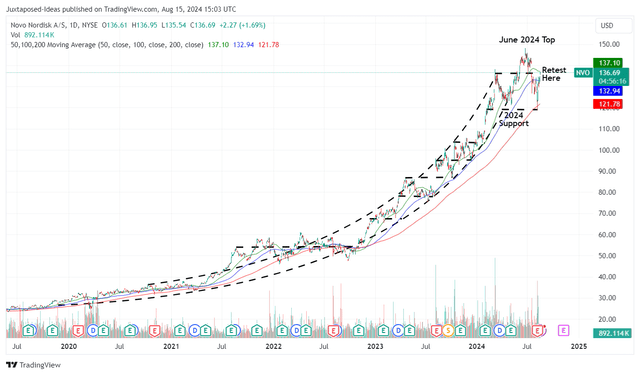
For now, NVO has traded sideways since the start of 2024, with it currently trading near to its 100-day moving averages after the drastic correction from the June 2024 top and the subsequent bounce from the bullish support at $120s.
For context, we had offered a fair value estimate of $98.90 in our last article, based on the FY2023 adj EPS of $2.70 and the previous FWD P/E valuations of 36.63x. This is on top of the long-term price target of $186.00, based on the consensus FY2026 adj EPS estimates of $5.08.
Based on NVO’s raised FY2024 adj EPS guidance to approximately $3.37 (+25% YoY) and the same P/E valuations of 36.63x (near to its 1Y mean of 36.09x), we are looking at an updated fair value estimate of $123.40, implying a minimal premium of +9.3% at current levels.
Based on the consensus raised FY2026 adj EPS estimates of $5.17, there remains an excellent upside potential of +40.3% to our updated long-term price target of $189.30 as well, thanks to the recent pullback from the June 2024 peak of $146.90.
While minimal, the 1.07% in forward dividend yields allow long-term shareholders to DRIP and accumulate additional shares on a quarterly basis as well.
As a result of still attractive total return prospects through capital appreciation and dividend income, we are reiterating our Buy rating for the NVO stock here.
Risk Warning
Readers must note that NVO’s prospects are tightly linked to its GLP-1, Insulin, and Obesity therapies, which comprise 93.7% of its H1’24 sales (+1.8 points YoY).
With its rare disease segment underperforming expectations with declining sales at -3.7% YoY in H1’24, it goes without saying that any market share losses in its growth segments may potentially impact its future top/ bottom-line growth.
This is especially since NVO has underperformed against its direct peer in H1’24, with it remaining to be seen if the improved Ozempic/ Wegovy supply may boost its H2’24 performance.
As a result, investors may want to monitor its near-term performance, particularly in China, since Wegovy has been recently approved in China albeit with accelerated patent expiry in less than two years, compared to 2031 in the EU/ Japan and 2032 in the US.
Credit: Source link