
Funtay
Thesis Recap
I covered GeoPark Limited (NYSE:GPRK) in April 2024, with the overall thesis that the company sports high margins and strong growth potential. I like this Latin American oil producer for its cheap valuation and nice dividend as well, highlighting it as a potential income play for investors. Since then, I remain bullish and view the recent sell-off in the stock as another buying opportunity. The company has made many value-adding acquisitions since my last report, and I view management as incredibly capable in allocating capital to create value for shareholders. Thus, I remain bullish and rate shares as a buy.
Savvy Acquisitions
Since my last report, GeoPark has made a few savvy acquisitions that seem poised to increase shareholder value. For instance, GeoPark announced that they were buying “a non-operated Working Interest in unconventional blocks in the Neuquen Basin in Argentina” for $200 million. Since the announcement, the offer has already been accepted, confirming that this deal is likely going to go through.
My opinion is that this deal is incredibly favorable for shareholders as it diversifies GeoPark’s operations, increases production capacity, and does not strain the balance sheet excessively. According to the press release, “Upon closing, the assets would immediately contribute more than 5,000 net boepd of production. The agreed acquisition price is around $200 million, plus an additional carry of $110 – 120 million (gross), over a two-year period, associated with certain exploration activities”.
It is hard to assess the true value of the deal as GeoPark comments, “Due to confidentiality terms under the agreement, GeoPark is not able to provide further information to the market on this acquisition until the final documentation is signed, or terminated, as the case may be”. Nonetheless, given the historical track record of management in making savvy deals for shareholders, I believe this deal to be a major positive and will give management the benefit of the doubt.
Furthermore, the company announced that they “signed an Asset Purchase Agreement with Phoenix Global Resources, a subsidiary of Mercuria Energy Trading, for the acquisition of non-operated working interest in four adjacent unconventional blocks in the Neuquén Basin in Argentina”.
I think this deal is also favorable for shareholders, and the market is significantly underestimating the growth GeoPark can achieve going forward. These assets have an immediate impact on the bottom line by increasing production capacity as well as future potential for an increase in productive reserves. Furthermore, it diversifies GeoPark operations into Argentina and increases the overall reserve life of GeoPark’s reserves.
What these acquisitions mean financially for investors is that cash flow capability should increase significantly over time, leading to more share repurchases and dividends to increase shareholder value. The balance sheet is still pretty strong, with interest payments still being well-covered by cash flow. I see the overall rewards outweighing the risks here and think management has credibility in making value-adding acquisitions. Therefore, investors should view the recent deals as a positive and remain bullish on the stock.
Oil Prices Are Still Attractive
Another reason I’m still bullish on GeoPark is that oil prices still remain very attractive for shareholders. According to the EIA,
Although crude oil prices have fallen recently, we continue to expect crude oil prices will rise in the second half of 2024. The Brent crude oil spot price ended July at $81 per barrel, compared with an average for the month of $85/b. We expect the Brent price will return to between $85/b and $90/b by the end of the year.
EIA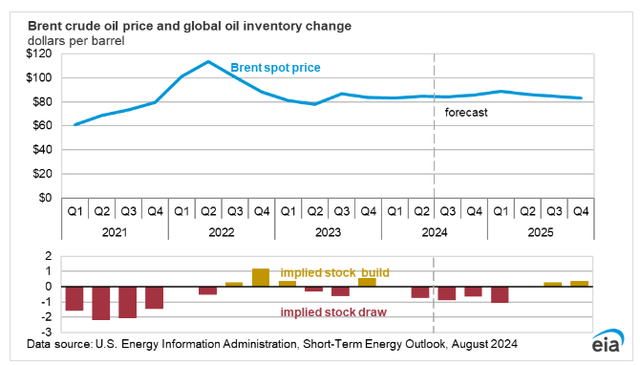
I think that oil prices should remain high due to OPEC’s supply cuts and sustainable consumption forecasts made by the EIA. The overall supply-side seems to be facing pressure recently, as the EIA report points to OPEC cuts and wildfires in Alberta’s oil production centers that may pressure supply. On the demand side, consumption from China remains relatively strong, with “consumption of petroleum and liquid fuels consumption will grow in China by about 0.3 million b/d in 2024 and in 2025”.
In other words, the cash flows should remain very strong as long as oil prices hold up. My analysis of the oil market shows that oil should hold up at prices above $60 a barrel due to favorable supply-demand dynamics. I project cash flows from operations to remain at least $300 million going forward, which should be enough to pay for the increasing capex and acquisitions GeoPark is making.
Improving Production Levels
GeoPark also released their Q2 operational update with the following results,
- Production increased 11% in Ecuador and 3% in Colombia, offsetting suspended production at the Manati gas field in Brazil (GeoPark non-operated, 10% WI) due to unscheduled maintenance
- As of July 1, 2024, GeoPark is producing over 41,000 boepd, adding approximately 5,700 boepd on a proforma basis from the Mata Mora Norte Block (GeoPark non-operated, 45% WI) in Argentina
- 2Q2024 consolidated average oil and gas production of 35,608 boepd, up slightly versus 1Q2024
In particular, the CPO-5 Block is hitting “record high quarterly production” according to the press release. With attractively high oil prices, it makes sense that GeoPark wants to ramp up production to take advantage of the profits they can earn for shareholders. I think the future earnings will trend more positive, posing a potential catalyst for the stock price to move up.
Investors can see that the growth prospects went from strong to stronger and I feel that GeoPark has the reserves, exploration expertise, and production capacity to improve cash flows. Further improvements in barrels of production would confirm the bullish story for GeoPark in my view.
What To Expect In Q2 Earnings
GeoPark plans to announce Q2 2024 earnings on August 14, 2024, after the market close. Investors should look for the following:
- Improvements in EBITDA and operating cash flow YoY
- Ramp up in capital expenditures, and watch if they remain below operating cash flow to avoid excessive leverage
- Capital efficiency metrics, see how every $1 of capex translates into adjusted EBITDA
- Manageable debt levels in relation to EBITDA and shareholder equity
I expect Q2 earnings to be in-line with estimates, but the stock is marvelously cheap in my view. It’d be a good idea to buy before earnings, as earnings surprises can cause a rally in the shares. If earnings miss, I doubt the stock could go any lower, so the risk/reward looks favorable for the stock heading into earnings.
Dividends and buybacks continue to reward shareholders for waiting, as the quarterly dividend was $0.147 per share at the time of writing, which is a yield of ~7%. Management has signaled potential undervaluation through strategic buybacks of “4.4 million shares at $10 per share that were launched in the first quarter and ended in April 2024, reducing shares outstanding by approximately 8%”. The capital allocation is very strong and continues to provide reasons for investors to remain bullish in my view.
In terms of valuation, I leave my price target of $15 unchanged from my last report. At 3x FWD earnings, the stock still remains undervalued compared to the sector median of 11x FWD earnings. I think further share repurchases are advantageous and serve as an inevitable catalyst for a rally, as the dividend yield may increase as shares outstanding decrease.
Risks
Recent news shows a potential sell-off in markets such as Japan, as well as recession fears in the US. If the overall markets plummet, then all stocks may go down, including GeoPark. Furthermore, if we see a strengthening in currencies such as the Colombian Peso, it could trigger a sell-off in Colombian stocks such as GeoPark. Adverse currency fluctuations as well as market fears can cause shares of GPRK to decline in the near-term.
GeoPark’s rapid acquisition spree may trigger some new political controversy similar to before, where they were accused of unfairly taking over indigenous lands. A few years ago, GeoPark faced “fierce opposition from the Achuar People of the Pastaza and the Wampis Nation of the northern Peruvian Amazon” and had to leave those lands from oil production. Now that we’re seeing GeoPark going on a shopping spree for land-producing oil, some may be worried history may repeat itself as indigenous peoples and environmental activists oppose the increase in production of fossil fuels by GeoPark.
Buy GeoPark
The story just keeps getting better in my view. I think the stock has reached another buying point below $10 per share and the earnings should eventually be recognized by the market as being sustainable and growing due to high oil prices. Aggressive acquisitions show that management believes in their cash flow capabilities and are ready to turn GeoPark into a growth story, reinforcing my bullish views. Shares remain a buy with a price target of $15, unchanged.
Credit: Source link