
John Lamb
Arista Networks (NYSE:ANET) is positioned for a strong eFY24 as the network equipment industry takes a turn into bullish territory. With management’s q1’24 beat and raise, customers’ digestion of their equipment inventory builds, and the drive to build out the networking component to cater to the high-speed demands of AI/ML, I believe Arista is in the beginning phase of the next cycle and should realize significant top-line growth and margin expansion.
Arista will be reporting q2’24 earnings results on July 30, 2024. Analysts’ sentiment is very bullish going into this quarter, with 23 EPS revisions to the upside in the last 90 days and zero to the downside. Consensus estimates Arista to generate $1,628-1,744mm in q2’24 with a midpoint of $1,651mm. I anticipate Arista to report near the consensus estimate of $1.65b in total revenue and an adjusted EPS of $1.68/share for q2’24 and reach $6.65b in revenue for eFY24, just shy of the consensus estimate of $6.72b.
Given the optimistic outlook for the networking equipment industry, I am re-rating ANET to a BUY rating with a price target of $388/share at 14.81x eFY25 EV/EBITDA.
FinChat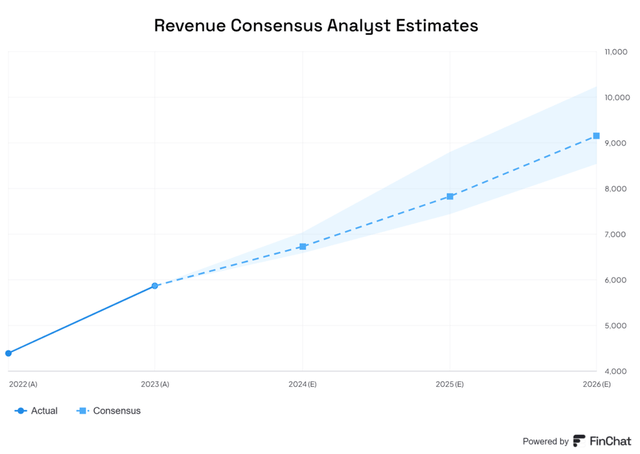
Be sure to review my previous report covering Arista Networks here:
Arista Networks Has A Strong Growth Runway But Is Priced Right
Arista Networks Operations
Chuck Robbins, Chair and CEO of Cisco (CSCO) cited some promising news about the networking industry in their q3’24 earnings call on May 15, 2024, making me believe that networking equipment sales should take a turn into high growth territory in the coming quarters.
Based on activations to the cloud, which we track as well as conversations with our customers and partners, we believe that the products customers have on hand are being steadily deployed in line with the expectations we laid out last quarter, meaning we currently expect customers to complete the installation of the majority of their inventory by the end of our fiscal year in July.
Chuck Robbins
This optimistic outlook may help reignite Arista’s growth rate in the coming quarters, well beyond their exceptional growth in q1’24. This will likely be driven by demand by the hyperscalers and a growing demand by enterprises. Aside from the higher expected top-line growth rate, management anticipates some additional new product launches throughout the fiscal year that may keep margins at a relatively level rate as the firm continues to deepen their role in connecting the back-end GPUs to the front-end endpoints.
On June 5, 2024, Arista launched their 800G Etherlink AI Networking Platforms, which are designed to deliver optimal network performance for most AI workloads, whether training or inferencing.
Arista Networks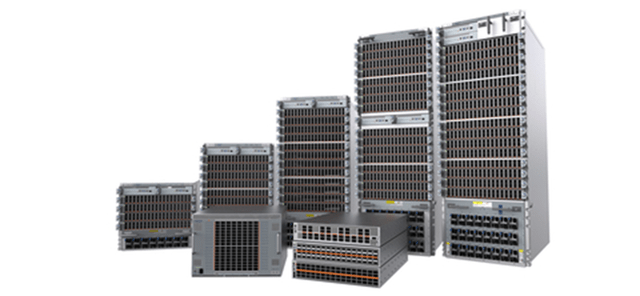
This platform will be powered by the Arista EOS to support AI clusters, ranging from thousands to hundreds of thousands of XPUs on a 2-tier network topology. Arista will be implementing Broadcom’s Tomahawk 5 silicon on the AI Leafe switch and the Broadcom Jericho3-AI processors on the AI Spine. This scalable stack will likely be pushed through to the hyperscalers and tier-2 data centers to interconnect their AI factories for optimized performance.
In addition to this, Arista is collaborating with Nvidia (NVDA) to optimize data center performance with their EOS-based remote AI agent. The agent will be hosted directly on an Nvidia BlueField-3 SuperNIC or on the server to allow EOS to configure, monitor, and debug network problems on the server. The use of the EOS agent will allow for a single point of control and visibility across the AI factory and is expected to improve job time. Customer trials are expected to begin in 2h24.
As for cybersecurity, Arista launched their MSS offering, which will allow for enterprises to create microperimeter segmentation across the existing network environment, whether in the data center or at the campus. The Arista MSS is network-agnostic and endpoint-independent, allowing for the product to integrate across multiple environments. This product can also integrate with firewalls and cloud proxies like Palo Alto Networks and Zscaler for stateful network enforcement, ensuring the right traffic is sent through. All of this can be controlled with CloudVision for Microperimeter Management, which will allow for real-time visibility into packets, flows, and endpoint identity. According to the press release, Arista MSS is currently in trials and will be available in q3’24.
Financial Forecast
Management provided strong guidance for q2’24 in their q1’24 earnings call. This included improved eFY24 guidance of 12-14% revenue growth, up from the original forecast of 10-12%. This should land revenue at $6.65b for eFY24 and an adjusted EBITDA margin of 51%. I believe this level of growth will positively impact gross margins across their two reporting segments, growing from the upper 50%’s in FY23 to low 60%’s for the duration of eFY24.
Corporate Reports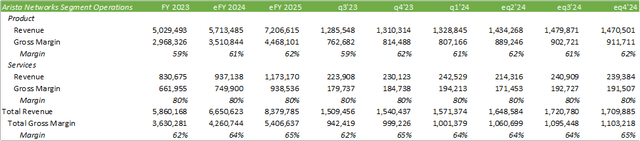
Given the verbiage from management at Cisco, I believe Arista will benefit from the inventory destocking at customer sites, allowing for the firm to accelerate the sales process. I also anticipate that the firm will realize stronger margins as a result of economies of scale as more volume sales flow through.
Corporate Reports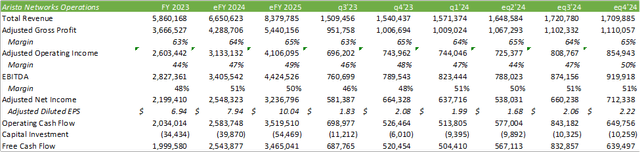
As for cash flow, I believe the firm can generate just north of $2.5b in free cash flow for eFY24, driven by operational growth. I believe there may be some attribution to balance sheet management as well, as the firm grew their inventory levels from 318 days at the end of FY23 to 328 days in q1’24. As a result of timing, the firm also drew down their days payables from 71 days to 36 days for the same period. These two factors may help enhance Arista’s free cash flow generation for eFY24.
Corporate Reports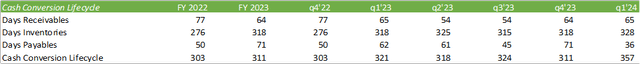
Valuation & Shareholder Value
Corporate Reports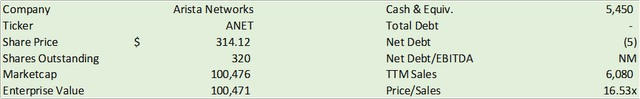
Arista Networks currently trades at 16.53x TTM price/sales, in line with its premium AI-related peers.
Seeking Alpha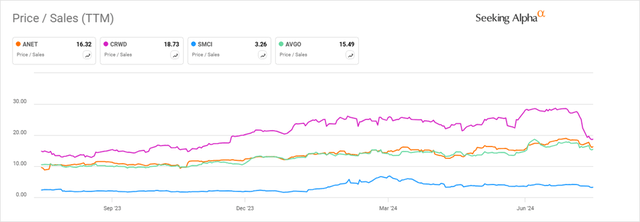
I believe ANET shares will be able to maintain their 15-16x price/sales premium throughout the cycle as the firm realizes significant top-line growth paired with stronger cash generation.
Despite this optimism, I do believe it would be prudent to weigh in the lower end of their trading multiple of 8x as an anchor, especially as the macroeconomic environment appears to be dimming. Based on my eFY25 sales forecast, 8x would price ANET shares at a -33% decline based on the closing price on July 26, 2024. Though this range is possible, I do not heavily weigh it in my valuation model as the firm tends to trade at the higher end of their multiple range. Based on my growth forecast, I believe ANET shares should be priced at $388/share at 14.81x eFY25 sales. Given this optimism, I am rerating ANET shares from a HOLD to a BUY rating.
Corporate Reports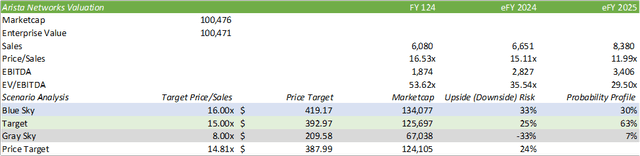
Before you buy into a position, I believe following the technical patterns may help an investor average into a position more optimally. From a tactical perspective, ANET shares appear to be trending down in the near-term through a retracement cycle. I believe shares will potentially drop somewhere in the range of $290-300/share before returning to growth as it pertains to my price target. This route will send shares down another 6-9% before retracing upwards, providing a better buying opportunity for those willing to be patient before entering into a trade. Given how close we are to Arista’s q2’24 earnings release, it might be wise to ease into a position as earnings can send shares in either direction, depending on management’s updated guidance. Given the challenging macro environment, the risk of slower-than-expected growth can potentially occur, especially from enterprise customers.
For a long-term strategy, I believe ANET is at the beginning of one of the most important cyclical upswings as the firm’s products will be entrenched in the AI environment, ensuring the most optimal connectivity from the GPUs, storage, and interfaces. I believe any headwinds will be short-lived and will resolve as AI factories are erected globally.
TrendSpider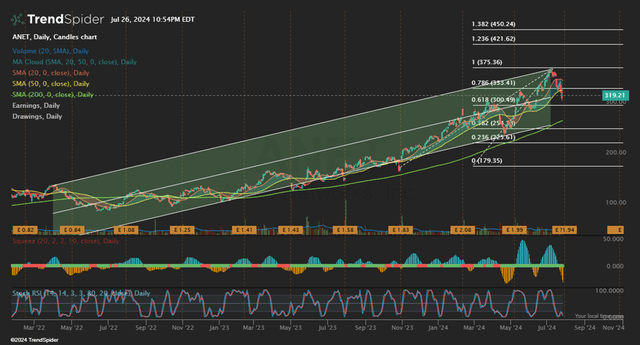
One last point I’d like to make is the viability of the AI trend. I realize that there is a lot of noise in the market, suggesting that the AI craze is a bubble waiting to burst. To counter this argument, firms outside of the tech industry are being brought into the roundtable as AI is moving beyond GPUs and into infrastructure and power sourcing. Companies like Quanta Services (PWR), Nucor (NUE), Chesapeake (CHK), and ONEOK (OKE) are in discussions with hyperscalers for providing electrical equipment, server racks, baseload capacity, and transport services to the planned AI factories. The point I’m drawing across is that AI isn’t a shallow hype-cycle as experienced in the DOTCOM bubble. Projects are being coordinated, planned out, and executed to provide actual automation and business optimization opportunities across all industries. In closing, this goes well beyond a copilot or basic ChatGPT prompts.
Credit: Source link