Shutter2U
Investment Overview
In the first of my two most recent pieces of coverage for Seeking Alpha on AstraZeneca PLC (NASDAQ:AZN), the Anglo / Swedish Pharma giant, I gave the company and its stock a “buy” recommendation in February. This was after a sell-off in response to a Q4 2023 earnings miss created a buying opportunity. Then, in late May, I gave it a “hold” recommendation, shortly after the company had revealed ambitious plans to exceed $80bn in top-line revenues by 2030.
AstraZeneca stock is +26% since my first note, and +2% since my second, corresponding with my calls. However, with the company due to announce its Q2 2024 earnings post-market next Thursday, 25th July, I am revising my stance from “Hold,” to “Buy,” as I will explain during this earnings preview.
AstraZeneca — Fundamentals Ahead Of Q2 Earnings
As we can see from the table below, AstraZeneca is the world’s eighth-largest pharmaceutical company by market cap valuation — currently ~$189bn (price used is for the ADR shares — the ADR ratio is 1:2, meaning each ordinary share is represented by 2 ADRs).
AstraZeneca fundamental metrics (data collected from TradingView, Google Finance)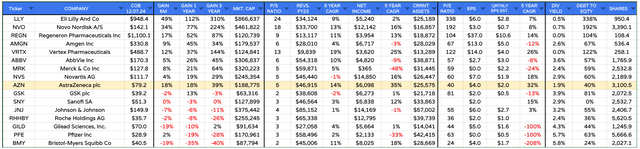
In terms of 3-year share price gains, AstraZeneca stock is +39% — the seventh-best performer, and the third-best performer on a 6m basis, but only ninth best on a 1-year basis. On a five-year basis, shares are up >95%, so essentially, we have a trend of growth, then plateau, growth, with few major sell-offs or setbacks. In 2016, shares traded ~$25, and growth had been stagnant for a decade or more, but ever since, the trajectory has been “up and to the right.”
Over the past 5 years, only Vertex (VRTX) has grown revenues faster than AstraZeneca, while its rate of earnings per share (“EPS”) growth puts it top of the class. A dividend currently yielding ~2% is lower than average, although those companies whose yield is significantly higher — Bristol-Myers Squibb (BMY) and Pfizer (PFE), for example. They have suffered share price declines of 40% and 28% on a 3-year basis, respectively, i.e., dividend yield is high due to company underperformance.
Between Q4 2023 and Q1 2024, AstraZeneca’s net debt increased in size, to $26.4bn. However, the net debt to adjusted EBITA ratio is ~1.9x, implying it is manageable, and it is rated “A-,” or “stable,” by Fitch, the credit rating agency, which stated on 11th April this year:
AZ’s ratings reflect its solid position in the innovative pharma sector, with accelerating organic growth across most of its selected treatment areas, reflecting successful investment in internal and external R&D capabilities.
As a result, we expect AZ’s pipeline to continue increasing its contribution to revenue over the rating case through 2027, offsetting the decline in treatments that are losing exclusivity during the same period, while maintaining an EBITDA margin above 30%.
Recent Performance — & Analyzing Oncology Ambitions
If AstraZeneca’s Q4 2023 earnings disappointed the market, then Q1 2024 earnings painted a much more positive picture. Top-line revenues grew 19% year-on-year, to $12.7bn, and EPS grew 13% year-on-year, to $2.06. For good measure, management also increased the dividend by 7%, to $0.965 per quarter for the ADR shares.
AstraZeneca Q1 2024 performance (earnings presentation)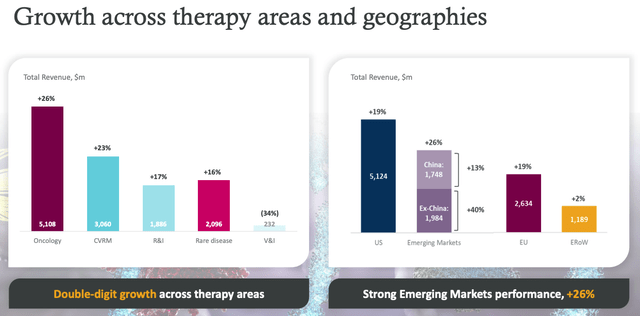
As we can see above, almost every business division showed strong growth, and almost every business territory as well. The exception was Vaccines and Immune Therapies because there are no recorded sales of Vaxzevria, AstraZeneca’s COVID vaccine, during the quarter.
Oncology is AstraZeneca’s biggest strength, generating ~40% of the company’s total revenues, led by the TKI-inhibitor Tagrisso, PD-1 blocker Imfinzi, PARP inhibitor Lynparza, and BTK-inhibitor Calquence, whose revenues in 2023 were $5.8bn, $4.2bn, $2.8bn and $2.5bn respectively.
The division turned over >$5bn in a quarter for the first time in Q1. With only Lynparza facing patent expiry before the end of the decade, more growth should be expected, led by Tagrisso, expected to drive >$7bn per annum in peak revenues, in lung cancer markets.
Not only that — I mentioned that AstraZeneca plans to deliver >$80bn in top-line revenues by 2030, and this is expected to be achieved with the launch of 20 new medicines by 2030, “many with the potential to generate more than $5 billion in peak year revenues,” according to CEO Pascal Soriot. Six of these products have now been launched.
In my last post, I shared a table of revenue forecasts for the oncology division, including the pipeline assets that AstraZeneca expects to deliver the >$5bn peak annual sales. Complementing recently approved Truqap, which has peak revenue expectations of ~$2bn per annum, according to Wall Street, are no fewer than eight new potential therapies, each with different mechanism of action (“MoA”). These range from CD19 targeting blood cancer candidates, to a selective estrogen receptor degrader (“SERD”), to a TIGIT inhibitor, and an antibody drug conjugate (“ADC”).
Five of these therapies — the SERD candidate camisestrant, ADC Dato-DXd, anti-TIGIT rilvegostomig, PARP-inhibitor saruparib, and PD-1/CTLA4 blocker vulrostomig — are all in Phase 3 clinical studies, which means, pending positive data readouts, they may secure commercial approval within a couple of years.
As such, when management presents its Q2 earnings in a week’s time, the focus will not just be on the numbers — Wall Street expects revenue to be ~$12.55bn, with normalized EPS of $1.01, and, and GAAP EPS of $0.76. Attention will also be on the pipeline progress, too.
In March this year, AstraZeneca announced the acquisition of Fusion Pharmaceuticals, a developer of radiopharmaceutical drugs, in a $2.4bn deal, signalling its ambition to compete in yet another field of oncology, considered one of the hottest new fields of research.
With so much expenditure and R&D spending — which increased by 18% year-on-year in Q1, to $2.7bn, comes pressure to deliver the promised revenue growth and margin reductions. So, in a way, as I argued in my last note, AstraZeneca is making an unnecessary rod for its back by sharing its ambitious growth plans.
Equally, the company is signalling its intent to become the most globally dominant oncology company in breast and lung cancer markets — the two largest markets — and if progress is maintained, this will inevitably lead to a rising share price. AstraZeneca has arguably the largest and most diverse late-stage oncology pipeline in global Pharma, and as this pipeline becomes commercialized, we will learn more and more about whether management’s ambitious targets are achievable.
Other Areas Of Focus — Onus On New Launches In Rare Disease, Biopharmaceuticals, To Deliver
Besides the eight new oncology drug launches promised (we may wish to discount this figure by two or three as there may well be study failures and drugs that do not make it to market), in my last note I counted four potential new drug launches within the biopharmaceuticals division, and five within the rare disease division.
AstraZeneca’s foray into rare disease was triggered by its acquisition of Alexion for ~$13bn back in 2021. Its key assets are the C5 inhibitor Soliris, and its long-acting, intended long-term replacement ultomiris. Ultomiris generated almost as much revenue for the company in 2023 — $2.97bn — than Soliris’ $3.15bn, and in Q1, outsold soliris, generating $860m of revenues, to Soliris’ $739m.
That is a good sign for AstraZeneca — soliris patents are expected to expire around 2025. However, there is also competition in the form of Swiss Pharma giant’s crovalimab, a self-injectable formulation that has already been approved in China to treat paroxysmal nocturnal haemoglobinuria (“PNH”), the same indication as soliris / ultomiris.
The advantage of a self-injectable over a therapy that must be injected by a physician either bi-weekly (soliris), or once every eight weeks (ultomiris) is clear. Crovalimab is pending approval in the US and Europe, and pegged by analysts for >$3.5bn in peak annual sales. It ought to be interesting to see if management has updates on the potential impact of this in Q2.
Within Biopharmaceuticals, another concern relates to Farxiga, a >$5bn per annum selling diabetes / heart failure drug, which loses patent protection around 2025. Even if patent protection was not an issue, the rise of the GLP-1 agonist drugs, like Eli Lilly (LLY) and Novo Nordisk’s (NVO) “miracle” weight loss drugs Zepbound and Wegovy, may soon begin to impact the cardiovascular space. This would take market share away from older drugs such as Farxiga.
Attempting to turn a potential weakness into a strength, however. AstraZeneca does have its oral small molecule GLP-1 candidate in the clinic. It says it will move into Phase 2b studies in obesity and diabetes this year, which is encouraging news, and updates will doubtless be provided on the earnings call. The company has played its cards close to its chest to date, but news of a successful GLP-1 candidate would add tens of billions to AstraZeneca’s market cap. Wall Street believes GLP-1 agonist drugs will become a $150bn — $200bn industry across many indications.
In the shorter term, the company has three major drug launches planned for different type of cardiovascular and lung disorders, and will doubtless provide updates on progress during the Q2 earnings call as well.
Otherwise, updates on commercial performance of newly launched assets including Airsupra, indicated for asthma, Wainua, indicated for polyneuropathy, cancer drugs Imjudo and Truqap, and RSV antibody Beyfortus, will be worth paying attention to. These drugs are key to the future performance of the company, with older drugs such as COPD therapy Symbicort and Fasenra losing patent protection, and likely to experience falling sales.
Looking Ahead — A “Fair Value” Price Target For AstraZeneca Stock — & A Rating Upgrade
After reporting 19% revenue growth in Q1, management’s guidance for full-year 2024 revenues and EPS growth in the “double-digit to low teens percentage,” may have slightly underwhelmed Wall Street.
In fact, management was asked about this on the Q1 earnings call, and Chief Financial Officer Aradhana Sarin responded as follows:
as you know, generally, we don’t update or provide more color on the guidance in first quarter. You’ve seen from the reported results, the underlying trend in our revenue product sales is very, very strong across the board. You’ve also mentioned some of the uncertainties that Ruud also mentioned as well as Dave. So those uncertainties are there for the remainder of the year.
However, if our momentum continues the way it has been in the first quarter and some of these uncertainties on VBP pricing, et cetera are in our favor, you can think about our product revenues, our product sales and Alliance revenues could be at the upper end of our range or higher.
This may imply that, if headwinds such as volume-based pricing and macroeconomic challenges are successfully negotiated in Q2, AstraZeneca will upgrade its 2024 guidance, which will trigger a rise in the share price. It should be noted that operational expenses have also been increasing, however, so to deliver a genuinely stellar set of earnings, the company may need to show that these costs are being massaged down towards its stated target for a “mid-30s percentage Core operating margin by 2026.”
My own discounted cash flow analysis suggested that, if AstraZeneca hits its 2030 $80bn revenue target, and its mid-30’s operating margin, using a weighted average cost of capital of ~10%, a present day share price target for AstraZeneca ADR’s is ~$114.
That represents a 45% premium to the current traded share price, and would take the company, and it’s valuation into uncharted territory, so the risks that management’s plans do not come to fruition must be considered carefully.
Six or seven of the 20 new drug launches planned have already occurred, so progress has been impressive to date. However, the challenges are getting harder, as these new products will now be judged on their ability to drive >$5bn in peak annual revenues — no small figure.
Nevertheless, personally, I cannot fail to be impressed by management’s detailed plans and its ambitions, for example to have >50% of lung cancer patients to be eligible for one of its medicines by 2030, and to “eliminate breast cancer as a cause of death.”
I mentioned that management may have created a rod for its back by unveiling such ambitious targets, and inviting Wall Street to punish its share price if it does not live up to these expectations. However, since AZN’s valuation is not excessive, with a market cap <$250bn, I hope clinical progress, growth for the top line, and narrowing operational expenses expected in Q2 persuade Mr. Market to send AstraZeneca shares up >$80, and in time, >$100 per share.
As such, I am upgrading my “hold” call to a “buy” ahead of AstraZeneca PLC Q2 earnings set to be announced next week.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link