
D-Keine
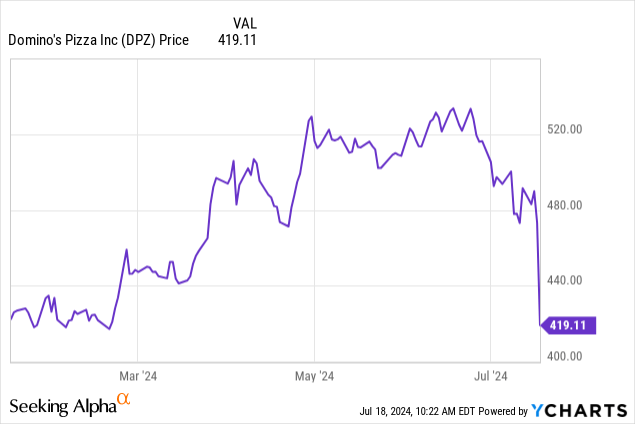
We like Domino’s Pizza, Inc. (NYSE:DPZ) here at $410 for a long-term buy. Shares have corrected some 24% from highs, and we think this sets up entry for investors. This comes following its just-reported quarterly earnings showed a nice profit beat, but some questions surrounding international growth and comparable sales have led to the Street taking some caution.
While consumers are certainly pressured by rampant inflation, and restaurant input costs for ingredients and labor have risen, Domino’s provides its pizza and related products at a very low cost for consumers. While it is not recession proof, it certainly is resistant, as you can feed a family quite cheaply with Domino’s offerings. After this massive collapse in the share price, which historically such declines are buying opportunities, we see Domino’s stock being much more reasonably valued now after falling back from highs of over $540 per share. Let us discuss.
What to watch in Domino’s key metrics
When evaluating the restaurant business, we primarily focus on four key areas. First, we assess revenue growth to determine if sales are increasing. Second, we examine expense control to ensure that rising sales translate into growing profits. Third, we analyze store count changes, such as closures and new openings. Finally, and most critically, we closely monitor comparable sales performance. Let us turn to the numbers.
Just reported numbers strong on the headline results
In the quarter, we saw growth in sales despite the pain in many restaurant stocks. We are buyers here on this morning’s pre-market dip. The company, like so many others, is facing challenges and seemingly overcoming them. The company’s growth will continue long-term. The stock has seen an incredible selloff the last few sessions, but there were strong sales results, all while controlling expenses.
In this quarter, Domino’s delivered a top-line showing growth that was in line, and a nice beat on earnings. Let’s first discuss the revenues.
Sales rising
Sales were up 7.1% in Q2 2024. Volumes were relatively strong, and higher volumes are welcome news, though international left a bit of a question mark. What about same-store sales? Well, the same-store sales increased as did store count globally, helping to boo. Revenues came in at $1.09 billion and were essentially in line with consensus estimates. That is respectable. But how about same-store sales, which is a key indicator?
Well, we mentioned they were up. In the U.S., same-store sales grew 4.8% during the quarter versus the year-ago period. U.S. same store sales growth has occurred for most of the last 10 years. But international same-store sales have been mixed. In this quarter, they were positive, but a bit light. International comps were positive 2.1% during the quarter, but it was less than expected. We are not sure if this justifies a 14% decline today, but we think it’s a buying opportunity. As far as store growth, factoring in closings and remodels, it had global net store growth of 175 stores in the quarter, comprised of 32 net new domestic stores and 143 net new stores outside the U.S.
Margins mixed
While sales were up, we do note that the costs to generate these revenues were higher than we would like. Expense management has long been a strength of the company in our opinion. However, margins were mixed. U.S. Company-owned store gross margin decreased 100 basis points, driven by higher insurance costs and increased labor costs as a result of higher wage rates. However, supply chain gross margin rose 40 basis points thanks to procurement productivity.
Operational income rose $0.7 million, or 0.4%, in Q2 2024 as compared to a year ago. That said, turning to income, we see that net income surged 29.8% versus last year to $32.6 million. On a per-share basis, income was $4.03 compared to $3.08 in the prior year quarter, rising 30.8%. This was a solid beat. When considering the reset valuation and the continued growth metrics of the company, we think this decline is an opportunity.
We also like that the company is repurchasing shares too. During the first half of 2024, the company repurchased 56,372 shares of common stock for a total of $25.0 million. Domino’s still has a remaining authorized amount for share repurchases of $1.12 billion. Finally, the company pays a dividend too, which is about a 1.3% yield.
Why shares are really down
We do not see the slight comp weakness in international as a reason shares are down. We think it was because the international expansion will be much slower than anticipated. This was the reason, in our opinion. Looking ahead, the company sees 2024 annual global retail sales growth of 7% or higher and 8% or more annual income from operations growth. However, management now sees global net store growth of 825 to 925 in 2024. This is down from its guidance metric of 1,100+ global net stores, and is a result of international uncertainty. Domino’s indicated that it expects it will fall 175 to 275 stores below its 2024 goal of 925+ net stores internationally due to challenges “being faced by Domino’s Pizza Enterprises”, and one of its master international franchisees. So Domino’s is working with this partner to solve the international bottlenecks. This guide down on new stores and uncertainty, in our opinion, is the impetus for the selling.
Take home
Shares are down over 20%. The earnings report itself was mostly strong, particularly on domestic sales growth and profit power. The international comps were a touch light, and future international store openings are in question with Domino’s Pizza Enterprises. This uncertainty leads to the Street selling first and asking questions later. However, investors do not often get massive declines like this and when they come around, consider taking advantage.
Credit: Source link