
Baloncici
Following EssilorLuxottica Société Anonyme’s (OTCPK:ESLOF, OTCPK:ESLOY) agreement for two new bolt-on acquisitions, we are back to comment on the company today. Here at the Lab, we have been positive on EssilorLuxottica, recognizing the player as a perfect combination between Value And Growth; however, we recently downgraded the company with a publication called No More Upside. Our rating change was supported by no upgrades on earnings post-Q1 results and a less attractive valuation than in the past. In addition, even if we recognize a positive stance on the Nuance Audio acquisition, the company did not disclose financial targets, and our updated sales projections estimate was only a fraction of the total company’s turnover.
M&A Update
Before the Paris stock exchange opening bell, the Italian-French eyewear giant communicated a double acquisition. The company invested in the American streetwear brand Supreme, acquired from the fashion conglomerate VF, and 80% equity stake acquisition of Heidelberg Engineering. This German company specializes in diagnostic solutions, digital surgical technologies, and IT solutions for clinical ophthalmology.
Supreme’s time under the VF conglomerate came to an end. In number, EssilorLuxottica acquired the company for a total consideration of $1.5 billion.
Related to the Supreme deal, there are two high-level considerations to report:
- VF is a fashion conglomerate with brands such as Timberland, Vans, Eastpak, Northface, and Dickies in its portfolio. Supreme was a solid add-on, and VF could not capitalize on the brand that was very much aligned with its market scope. On the other hand, EssilorLuxottica is a fully integrated player in the design, manufacturing, and distribution of frames and sunglasses. Therefore, we see limited synergies, and more importantly, Supreme’s business is focused on apparel, footwear, and accessories. The company also produces glasses but is mainly a clothing brand. Here at the Lab, we do not fully understand the deal rationale;
- Secondly, this acquisition will be financed entirely in cash. EssilorLuxottica’s debt position further deteriorated. That said, there is ample maneuver for acquisition, and including the latest deal, the company’s ratio of net debt/EBITDA is lower than 2x. Still, we now project a higher interest rate that is detrimental to the bottom line.
On the other hand, we see support for the Heidelberg Engineering investment. The company is particularly active in diagnosing eye diseases such as glaucoma and age-related macular degeneration early. This is also aligned with Nuance glasses, which, in addition to vision problems, can also correct hearing problems of those with moderate hearing impairment. This deal further diversifies EssilorLuxottica’s exposure to the pharmaceutical sector. Heidelberg Engineering was founded by Gerhard Zinser and Christoph Schoess in 1990 and is present in more than 100 countries.
In the press release, the eyewear Group states that ‘Heidelberg Engineering “brings extensive technological and scientific expertise in optical coherence tomography, real-time image processing and analytics, large-scale data analysis, and digital surgical navigation to serve medical professionals, scientists, and researchers across a broad range of ophthalmic areas.”
Q2 Expectation and Valuation
Following our update within the sector and Burberry (OTCPK:BURBY) and Hugo Boss’ recent outlook downgrade, we anticipate a soft quarter. Here at the Lab, we forecast FX-neutral sales growth with a turnover of €7 billion. A favorable trading environment in the North American region supports this. Looking at APAC, despite challenging demand, we anticipate a supportive growth rate. EMEA has sustained growth momentum in its key markets, but we are more cautious about the margin. There was no disclosure in Q1, and we will closely monitor EssilorLuxottica’s magnitude of price increases. Given the Supreme acquisition and considering the cash transaction, we lower our net income projection of $75 million (€67.5 million). This is based on a favorable remuneration of cash interest at 5%. That said, we also assume transaction costs of a similar amount. This is detrimental to our net income projection. Therefore, our earnings decline from €3.15 billion to €3 billion, implying a lower 2024 EPS from €7 to €6.65. As a reminder, our valuation has an EPS estimate for the next twelve months. As it is, we make no change in our 2025 projection. Therefore, rolling forward our EPS, we arrive at €7.3. Applying an unchanged P/E target of 28x, we valued EssilorLuxottica at a target price of €204 per share. Therefore, we have maintained an equal-weight rating. Looking back, the yearly group average P/E multiple was 27.2x in 2021-2023, and cross-checking the sector median, the company trades at a higher multiple (Fig 1).
SA Valuation data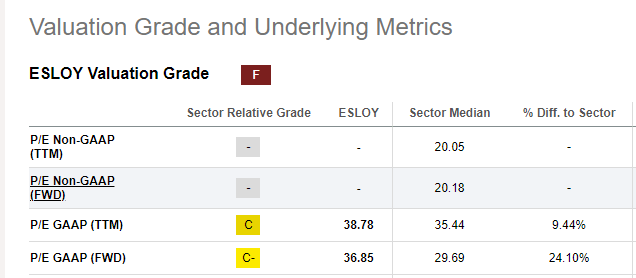
Fig 1
Risks
Our last update has a detailed downside risks section (Fig 2). In addition to our previous analysis, we report additional risks in the Supreme acquisition. This streetwear brand operates outside EssilorLuxottica’s scope, from logistics to manufacturing to global distribution. Indeed, VF decided to exit Supreme with a write-off of almost $600 million. Related to Heidelberg Engineering, we do not have financial disclosure. We should also take into account regulatory approval risks.
More importantly, as several Chinese press sources reported, the Chinese government is evaluating a potential consumption tax that could impact luxury goods.
Mare Evidence Lab’s past analysis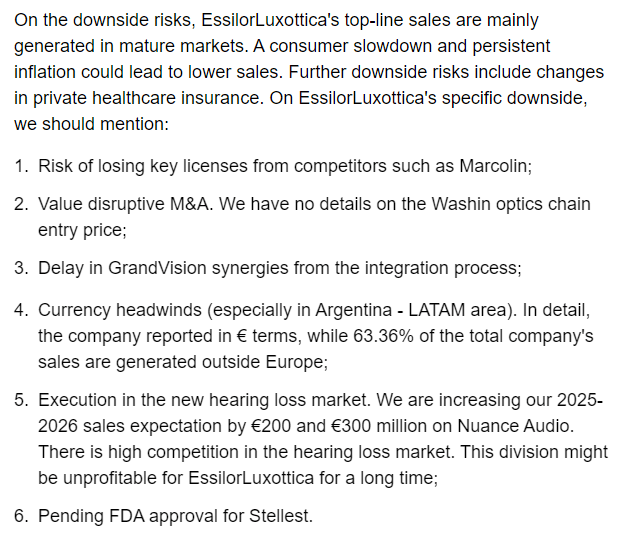
Fig 2
Conclusion
We need more visibility on Heidelberg Engineering’s acquisition and see no rationale for acquiring Supreme. EssilorLuxottica trades above its historical average and the sector median. We continue to see a balance of risk/reward, confirming our neutral rating for the next twelve months’ estimate.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link