
BalkansCat/iStock Editorial via Getty Images
Sentiment continues to deteriorate across the luxury industry as top-line pressures persist and operating leverage declines. Following Kering profit warning in April 2024, the Q2 earnings season kicked off with disappointing results. On 15/07/2024, Burberry appointed a new CEO and published its results, reporting revenues of £458 million, down 22% after a year ended in March already in decline. On 16/07/2024, Hugo Boss cut the current year outlook forecast due to weakening global consumer demand, especially in markets such as China and the United Kingdom.
Compagnie Financière Richemont (OTCPK:CFRHF)(OTCPK:CFRUY) reported a solid start to the year in a complex industry context. This should be taken very well in light of the recent warnings by its closest peers. For this reason, we are not surprised to see a divergence between the S&P Global Luxury Index with an aggregate year-to-date performance of -3.01%, while Richemont’s stock price is up by 19.5%. The company’s Q1 results fully confirmed our January 2024 follow-up called Resilience In The Luxury Sector, Buy Confirmed. As a reminder, our buy rating was supported by:
- An attractive valuation (vs. the sector) and supportive growth projections based on a more aggressive pricing policy for 2024;
- Tactical M&A with a majority stake in Gianvito Rossi and Vhernier to diversify its businesses in the luxury market;
- Solid balance sheet and impressive track record by the CEO.
Q1 Results and Positive Takes
Today, the group presented its results to the investor community. Q1 company top-line sales reached €5.26 million (Fig 1), which is in line with the consensus at €5.28 million. Richemont organic sales grew by 1%, with the relevant jewelry maisons delivering 4%. We should also report that last year, the company delivered sales of 19%. Even if we might conclude that Richemont’s sales were flat in the first quarter, the comps analysis was challenging.
By region, Europe was up by 5%, and America recorded a positive sales progression of 10%. On a negative territory, APAC delivered a -18%. The Middle East was also up by 8%. Richemont managed to balance the Asia-Pacific market deterioration.
By business area, we already reported the positive performance of the jewelry maisons, but we should record a negative trend in Specialist Watchmakers. This segment was down by 13%. However, flagship brands such as Vacheron Constantin and A. Lange & Söhne recorded excellent results during this challenging period. Richemont accounts for brands such as Buccellati, Cartier, and Van Cleef & Arpels in the jewelry maisons.
Regarding the giant’s other brands, Richemont reported that the current momentum of Alaïa and Peter Millar has more than compensated for the weaker sales in the other houses, including Chloé. There was a change in the creative director, and the new collection proposal arrived in stores only at the end of the quarter.
Relevant updates include 1) no guidance, 2) Richemont’s net cash position at €7.7 billion, and 3) no update to the Yoox Net-a-porter sale process. This company is classified as a “discontinued operation” with assets held for sale. Yoox Net-a-porter sales are down by 15% at constant rates in Q1.
Richemont Q1 sales update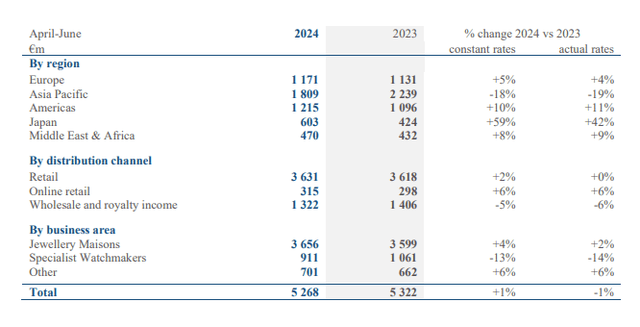
Source: Richemont Q1 results press release – Fig 1
Aside from the results, there are two high-level considerations to report:
- The luxury goods sector has entered a slowing sales growth momentum, and this is an industry-specific cycle. That said, here at the Lab, we believe the jewelry category may fare better than the market’s current negative expectations. Customer scrutiny of luxury goods’ “value for money” is less aggressive in the jewelry category. Handbag prices have seen disproportionate prices increase in the last few years, with short-term saturation for the category. There is a price gap that Richemont could grab, and in this context, we continue to favor the company as the best play;
- Secondly, the cash position has improved healthily on a yearly level. This implies reasonable costs and cash control in the company. It also means healthy, well-balanced growth for the luxury player.
Financials and Valuation
In our last analysis, supported by better results in the jewelry category division, we increased our turnover estimates to €21.6 billion. This implied a 5% growth rate compared to 2023. After the Q1 results, we believe that Richemont is aligned with our year-end target. Therefore, we apply no change in our sales evaluation. With better cash on the balance sheet, we might suggest a better-than-anticipated operating leverage projection. Cost control in the business continues, and we believe there is a potential for a margin uplift. We now forecast an EBIT margin of 24.5%, with 100 basis points higher compared to the 2024 results. In addition, there has been no change in corporate tax, but we have increased our cash balance. We do not anticipate relevant M&A, and we estimate higher interest income, which supports a better-than-estimated EPS, moving from €7.55 to €7.6 on a twelve-month forward basis.
Here at the Lab, the luxury sector average moved from a median P/E of 21x to 18.26x (Fig 2). In our previous report, Richemont was trading below their peers’ average, but we have always had a favorable view of deserving a higher multiple. We still apply a 20x P/E (aligned with the company’s historical average) for reasons of consistency and superior performance. With our EPS of €7.6, we derive a target price of €153.2 per share, equal to CHF 149.3.
Richemont SA Valuation data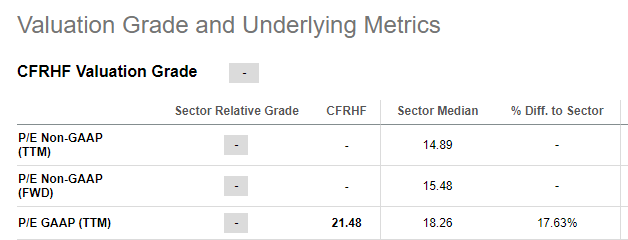
Fig 2
Risks
Our last coverage has a detailed downside risks section (Fig 3). In addition to our previous report, we include a delay in the Yoox Net-a-porter sale process. We would also like to have more financial details in the Q1 and Q3 results update.
Mare Evidence Lab’s past analysis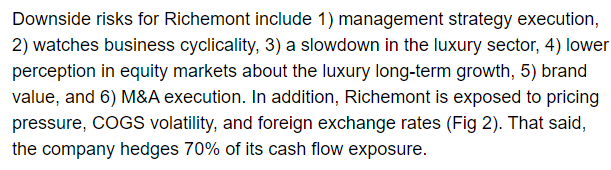
Fig 3
Conclusion
Richemont offers exposure to the jewelry category, which has high barriers to entry. In addition, it has a healthy balance sheet with good cost control at the P&L level. With the latest acquisition, Richemont is more diversified and continues to be one of our favorite companies in the segment.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link