
Wirestock
Introduction
I’ve been cautious on consumer discretionary stocks lately, largely because of a weakening consumer, with most households choosing to pullback on discretionary purchases like dining out. As such, I’ve become increasingly selective in picking my spots, choosing to favor companies with more robust business models, are outperforming peers, have growth opportunities available, and trade at decent valuations that offer a margin of safety. In my view, Pizza Pizza Royalty (TSX:PZA:CA) (OTCPK:PZRIF), the owner of the licenses and trademarks associated with the Pizza Pizza and Pizza 73 brands, fits that bill. In this article, I’ll discuss my investment thesis on the company and why an attractive royalty model, a track record of consistent growth, expansion opportunities, and strong results amidst a weak economic backdrop make this a compelling investment in the sector.
Company Overview
Pizza Pizza Royalty owns the rights and royalties to the Pizza Pizza and Pizza 73 brands in Canada. For Pizza Pizza, the company’s larger of the two brands, the company primarily operates out of Ontario and BC, but has a presence in 9 out of 10 provinces with over 600 restaurants. For Pizza 73, the company has 102 restaurants (all in western Canada) with 96 of them being in Alberta.
Investor Presentation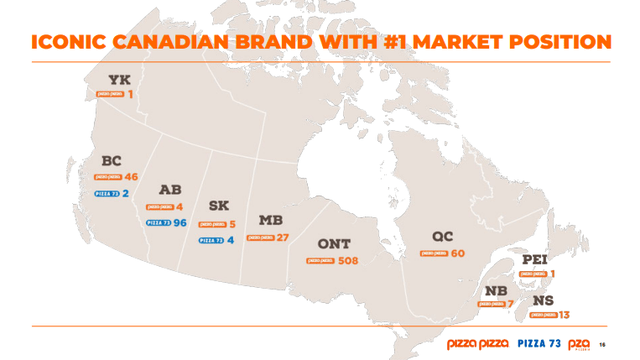
The Royalty Model
Pizza Pizza operates a royalty model. This isn’t too dissimilar to what many restaurant companies do – think A&W (AW.UN:CA) – but we see this in other industries to like oil and gas, precious metals, and even in pharma.
Unlike a traditional restaurant, Pizza Pizza doesn’t have to subject itself to labor issues, operating costs (e.g., sourcing resources) and managing customers. Rather, the company focuses on the bigger picture things like managing the brand, advertising, and allocating resources towards strategic initiatives that benefit the entire franchise network.
Franchisees (those who operate and run the stores) love it because they can focus on what they do best. They also receive marketing help, access to key relationships (e.g., suppliers) and training support and hiring best practices for employees. Perhaps most importantly, they benefit from the goodwill established by the brand, as the franchisees will have customers in their market who are already familiar with them from day one.
In return, the franchisor (Pizza Pizza) enjoys royalty fees (a percentage of sales from franchisees) which generally increase as these stores do well, highlighting aligned incentives. Moreover, the royalty model is great because it allows for steady, predictable revenues and risk sharing by shifting operational risks to franchisees and diversifying risk across different franchisees in different locations and markets.
Track Record of Consistent Growth
One of the things I like about Pizza Pizza is its track record of growing its restaurant count over the years. Since the IPO in 2005, the company has expanded its restaurant count by 272 stores for a 54% increase to 777 at the end of last year. On a compounded annual basis, this equates to a growth rate of 2.4% per year. That may not sound like a lot, but keep in mind that most brick-and-mortar pizza locations aren’t expanding. As the company has grown entirely in Canada, it’s continued to incrementally steal market share away from competitors. Moreover, even with a saturating market in Canada, Pizza Pizza has announced that it will pursue new markets, most notably Mexico, for expansion.
Investor Presentation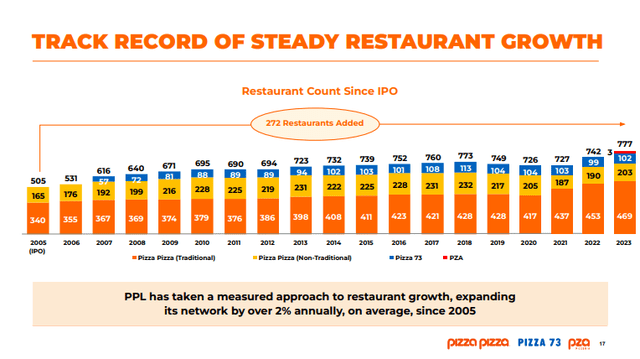
If there’s any reason to hold a royalty company in your portfolio, it’s almost certainly for the dividend distributions. Unlike most companies that pay a flat, consistent dividend, Pizza Pizza has had a track record of growing its distributions to shareholders over time. Funded by the growth in the business (both in terms of higher store count and same store sales growth over time), investors have been rewarded with regular dividend raises, which is one reason why I find the company’s shares compelling. With a 92% payout ratio, the company pays a 7.2% dividend yield that’s seen regular increases, barring the 2020 period when the pandemic hurt restaurant sales as a result of lockdowns and feats of dining out.
Investor Presentation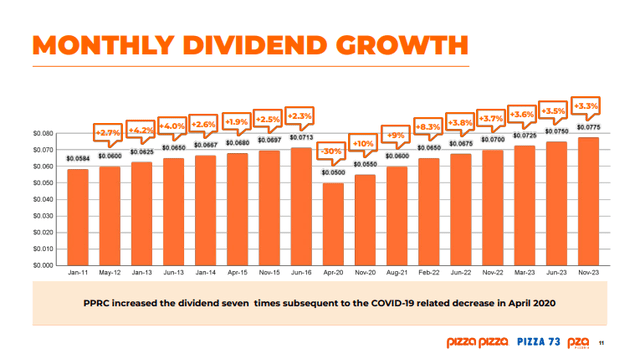
Expansion Into New Markets
It’s rare to find a royalty company that pays a growing and high dividend. But just as Tim Horton’s (QSR:CA) looks to expand in China and A&W with growth opportunities in Southeast Asia, Pizza Pizza is gunning for growth abroad. In the announcement for the company’s growth plans in Latin America’s second largest economy, CEO Paul Goddard said the following:
“There comes a certain point where you do become too saturated. I think we’re still a long way from that. But in a place like Toronto, for instance, we have 200 locations. We don’t need 500 locations in the city of Toronto. That would probably be too many.”
While the company thinks they still have further room to grow (to around 1000 stores from the 777 currently), the company wants to make sure they have “smart growth” and avoid cannibalizing current locations against each other. Again, because Pizza Pizza takes a slice of revenue as a royalty, the company’s incentives are aligned with franchisees as it doesn’t benefit if it cannibalizes its own revenue, compared to if it grew the total pie.
In terms of the international expansion, the announcement includes Guadalajara-based KSG/GrünCorp, who already has expertise in restaurants and real estate. In my view, working with a partner significantly de-risks the strategy to expand in Mexico.
Strong Results In A Weak Consumer Environment
I’ve had mildly bearish outlook on consumer discretionary stocks, particularly those attached to leisure and restaurants. With Pizza Pizza, I find it to be one of the few companies I’ve looked at that seems very well-positioned to navigate a challenging consumer environment.
For example, in the company’s latest Q1 results, Pizza Pizza reported total system sales of $148.9 million, which was up 4.3% on a year over year basis. Royalty income for the quarter clocked in at $9.6 million, up 4.6% compared to last year.
Company Filings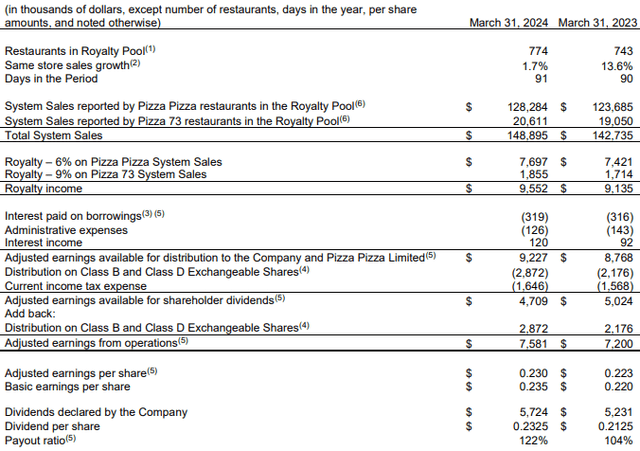
When we look at what drove the results, what I was most impressed with was the company’s same store sales growth. With Q1’24 in the bag, this marked the company’s 12th straight quarter of positive same-store sales growth. Same-store sales growth was 1.7% same-store sales growth as Pizza Pizza reported 0.6% growth and Pizza 73 reported 8.5% growth. A 1.7% growth on a year-over-year basis may not sound like much, but keep in mind what comps we’re comparing this to. In Q1’23, the company reported same-store sales growth of 15.5% (versus Q1’22), so any growth on top of this was going to be a tall ask. So despite mild weather challenges and a soft consumer environment where consumers are choosing to eat out less, it seems that Pizza Pizza has navigated consumer weakness quite well.
On the earnings call, management noted several successful menu innovations (i.e., strombolis and poutines; significant growth in lunch and snack day parts driven by new offerings including snack boxes and panzerottis) which seem to be resonating with consumers well. The company has talked about its convenient delivery or in-store pick-up options, which help to improve the customer experience. Finally, the company has also been making investments in its technology through digital improvements, which includes things like push notifications, visual order tracking, and increased online presence, helping to grow how much customers spend with the company. For the Pizza 73 brand in particular, it also benefited from the website/mobile app launch earlier in the year, as well additional third-party channels, and store renovations.
Valuation and Wrap Up
Looking ahead, I think there could be some moderation in same-store sales growth for the balance of 2024. While the comps could get easier, I think low single-digit growth in same store-sales growth would be my base case, with potential for mid-single digit growth into FY’25. At present, the company still faces risks related to reduced consumer discretionary spending, increased consumer price sensitivity, increased competition, factors that could weigh on results. On the earnings call, management commented on some aggressive promotions from peers recently, so I’d watch how this unfolds in the quarters to come with respect to how Pizza Pizza navigates this. At present, I’d assign the company an A rating for its resiliency compared to most restaurant companies I’ve looked at.
On valuation, Pizza Pizza trades at 13.2x next year’s earnings, which is a 0.3x turn discount to its historical ten-year average (source: S&P Capital IQ). Overall, this discount may be warranted, given the competitive pressures that the company faces, coupled with a weak consumer environment. On an absolute basis, 13.2x forward P/E doesn’t seem that expensive for a company that should be able to grow in the low-single digits at minimum over the long-term
Author, based on data from S&P Capital IQ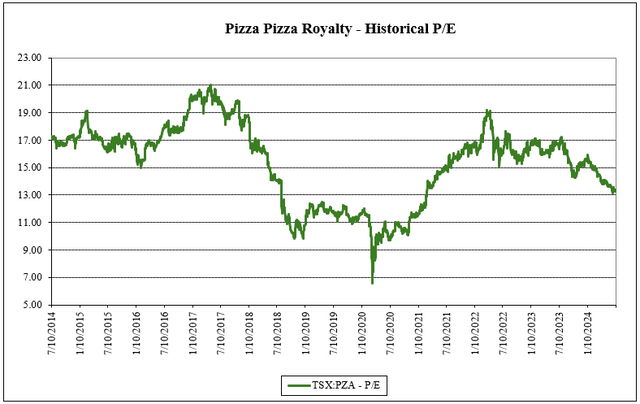
Compared to Canadian franchisors, the company trades at a 1.7x discount on forward P/E. While there’s no perfect comparable (a Canadian pizza franchisor), I find the current valuation compelling relative to the comps set.
Author, based on data from TD Cowen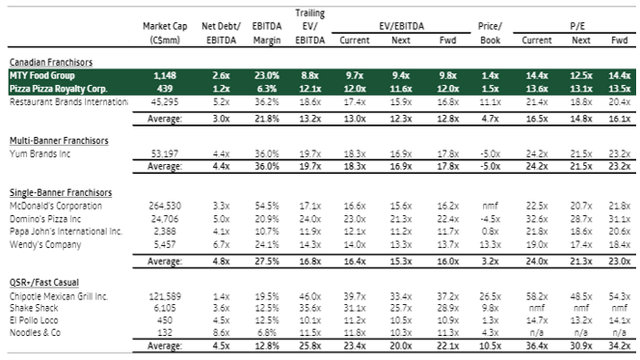
Altogether, Pizza Pizza is a relatively safe investment that pays a generous yield. The royalty model has a number of benefits that make it a more predictable business, as opposed to having operational uncertainty and risk with locations being company owned. In my view, with expansion into new markets, growth opportunities, and investments in digital capabilities and menu offerings, I think Pizza Pizza is taking the right steps to grow the business. Given that the company has a track record of growing the business, I find the investment to be somewhat de-risked. While a weaker consumer environment could persist, with shares at an attractive valuation and shares close to 52-week lows, I’d be a buyer of shares today.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link