
oliver de la haye/iStock Editorial via Getty Images
In the summer of last year, I saw strong signals in the case of Federal Signal Corporation (NYSE:FSS). Momentum at the time was impressive, although I recognized that this has not always been the case in the past. Amidst demanding valuations and a real transition to make regarding electrification, I was a bit reserved.
Ever since, Federal Signal has seen continued momentum, which has been awarded ever-higher earnings multiples by the market. While I like the transition which the business made, the risk-reward here simply does not look compelling. This makes me very cautious here, despite the solid operating performance, as shares have simply commanded too much of a premium valuation here.
Specialty Equipment Manufacturer
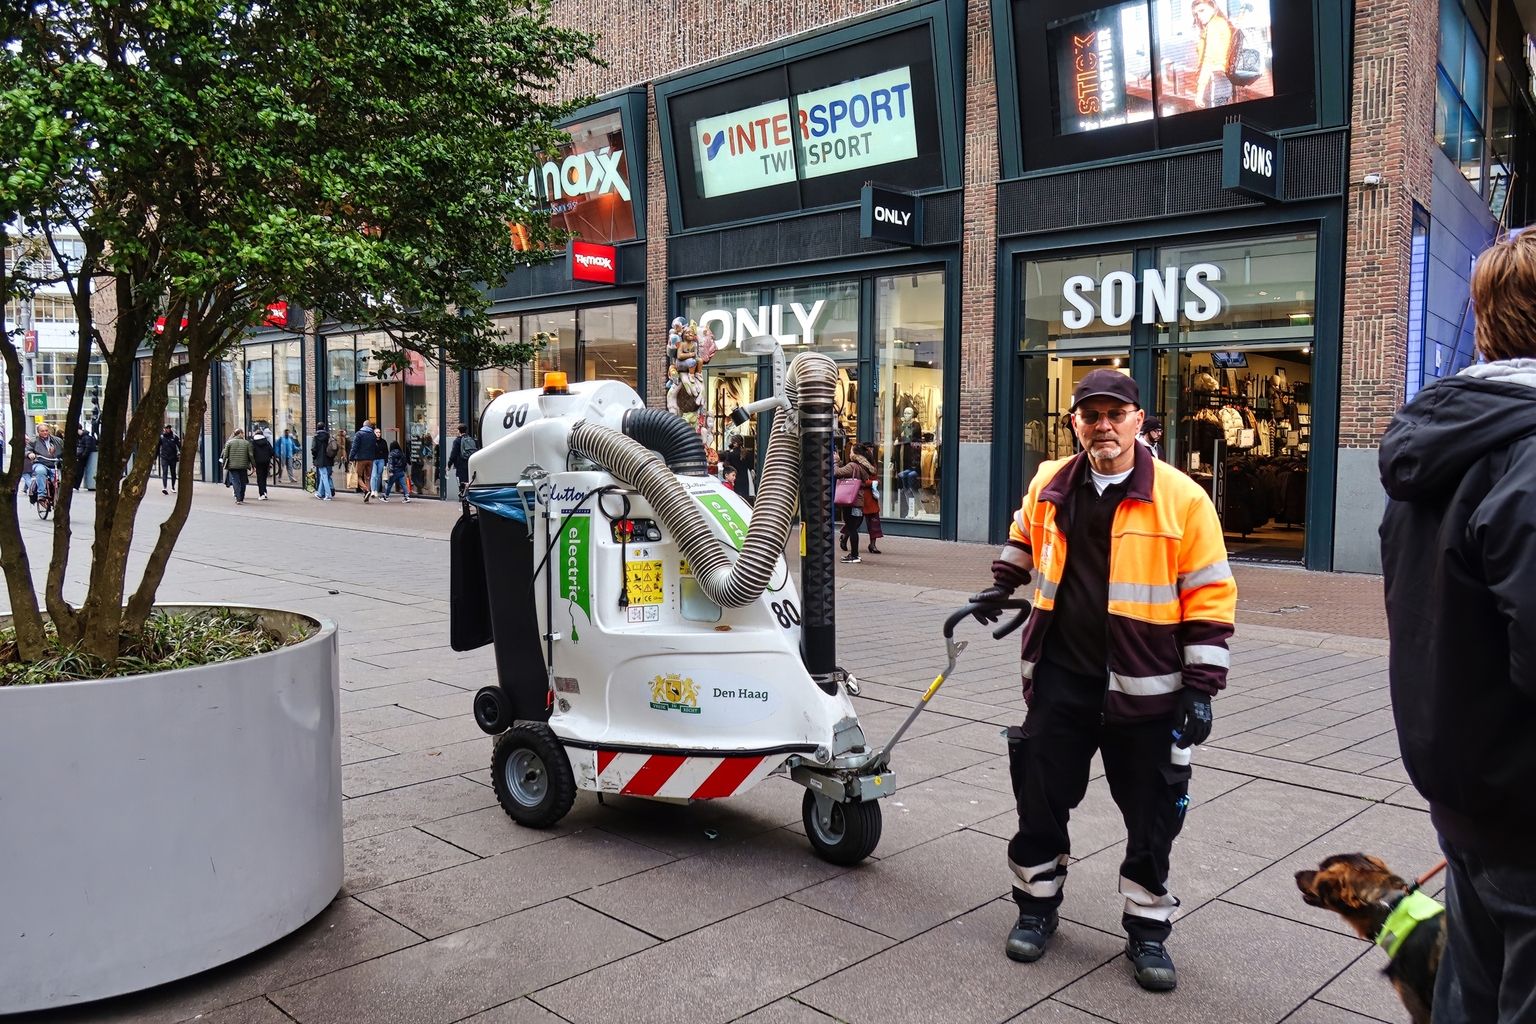
Federal Signal is a so-called specialty equipment manufacturer, making sweepers, sewer cleaners, and security equipment. Already, a stock trading in the $30s in the 1990s, its shares gradually came down to $5 per share during the recession amidst lackluster operating performance, although shares recovered to the $30 mark ahead of the pandemic.
Just ahead of the pandemic, the company generated some $1.2 billion in sales on which it posted earnings of $1.80 per share, resulting in quite fair valuations. As of today, the business has been very diversified. Sweepers, road marking, water blasting and other, make up nearly a quarter of sales, as the same applies to vacuum trucks and aftermarket sales. All this is complemented by dump truck bodies, public safety, industrial signing, among others.
In terms of end markets, half of sales are generated from publicly traded clients, some 40% from industrial clients, and the remainder from the energy and utility sector. In terms of classification of end markets, over 80% of sales are generated from ESG solutions, with the remainder coming from signal solutions, referring to the name of the business.
The electrification trend, ever more complex vehicles and infrastructure spending all act as drivers for the business here, but in some regards make that innovation will need to be performed in the own product line-up as well.
Momentum Is Unleashed
When I looked at the shares in August of last year, shares had rallied to the $60 mark, while modest growth has been seen from pre-pandemic levels.
Amidst an acceleration in the business, aided by dealmaking, the company guide for 2023 sales to come in at midpoint of $1.67 billion, with earnings seen around $2.30 per share. This made that the company enjoyed some operating momentum again, but earnings multiple in the mid-twenties and a 1.5 times leverage ratio made me a bit cautious from a valuation standpoint.
This was furthermore the case as the company still had to undergo a real transition with electrification, although its equipment generally lends itself pretty good for such purposes. At the same time, the valuation had run away a bit much for me to find appeal around the $60 mark.
The Move Continues
Since August of last year, Federal Signal Corporation shares have risen another 40%, now trading at $84 per share, and that is even after shares are down nearly ten dollars from recent highs.
This was in part fueled by a convincing 20% hike in the dividend at the start of the quarter, although a quarterly dividend of $0.12 per share now yields a dividend far below a percent.
Later in February, Federal Signal announced a 20% increase in full-year sales to $1.72 billion, with organic growth being responsible for 15% of the growth. The company posted solid 13% operating GAAP margins at $224 million, and that is even after already incorporating a $15 million amortization charge. All this made that after tax earnings came in at $2.56 per share on a GAAP basis (with adjusted earnings posted two pennies higher), with both sales and earnings far outpacing the original outlook for the year.
Moreover, momentum remained strong, with full-year orders of $1.87 billion resulting in a book-to-bill ratio of 1.1 times, adding to a backlog which has now topped the billion mark, at $1.02 billion. Furthermore, momentum was spread nicely across both divisions, both at the environmental solutions group and as well as at the safety and security systems group. Net debt, that is excluding lease and pension liabilities, stood at just $238 million, all very manageable as it trailed the $286 million EBITDA number posted for the year.
The company guided for modest growth in 2024, seeing sales between $1.85-$1.90 billion, largely at par to the order intake in 2023, with sales seen up around 9% at the midpoint of the guidance. Adjusted earnings were seen at $2.95 per share, plus or minus ten cents, up 14% compared to 2023.
Momentum Continues
In April, it became apparent first quarter earnings showed a pretty picture. First quarter sales rose by 10% to $425 million, driven by 7% organic growth. GAAP earnings of $0.84 per share nearly doubled from a $0.45 per share number in the year before, aided by a small tax refund. Adjusted earnings of $0.64 per share were up a very solid 39% as well.
Moreover, the company raised the full-year earnings guidance by ten cents to a midpoint of $3.05 per share, all while net debt came down to $222 million. Furthermore, an order intake of $503 million only added to the backlog, which rose to $1.10 billion as of the end of the quarter.
Amidst all this, the momentum continues to be very strong and in fact surprised me somewhat. While this is greatly to be applauded, a 27 times forward earnings multiples is quite demanding, even as leverage is very modest here, leaving financial room for more M&A. While I am shrugging off the fact that this was a mediocre performer in the past, the reversal from a modest valuation to a huge premium feels a bit overblown.
Politics and budgets are a driver of the business, as the question, of course, remains how things will evolve post the election in the fall. Hence, I cannot continue to escape the feeling that shares have been trading at too rich valuations here, making me very cautious. While I applauded management on the great performance, shares have been on a real run recently, backed up by a decent performance of the business, but in part the result of valuation multiple inflation as well.
Shares definitely deserve a continued spot on my watch list, in case of an unexpected and substantial setback or stagnation, but for now, Federal Signal Corporation shares remain a lot too expensive to create a compelling risk reward here.
Credit: Source link