
Growing stacks of coins alongside a piggy bank represent the power of compounding. erdikocak
There is much that can be said about the power of compounding. Depending on what side of the ledger somebody is on financially, it can either be their greatest friend or their worst enemy.
My favorite quote that applies to compound interest is most often attributed to Albert Einstein. Whether he said it or not is a subject of debate. Regardless, it doesn’t take away from the validity of the statement:
Compound interest is the eighth wonder of the world. He who understands it earns it. He who doesn’t pay it. Albert Einstein (maybe)
For the sake of compounding, I could focus on the tenets of sound personal finance, such as paying off credit card debt in full each payment cycle. Since Seeking Alpha revolves around investing, though, that’s what I will be focusing on here today.
Atmos Energy (NYSE:ATO) is one great business in our master list at The Dividend Kings that recently caught my attention. In my view, this is a practical illustration of what compounding can look like in the real world.
Dividend Channel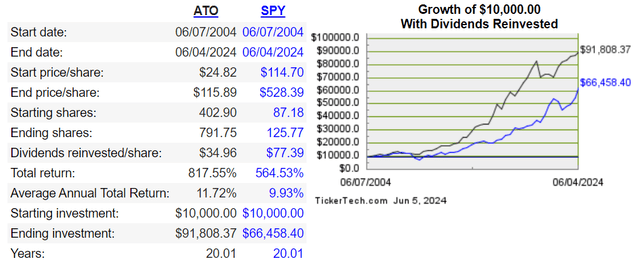
A $10,000 investment in the regulated gas utility in 2004 would now be worth $92,000 with dividends reinvested per Dividend Channel. That’s well ahead of the $66,000 that the same investment amount in the SPDR S&P 500 ETF Trust (SPY) would be worth today with dividends reinvested.
Today, I’m going to be initiating coverage in Atmos Energy (hereafter referred to as ATO) with a buy rating. The reasons for this buy rating that I’ll unpack as the article unfolds include:
- The potential for respectable future earnings growth. The catalysts for this include a growing customer base and substantial planned capital investments through 2028.
- A rock-solid balance sheet to finance growth ambitions.
- I believe ATO can build on its 40-year dividend growth track record.
- The current share price makes the stock’s valuation interesting.
Demographic Trends And Capital Investments Can Fuel Continued Growth
ATO May 2024 Investor Presentation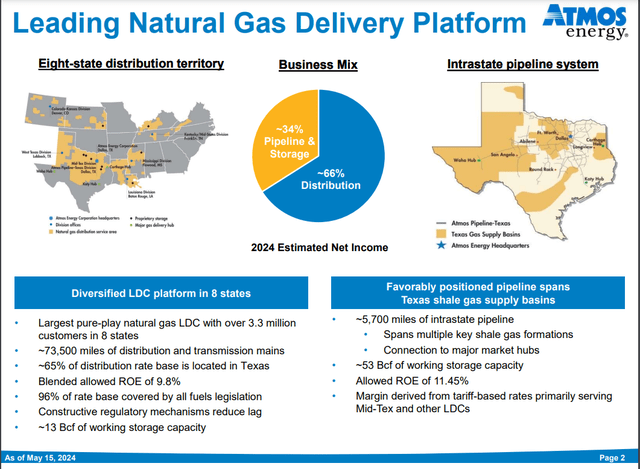
ATO is the nation’s largest pure-play natural gas distributor. The company’s network of approximately 73,500 miles of distribution and transmission mains serves 3.3 million customers throughout the United States. ATO’s rate base is about 65% concentrated in Texas. The remaining rate base is located in Kentucky, Tennessee, Virginia, Louisiana, Mississippi, Colorado, and Kansas.
The company is divided into two operating segments:
- Distribution: This segment provides regulated natural gas distribution services to customers in the aforementioned eight states. ATO anticipates that the segment will account for two-thirds (66%) of net income in FY 2024.
- Pipeline & Storage: This segment engages in natural gas transportation for third parties and also owns and operates five underground storage facilities in Texas. The company expects that the segment will contribute the remaining third (34%) of net income in FY 2024.
ATO May 2024 Investor Presentation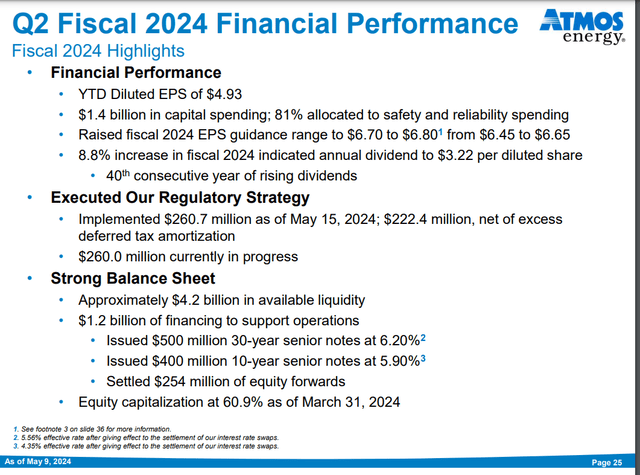
ATO’s financial results in the fiscal first half were a testament to the strength of its fundamentals. The company’s operating revenue fell by 7.2% year-over-year to $2.8 billion during the first half.
At first, this seems to be a contradictory statement. How could an operating revenue decline be indicative of strength?
As a regulated natural gas utility, the answer lies in ATO’s business model. The company can pass on the cost of natural gas to its customers. This means a rise in natural gas costs is offset by increases in operating revenue.
In the first half, the opposite was true. Natural gas prices were lower, so ATO received less operating revenue via bills to its customers.
This headwind to the topline was partially offset by the exceptional demographics of its service area. According to opening remarks from ATO’s President and CEO Kevin Akers during the Q2 2024 Earnings Call, favorable employment trends in Texas helped the company’s customer count to grow. The company added 56,000 customers to its customer base in the 12 months ended March 31, 2024. More specifically, 43,000 of those new customers were located in Texas. The booming economy continues to attract net migration to the state.
ATO’s reduced operating revenue base came with a notable benefit: Improved profitability. The company’s 24% plunge in purchased gas costs helped its net profit margin to expand by 570 basis points to 26.5% through the fiscal first half.
That is how ATO’s net income soared by 18.1% over the year-ago period to $743.3 million in that time. As a regulated utility, the company has recently issued additional shares to fund its growth spending. That led to a 5.3% uptick in the diluted weighted average share count to 150.5 million. Even so, diluted EPS rose by 12.1% year-over-year to $4.93.
ATO May 2024 Investor Presentation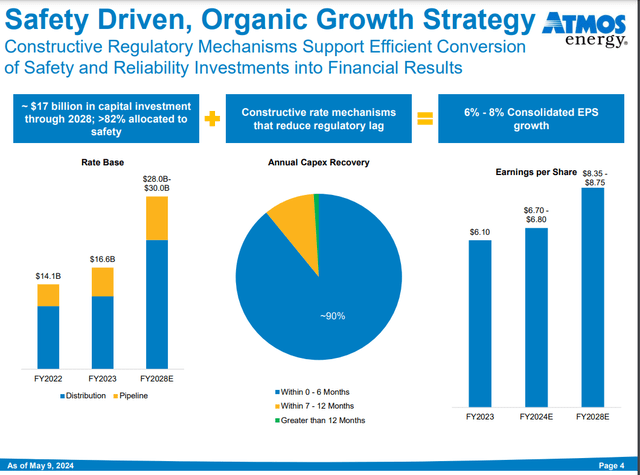
Looking toward the future, ATO’s growth outlook is positive.
Per Akers, new home starts in North Texas surged 44.7% higher in the first calendar quarter of 2024. The annual new-home start rate has reached the highest pace since mid-2022. That should bode well for new customer growth in the quarters and years ahead.
Additionally, ATO plans to invest $17 billion in capital spending through 2028. Most of this spending will be dedicated to improving the safety of its infrastructure, with the remaining spending being allocated to meeting growing customer demand.
That is expected to drive the total rate base from $18 billion in FY 2023 to a midpoint of $29 billion ($28 billion to $30 billion) by FY 2028. This should back up the 6% to 8% annual diluted EPS growth that ATO is targeting.
The beauty of this capital spending is that it is also well-supported by the business model. This spending is via constructive rate mechanisms that reduce regulatory rate lag. That means 90% of ATO’s annual capex spending starts to earn a return within six months of completion.
The company’s blended allowed return on equity of 9.8% is also well above its cost of capital. As proof of what I mean, ATO recently issued approximately $1.2 billion in debt/equity to support operations. Of that, $500 million was 30-year notes at 6.2%, another $400 million was 10-year notes at 5.9%, and $254 million was equity issuances.
That is made possible by ATO’s A- credit rating on a stable outlook from S&P. This is bolstered by an interest coverage ratio of 9.2 through the first half of FY 2024 (unless otherwise noted or hyperlinked, all details in this subhead were according to ATO’s May 2024 Investor Presentation and ATO’s Q2 2024 10-Q Filing).
Shares Could Be Worth $125 Each
FAST Graphs, FactSet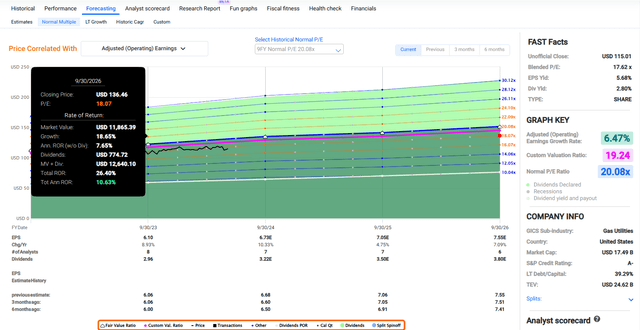
Shares of ATO look to offer decent value from the current $115 share price (as of June 6, 2024).
The regulated natural gas utility is priced at a current-year P/E ratio of 17.1. This is moderately below the 9-year normal P/E ratio of 20.1 per FAST Graphs.
Of course, for much of that time, the Federal Reserve has observed a zero interest rate policy. Rates will probably come down by around 200 basis points in the next two years or so. But that will still be higher than the average over the last nine years.
The company appears positioned to deliver diluted EPS growth in the high-single-digits annually. That would also be in line with what it has historically accomplished.
These higher interest rates are why I think that the fair value multiple will re-rate 10% below the 9-year normal P/E ratio. Put another way, that’s one standard deviation. This would be a fair value multiple of 18.1.
Since the first half of ATO’s fiscal 2024 is complete, I will weigh 50% of my earnings input using FY 2024 and the other 50% using FY 2025. That gives me a 12-month forward diluted EPS forecast of $6.89.
Plugging this in with a P/E ratio of 18.1, I arrive at a fair value of $125 a share. From the current share price, that would mean shares of ATO are 8% undervalued. If ATO reverts to my fair value multiple and matches the growth consensus, 26% cumulative total returns could be posted by the end of its FY 2026.
I’m Expecting More Of The Same Robust Dividend Growth
In my view, ATO’s 40-year dividend growth streak that makes it a Dividend Aristocrat is showing no signs of ending anytime soon. This is enough to earn an A+ grade from Seeking Alpha’s Quant System for dividend consistency.
ATO’s 2.8% forward dividend yield is well below the 3.9% utilities sector median. This is why it has a D+ grade for forward dividend yield from the Quant System.
ATO more than makes up for this lower starting income with its high dividend growth rate. The company’s dividend has compounded by 8.9% annually in the past five years, which is better than the sector median of 5.2%. This is why the Quant System awards a B grade to ATO for the metric.
The most recent 8.8% dividend raise suggests that dividend growth isn’t decelerating, either. An examination of ATO’s payout ratios supports similar dividend growth moving forward. That’s why the Quant System forecasts forward dividend per share growth of 8.7%.
Courtesy of the Zen Research Terminal, ATO’s 48% EPS payout ratio is substantially better than the 75% EPS payout ratio that rating agencies prefer from the industry.
The company is slated to pay $3.22 in dividends per share in FY 2024. Against the $6.73 analyst consensus for the fiscal year, that would be a 47.8% payout ratio. Along with a vigorous balance sheet, this is why I also think dividend growth can come in ahead of earnings growth for the foreseeable future.
Risks To Consider
ATO is an all-around exceptional business, but there are risks to the investment thesis.
Geographic concentration presents one set of risks to the company. This is because approximately 65% of ATO’s distribution rate base is located in Texas (per ATO’s May 2024 Investor Presentation). The good news is that this has been a favorable regulatory environment and that is expected to remain the case in the years to come. If this didn’t hold up, though, it could be a drag on ATO’s growth prospects.
Additionally, this geographic concentration means that the company’s infrastructure is vulnerable to natural disasters. If severe natural disasters occurred, they could interfere with ATO’s operations. In a worst-case scenario, the company’s infrastructure could be damaged beyond insured amounts. That could erode ATO’s earnings power.
The materialization of any of these events could also result in credit downgrades from rating agencies. If this happened, ATO’s cost of capital could rise. If this rose significantly enough, that could jeopardize the company’s plans to spend $17 billion on infrastructure upgrades/expansion through 2028.
Summary: Appealing Total Return Potential From A Dividend Aristocrat
ATO is a utility that checks off all of the boxes for me. According to FAST Graphs, the company’s diluted EPS has grown in 17 out of the past 20 years. Population growth throughout ATO’s service areas and capital spending plans should translate into healthy future growth. The company should also have the means to keep handing out high-single-digit annual dividend hikes. Finally, shares offer an ample margin of safety for me to rate them a buy now.
Credit: Source link