
EXTREME-PHOTOGRAPHER
Sportsman’s Warehouse Holdings, Inc. (NASDAQ:SPWH), the sporting goods retailer, reported the company’s Q1 results on the 4th of June after market hours. The stock quickly fell by up to -20% in the following day’s market open as the results showed continued weakness.
I previously wrote an article on the stock, titled “Sportsman’s Warehouse: Temporary Weakness Requires A Long-Term View.” In the article, published on the 13th of November in 2023, I upgraded my rating into buy as the valuation had slid into a seemingly attractive level when compared to normalized earnings. Since, the company has continued to post weak financials and as a result, the stock has returned a negative –35% compared to an S&P 500 (SP500) return of 19%.
My Rating History on SPWH (Seeking Alpha)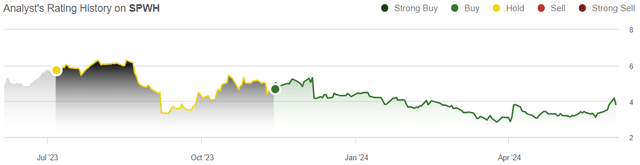
Weak Q1 Results From Sportsman’s Warehouse
Sportsman’s Warehouse reported the company’s Q1/FY2024 results after market hours on the 4th of June. The report showed revenues of $244.2 million, down -8.7% year-over-year. The GAAP EPS came in at -$0.47 compared to a Q1/FY2023 EPS of -$0.42 in the typically seasonally weak quarter. Same-store sales were down by -13.5%, continuing a weak performance from the Covid pandemic peak to a currently macro-pressured level.
The results missed Wall Street analysts’ estimates. Revenues missed by a margin of $4.1 million and the EPS missed by $0.09. While both financial metrics had a miss, the miss wasn’t very dramatic as weak financials were already expected from the quarter. I believe that the Q1 results were worth a slight negative stock reaction, but don’t call for a very significantly negative reaction, especially with a continued upbeat FY2024 profitability outlook.
The FY2024 Outlook Was Reaffirmed
Although the results in Q1 were soft, Sportsman’s Warehouse reaffirmed the previously given FY2024 outlook. The company continues to expect $1.15-1.23 billion in sales and an adjusted EBITDA of $45-65 million, with the sales outlook down -10.7% to -4.5% year-over-year, but the adjusted EBITDA up significantly from $24.6 million achieved in FY2023.
I believe that caution around the given outlook is wise, especially with the given adjusted EBITDA range. The outlook expects quite a similar revenue year-over-year revenue performance in FY2024 as Q1 showed, but the adjusted EBITDA is expected to rise substantially even though Q1 showed a slight year-over-year decline in the metric.
Sportsman’s Warehouse’s management has related heavily to inventory management as a key issue. It appears that the assortment has now started to improve, with the Q1 earnings call seeming more optimistic about the assortment. The better assortment should be able to aid profitability, but the scale of improvements is yet unseen, and the adjusted EBITDA range seems to expect quite a notable shift upwards. While improvements have been made, Sportsman’s Warehouse’s inventory management is still in progress and improvements look to be gradual.
Q1 Results Are a Continuation of Macro & Industry Weakness
After my previous article, Sportsman’s Warehouse has also reported Q3 and Q4 results from FY2023, showing a gradually improving financial performance. Revenues declined by -5.3% in Q3 and by -2.3% in Q4, suggesting a gradual recovery that the now-reported Q1 results haven’t continued as the already-given FY2024 outlook suggested. Profitability continued to decline in the second half of FY2023 into near breakeven operating income.
*Note possibility of rounding errors (Author’s Calculation Using Financial Report Press Release Data)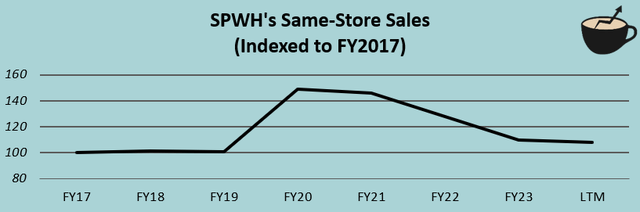
With trailing financials, same-store sales are now approximately 7.7% higher than in FY2017 and 7.0% higher than in FY2019 before the Covid pandemic that caused a massive spike in FY2020. While the sales are higher by a good amount, the CAGR has been only 1.6% from FY2019 in a period of rapid inflation – I expect that same-store sales will eventually recover to a better level after the bleak FY2024 outlook, and believe that Sportsman’s Warehouse’s continued notation of macroeconomic pressures holds its ground. Also, revenues should improve slightly as more recently opened stores start attracting more customers.
Some industry trends are also behind the revenue weakness. Sportsman’s Warehouse’s firearm and ammunition sales have continued to decline, and the trend seems to be in line with the industry as a whole – for example, AMMO, Inc. (POWW) and Vista Outdoor’s (VSTO) firearms segment reported wide revenue declines with -17% and -13% in year-over-year revenues reported in the latest quarter respectively. While it appears that Sportsman’s Warehouse’s revenue declines are still partly a fault of the company, industry shifts have also clearly played a major role in the financial performance.
Sportsman’s Warehouse’s Strategy Has Shifted
There has been a notable shift in Sportsman’s Warehouse’s forward capital allocation strategy – in my previous article, I had a paragraph titled “A Failed Strategy?” suggesting that the company’s aggressive store growth plan could have backfired on the company. Now, Sportsman’s Warehouse’s focus has clearly shifted to focusing on improving current stores’ metrics, with only $20 million to $25 million in capital expenditures and no new store openings expected for FY2024 compared to $79.9 million spent on investments in FY2023. The capital allocation is a notable shift from Sportsman’s Warehouse’s previous strategy of aggressive expansion, and I believe that the change is highly welcome.
The company laid out the Go Forward Plan in April, addressing the strategic shift and noting operational efficiency initiatives. Key initiatives include thorough improvements in the customer experience in stores, such as better customer service, in-store visual enhancements, improved omnichannel capabilities, a better loyalty program, improved assortment management with rationalized SKUs, and improved marketing efforts.
SPWH April 2024 Go Forward Plan Presentation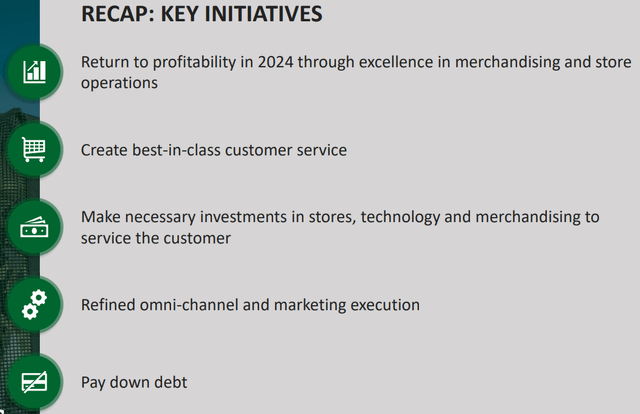
The operational focus is planned to improve profitability and cash flows. The shift aids Sportsman’s Warehouse’s new capital allocation plan of paying off debt, as the company’s current balance sheet is weak with $164.0 million in short-term borrowings. Improved cash flows are a very good sign for investors as the recent years’ growth investments have backfired, and although the operational initiatives’ effectiveness is yet to be seen, I believe that good profitability improvements should happen.
Updated Valuation: Risky Upside Exists In SPWH Stock
I updated my discounted cash flow model (DCF model) from the previous analysis. The model sees major changes – I previously estimated FY2024 to start to show improvements in revenues, but the recovery is now pushed back to FY2025 and FY2026 as growth of 5.0% and 3.5% respectively. Afterward, I only estimate growth of 2%, down slightly from previous estimates as the strategy has shifted from aggressive expansion to profitability preservation.
Due to continued margin weakness, I have also adjusted EBIT margin estimates down from an eventually achieved level of 4.6% into a conservative 2.7%. Future margins play a key part in the stock’s valuation, and I believe that the new estimate leaves a good margin of safety, although a surprise in either direction is still very possible. The company’s new capital allocation leaves space for improved cash flows, though, and I now estimate a very good conversion after a previously poor conversion estimate for the next couple of years.
With the mentioned estimates, the DCF model now estimates Sportsman’s Warehouse’s fair value at $5.04, around 57% above the stock price at the time of writing but -18% below my previous estimate of $6.14. There is clear upside potential in the stock, but investors should note that the stock is incredibly risky and volatile. High debt and continued pressured earnings are major risks, and the investment case could easily turn into a weak one.
DCF Model (Author’s Calculation)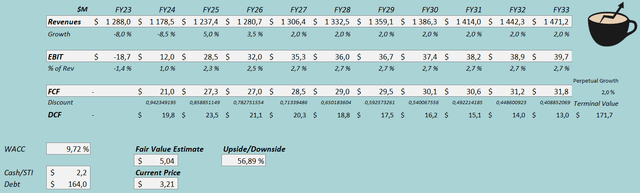
A weighted average cost of capital of 9.72% is used in the DCF model. The used WACC is derived from a capital asset pricing model:
CAPM (Author’s Calculation)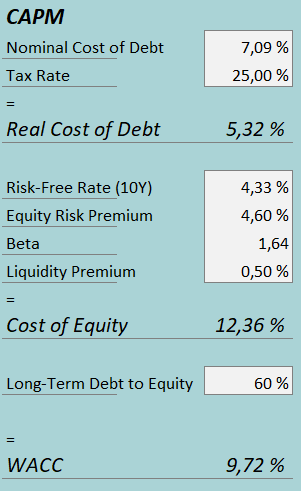
In Q1, Sportsman’s Warehouse had $2.9 million in interest expenses. With the company’s current amount of interest-bearing debt, Sportsman’s Warehouse’s annualized interest rate comes up to 7.09%. I now estimate a higher long-term debt-to-equity ratio of 60% instead of 30% as debt continues to be high and the company’s current cash flows make paying off the debt take time.
For the risk-free rate on the cost of equity side, I use the United States’ 10-year bond yield of 4.33%. The equity risk premium of 4.60% is Professor Aswath Damodaran’s latest estimate for the United States, updated on the 5th of January.
As earnings have declined further and debt continues to leverage shareholder returns, and as the macroeconomic pressure seems to push Sportsman’s Warehouse significantly, I raised my beta estimate by 30% from 1.26 into a more representative estimate of 1.64. Finally, I add a small liquidity premium of 0.5%, creating a cost of equity of 12.36% and a WACC of 9.72%, down from 10.27% previously.
Takeaway
Sportsman’s Warehouse’s weakness continued in Q1, with weak same-store sales also worsening earnings. The company expects macroeconomic pressures to persist in FY2024, with the year’s outlook showing continued revenue weakness. Still, gradual profitability improvements are now expected with the reaffirmed adjusted EBITDA outlook as Sportsman’s Warehouse’s inventory management starts so show progress. An eventual macroeconomic recovery and the company’s new strategy revolving around operational improvements instead of aggressive expansion should aid earnings over the medium term, although the scale of improvements is still unknown.
I believe that Sportsman’s Warehouse Holdings, Inc. stock now has a very good amount of upside, although the upside is highly risky and speculative – high debt and volatile earnings continue to cause high uncertainty. Due to the estimated upside, I keep my rating at Buy but suggest high caution with SPWH stock.
Credit: Source link