
marima-design/iStock via Getty Images
Note:
Seadrill Limited (NYSE:SDRL) has been covered by me previously, so investors should view this as an update to my earlier articles on the company.
Last month, leading offshore driller Seadrill Limited or “Seadrill” reported Q1/2024 results largely in line with expectations, with profitability boosted by a $16 million tax benefit:
Company Press Releases / Regulatory Filings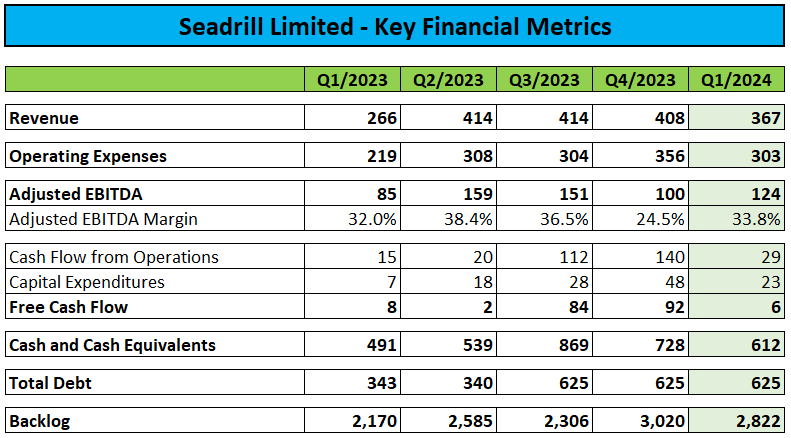
The company generated $6 million in free cash flow and ended the quarter with $612 million in cash and cash equivalents, down from $728 million at the end of last year solely as a result of Seadrill’s aggressive share repurchase approach.
Since September 2023, the company has repurchased 10.4 million common shares for aggregate consideration of $469 million, or 13.1% of Seadrill’s issued shares at the time of inception. The company continues to be active in the open market basis, with weekly buybacks currently running in a range of $5 million to $10 million.
In the press release, Seadrill reaffirmed full-year guidance of $1.47 to $1.52 billion in revenue, $400 to $450 million in Adjusted EBITDA, and $400 to $450 million in capital expenditures:
Company Press Release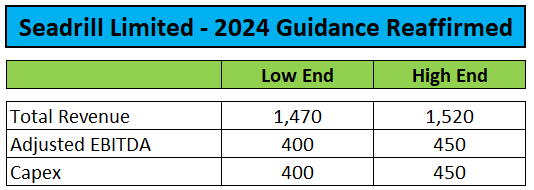
Please note that the company’s capital expenditure guidance includes maintenance expenses, which are recorded under operating activities in the cash flow statement.
Backlog was down by almost $200 million or 6.5% sequentially due to the recent lull in contracting activity.
However, the 6th generation drillship West Capella was awarded a short-term contract in South Korea at an industry-leading dayrate of $545,000.
In addition, the 7th generation drillship West Neptune secured a six-month contract extension in the U.S. Gulf of Mexico at a dayrate of $475,000.
On the conference call, management remained optimistic on industry prospects but warned of limited near-term visibility as customers continue to exhibit capex discipline (emphasis added by author):
The drilling industry’s recovery has been largely supply driven thus far. A continued up-swelling of demand across a broadening base supports further market development. The Golden Triangle remains the engine room of deepwater production, but incremental demand is increasingly distributed across geographies. It is not limited to a single epicenter, so the market will continue to grind higher. That said, we do not expect neat sequencing of supply and demand. One of the most challenging aspects of today’s market is timing.
E&P preference for growing cash flow over production can cloud market visibility. Aside from some unique instances of extensive term, most customers appear to be seeking contracts for a maximum of two to three year terms. Discrete delays around permitting, supply chain challenges, and even efficient operations can affect rig schedules and contracting, further contributing to momentary mismatches in supply and demand that may result in intense market activity within a relatively compressed window.
As an industry, offshore drillers simply do not have the same level of visibility we enjoyed in past cycles. So, whilst the dayrate environment proves, there’s nonetheless potential for volatility in rig utilization that may result in a delay or dislocation of demand. In this environment, our balance sheet strength and positioning provides solidity.
Not surprisingly, Seadrill’s near-term results will be impacted by these issues quite meaningfully, and even the much-anticipated earnings inflection next year might be more muted than previously expected by market participants.
Currently, 66% of available days for 2025 are contracted, but a number of rigs could be facing material idle time next year:
- The 6th generation semi-submersible rig West Phoenix will roll off contract in Norway in August with limited prospects for follow-on work and major capital needs for its 15-year special periodic survey and maintaining Norway continental shelf compliance. Consequently, Seadrill will require a long-term contract to justify the investment. Under a worst-case scenario, the rig might end up being cold-stacked.
- The company’s Sonadrill joint venture in Angola has three drillships (Quenguela, Libongos, West Gemini) rolling off contract in mid-2025. While management expects the rigs to secure new work in the region, some of these drillships might face idle time next year.
- The 6th generation semi-submersible rig Sevan Louisiana is sitting idle in the U.S. Gulf of Mexico.
- The 6th generation drillship West Capella is likely to sit idle between August and December 2024 and could face more idle time in 2025.
Given these issues, it seems prudent to reduce forward estimates for the company:
Author’s Estimates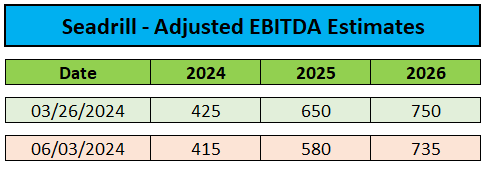
However, lower profitability expectations should be more than made up for by additional buybacks under Seadrill’s new $500 million share repurchase program, which has been announced concurrently to the sale of the company’s Qatar jackup fleet two weeks ago (emphasis added by author):
Seadrill Limited (…) today announced that it has entered into a definitive agreement to sell three jack-up rigs-the West Castor, the West Telesto and the West Tucana (the “Qatar Jack-Up Fleet”)-and its 50% equity interest in the joint venture that operates these rigs offshore Qatar to Seadrill’s joint venture partner Gulf Drilling International (“GDI”) for cash proceeds of $338 million (the “Transaction”).
The Transaction is subject to certain conditions, including approval or non-objection of the Qatar Financial Centre Authority and approval of the shareholders of GDI’s parent company, and is expected to close early in the third quarter of 2024.
“Our divestiture of the Qatar Jack-Up Fleet and exit from the joint venture are consistent with our ongoing efforts to strengthen and simplify our business and will allow us to focus on Seadrill’s core business: operating deepwater rigs across the Golden Triangle and similarly advantaged geographies,” remarked Simon Johnson, President and Chief Executive Officer. “We believe that our strengthened liquidity position upon completion of the jack-up sale, coupled with our conviction in the deepwater floater market outlook and Seadrill’s competitive positioning within it, supports the expansion of our share repurchase program.”
Concurrent with the announcement of the Transaction, Seadrill announced its Board of Directors has increased the Company’s aggregate share repurchase authorization, allowing the Company to repurchase up to an additional $500 million of its outstanding common shares over a two-year period commencing after the current share repurchase program is completed.
Pro-forma for the divestiture, the company’s cash balance calculates to $950 million, with no debt maturities until 2030. Pro-forma net cash stands at $325 million:
Company Press Releases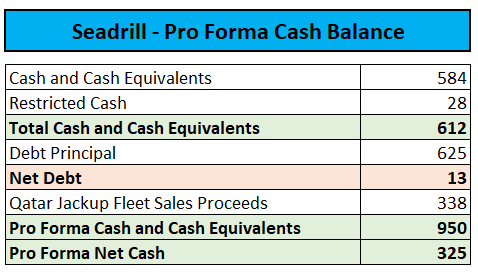
At the current buyback pace and prevailing share prices, Seadrill would be able to repurchase another 10.6 million shares, or approximately 15% of the company’s currently outstanding common stock until the end of Q2/2025.
Consequently, I am raising my price target which remains based on an assigned 2025 EV/Adjusted EBITDA multiple of 6x from $60 to $62.
Author’s Estimates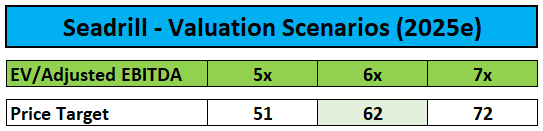
Please note that basing the company’s valuation on expectations for 2026 would result in a much higher price target for the shares:
Author’s Estimates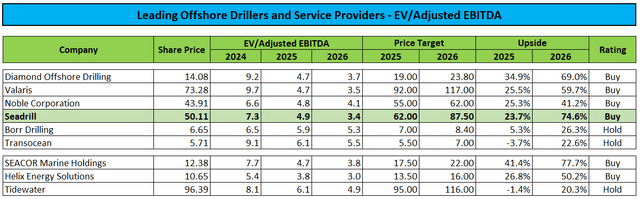
However, given persistent downward adjustments to expectations in recent quarters, a material level of uncertainty remains.
Bottom Line
Seadrill reported Q1/2024 results largely in line with expectations and reiterated full-year guidance.
Subsequent to quarter-end, the company sold its Qatar jackup fleet for $338 million in cash proceeds and concurrently announced a new up to $500 million share repurchase program.
On a less positive note, the company is facing more idle time on a number of floaters next year, which is likely to weigh on profitability.
However, the potential impact should be more than offset by accretion from additional share repurchases.
With a best-in-class balance sheet and strong focus on shareholder capital returns, Seadrill remains one of the most solid investments in the offshore drilling industry.
Consequently, I am reiterating my “Buy” rating with an increased price target of $62.
Credit: Source link