
Sundry Photography
Overview
The Dollar General Corporation (NYSE:DG) is where you can get all of your household essentials at a fraction of the cost. You can get everything ranging from personal care products, snacks, and even perishables such as eggs and milk. This also means that you sometimes get the same goods at a fraction of the quality as well, but that’s a trade-off that many people are willing to make during tough economic times. Tough economic times is precise how many Americans would describe the current financial situation here in the US as we experience slow wage growth, increases in the general cost of living, higher inflation than usual, and higher interest rates.
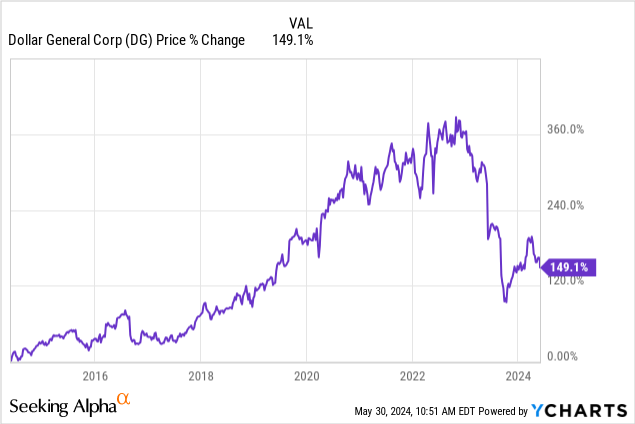
It’s no wonder we saw the price of DG rise to new heights while we simultaneously experienced some of the highest levels of inflation over the last decade. Dollar General recently reported their Q1 earnings and the results indicate that sales volume has been increasing. I feel that the company remains undervalued, and the market has not fully priced in the potential of DG yet. Therefore, entry here would be ideal as my dividend discount model indicates that there is a significant upside potential.
DG 2023 Annual Report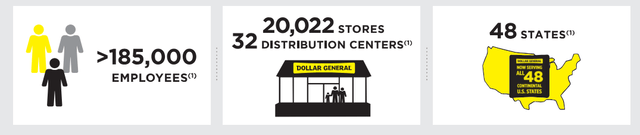
Dollar General has exposure throughout the United States, having locations in 48 states. There are over 185k employees throughout its over 20k stores and 32 distribution centers. With such a wide reach across the country, the business is getting exposed to each region of the country and capturing sales from all demographics. As the cost of living rises, I believe that DG’s wide exposure across the country should help them benefit from this consumer shift in spending to cheaper alternatives.
While DG may not be traditionally known as a dividend growth stock due to its low starting yield of 1.7%, the growth has been impressive. In my opinion, DG would make for a great long-term hold if you are an accumulator and do not need the income today. The company has increased their dividend payouts on a consistent basis for the last six-year period and I believe that a long-term position could yield significant growth to dividend income received as well as a nice boost to the yield on cost.
Financials – Q1 Earnings
DG reported their Q1 earnings this month and the results looked strong. For instance, earnings per share landed at $1.65, beating expectations by $0.07. Same store sales increased by 2.4% over the prior year’s Q1, while net sales increased by 6.1% to a total of $9.9B. These increases can be attributed to contributions from new store openings and increased customer volumes. Even though the average amount of customers was up, this was offset by the fact that the average transaction amount decreased.
A lot of the growth in sales were due to a rise in the consumables category, which I find very interesting. This is because I have been predicting for months that consumers would start to shy away from national branded food items, such as the products that are distributed by companies like General Mills (GIS) or Mondelez (MDLZ), if they were able to save a bit of money by purchasing the ‘store-brand’ or cheaper alternatives. Well, this increased traffic seems to indicate that the Dollar General also serves as a place where consumers can save a bit of money to buy the cheaper alternatives to their everyday products.
The Wall Street Journal recently put out a study that confirms my predictions. There have been a few different surveys also taken that concluded more shoppers would opt for the store brand or cheaper alternatives in an effort to save money. In fact, over 54% of shoppers now say they’ll choose the store-brands over expensive national brands. We can see from the graphic below that almost all categories show an increase in unit sales for the store-branded alternatives. I believe that Dollar General is also benefitting from this shift in the consumer mindset, as their products are cheaper and fall into more affordable price buckets.
Wall Street Journal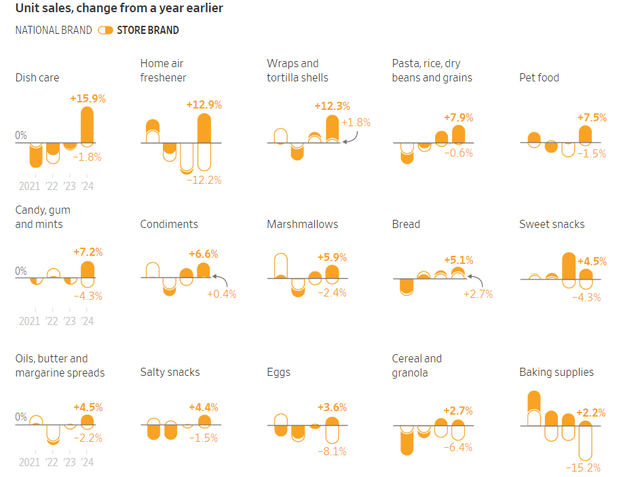
Looking at their 2023 annual report published this May, we can see that net sales have consistently increased over the last three years due to this increase in volume. However, net income has decreased down to $1.66B and the margins have been lowered from a combination of higher interest expenses and increases in SG&A expenses. If DG manages to find a way to efficiently cut down on these costs, I believe that we are primed to see a higher level of growth in share price. The interest expense rise is mostly a result of the higher interest rate environment we remain in, but this total is relatively small compared to the SG&A expenses.
DG 2023 Annual Report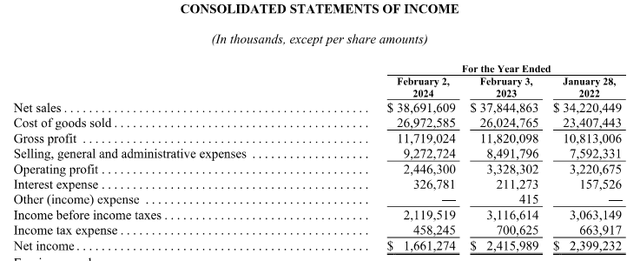
Despite these increased costs, DG has a solid liquidity profile. They currently have $537M in cash and cash equivalents on hand accessible to help them navigate any potential headwinds. Additionally, they are pulling in approximately $2.4B in cash from operations at the moment, which sits higher than the sector median of only $811M.
Management also provided some full-year guidance related to the outlook on performance. They forecast net sales growth to land in the range of 6% to 6.7% while same store sales increase between 2% – 2.7%. Capital expenditures for the full year will fall between $1.3B to $1.4B, which could encompass additional store openings. However, the company expects an estimated negative impact to EPS of approximately $0.50 per share due to a higher compensation expense.
Dividend Growth
Since the price has fallen 40% over the last 3-year period, the dividend yield higher than the norm. Over the last four-year period, the dividend has averaged a yield of 1% flat. We can see below that even as the share price has fallen, the dividend payout amount has increased by over 40% during the same time period. As of the latest declared quarterly dividend of $0.59 per share, the current dividend yield sits at 1.7%. Despite the fall in share price, the financials remain solid, and the dividend is well-covered. The current dividend payout ratio sits at 31.2%, which means there is a large enough cushion of safety and I see no threat to the current dividend payout amount.
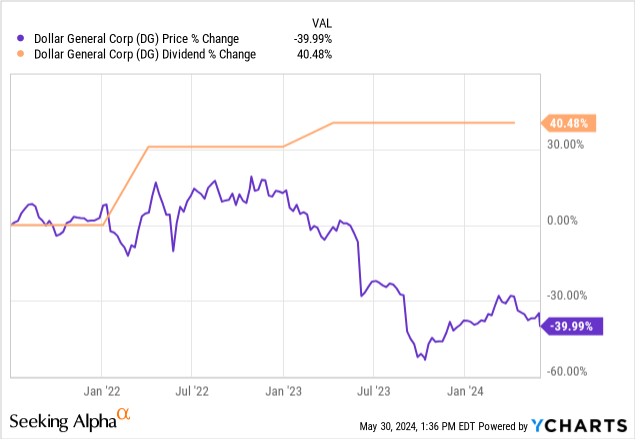
In addition to the dividend remaining safe, the growth here has been excellent. The dividend has managed to be increased at a CAGR (compound annual growth rate) greater than 14% over the last 5-year period. Even on a smaller time frame of three years, the dividend has increased at a CAGR of 16.31%. I believe that entry here would be most ideal, as the dividend growth has the potential to accelerate even more once the sales start to grow rapidly as inflation levels come down and interest rates start to get cut. As inflation cools, we may see the average transaction size increase and same store sales continue to grow at a faster rate.
Valuation
In terms of valuation, Seeking Alpha gives DG a D-rating, but I disagree with this assessment. For instance, the current price to earnings ratio of DG sits at 18.45x, undercutting the sector median price to earnings ratio of 20.09x. In addition, DG has averaged a P/E ratio of 21.06x over the last five-year period. Additionally, the price to book ratio sits at 4.53x, with is a significant premium over the sector median price to book of 2.4x. However, DG has consistently traded at an average premium price to book ratio of 7x over the last five years.
Additionally, the current average Wall St. price target for DG sits at $156.27 per share. This represents a potential upside of nearly 17% from the current price level. The highest price target sits at $190 per share and the lowest is at $118 per share. In order to get another source of reference, I decided to run a dividend discount calculation to get an estimated fair price.
I first started compiling the annual dividend payout amounts dating back to 2018. We can see that the dividend has steadily increased at a double-digit rate since then, averaging a CAGR of 14.32%. I also wanted to remain conservative, so I estimated that the dividend will increase by about 7.7% by the end of this year. Given the circumstances surrounding higher inflation, lower margins, and shifting consumer spend, I thought it would be more realistic to have a lower raise this year.
Author Created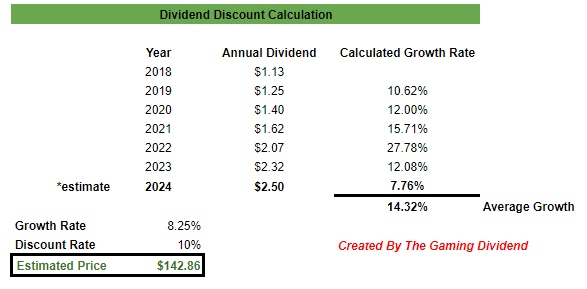
Management forecasts sales growth to land between 6% and 6.7% However, using the last five-year time period as a reference, year over year revenue has grown at a 9.6% rate while year over year EBITDA growth averaged 9.87%. I thought that it would be fair to use an estimated growth rate of 8.25% as it lands right in the middle of these growth rates and as volumes and same store sales increase, this can be achieved. With these inputs in mind, I get an estimated fair price of $142.86 per share. This represents a potential upside of 7.6% from the current price level. While this comes in lower than the average Wall St. price target, I believe it to be a more realistic outlook given the macroeconomic environment.
Risk
The recent price decrease can be attributed to a mix of factors. One of them being a decrease in gross profit, down to 30.2% of sales. This decrease can be attributed to increased shrink and inventory markdowns. Increased ‘shrink’ refers to the amount of inventory that is lost due to mostly theft, faulty, or damage. Since there is a greater amount of inventory that is being lost to these things, it directly translates to a lower amount of inventory that is available to be sold.
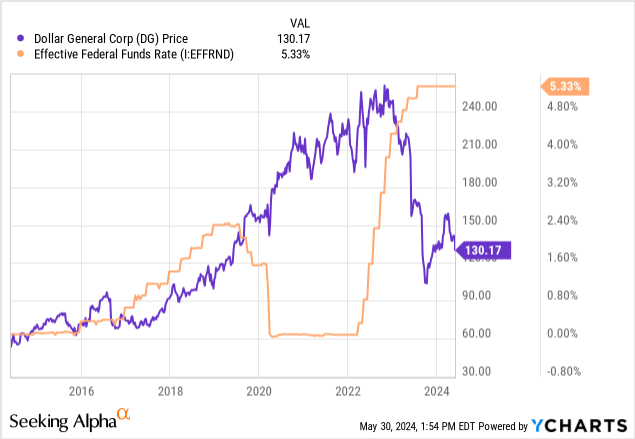
Additionally, high-interest rates continue to weigh down on profitability because of increased interest expenses. It’s no coincidence that the price momentum of DG shifted to the negative as interest rates reached their highest levels ever over the last decade. As rates rise, this increases the cost of maintaining debt and can chew into profit margin and increase costs to fund operations, fuel capital expenditures, open additional stores, and invest into new marketing initiatives.
If we remain in a higher interest rate environment for longer, we may see the price of DG continue to trade downward until rate cuts become a possibility. With inflation remaining higher than anticipated, the job market remaining strong, upcoming elections, and ongoing global conflict, I believe that rate cuts will likely be delayed until the end of the year. Other sources also share this sentiment and expect rates to remain unchanged throughout the summer of this year.
Takeaway
In conclusion, Dollar General continues to benefit from the consumer shift to cheaper branded alternatives. Even though the price has fallen over the last three-year period, this is more due to external factors rather than any fundamental issues of the company. For example, the combination of higher inflation, high-interest rates, and increase shrink has caused a loss of value. However, valuation indicates a fair estimated price of over $142 per share, indicating a modest upside from here while using conservative growth estimates. Even though the starting dividend is low, I believe that now would be an ideal time to accumulate so that long-term holders can benefit from the strong dividend growth.
Credit: Source link