RUNSTUDIO/DigitalVision via Getty Images
MFA Financial (NYSE:MFA) is a mortgage REIT that has a couple of interesting things going for it right now. Its dividend yield trades at a high 13%, and this also comes with a discount to book value.
MFA Price/Book 5Y History (Seeking Alpha)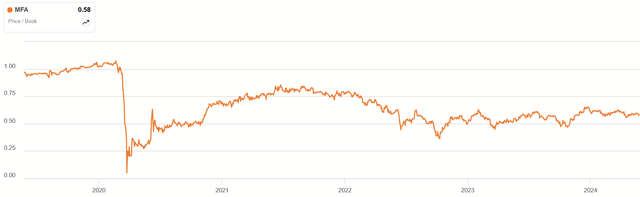
At 0.58, this looks like a large discount. During this period as well, the company has made some changes to its strategy to avoid some of the pitfalls of the past. After examining where they are in this process, I ultimately concluded that MFA is a Hold until it’s made more progress in its transformation.
Financial History
When looking at a REIT’s financial results, one of its biggest tests is how well it has maintained its dividend per share. In the last few years, we can see that MFA struggled to maintain it.
Seeking Alpha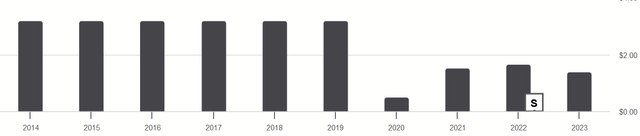
After 2020 and the onset of COVID, the dividend was reduced and hasn’t returned to previous levels. This is due, in large part, to how the pressures of the pandemic caused them to reduce the size of their balance sheet.
Author’s display of 10K data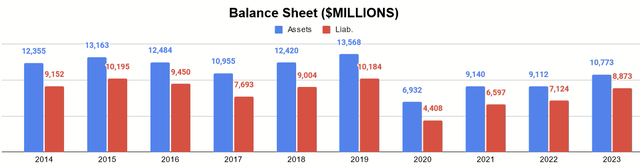
2020 saw the balance sheet fall by more than half. This was not uncommon for mREITs at the time, as the COVID crash created liquidity pinches for many of them that utilize mark-to-market financing and thus experienced margin calls. In Q1 2020 earnings, CEO Craig Knutson said:
It was clear to us in late March that our situation was not due to bad assets, but a fragile funding, and the path forward would require more durable forms of financing. We also recognize that term financing margin holiday and/or non-mark-to-market financing would necessarily require higher haircuts and therefore more capital.
So while they updated the financing situation, that was not the only change that occurred. In 2021, they acquired Lima One, which originates Business Purpose Loans (“BPLs”) to real estate investors, and these loans are a growing part of their portfolio. Management continued their strategy of evolving their leverage into 2023, noting in the 2023 Form 10K (pg. 41):
…we believe our commitment to prudent risk management and hedging and prioritization of non-mark-to-market financing allowed us to add $3.4 billion of our target assets at increasingly attractive yields. These additions included over $2.1 billion of funded originations of business purpose loans and draws on existing Transitional loans at Lima One, approximately $880 million of Non-QM loans, and approximately $460 million of Agency MBS. Reflecting the impact of our strategy, for the year ended December 31, 2023, the yield on our average interest-earning assets increased by nearly 100 basis points, while our effective cost of funds increased by nearly 40 basis points from the year ended December 31, 2022.
So the company is evolving its means of financing still, and it’s worth considering where what kind of business it is currently.
Business Model
MFA is primarily in the business of originating and acquiring BPLs (through Lima) and non-qualified mortgages (non-QM). The rest of its portfolio contains other types of mortgage assets, largely non-performing whole loans that are bought at a discount.
Q1 2024 Company Presentation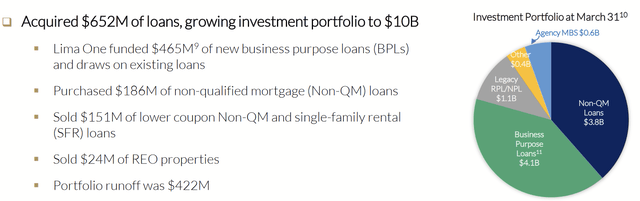
They have steadily been rotating their assets into these concentrations in BPLs and non-QM loans.
Cropped Table of Distributable Earnings (2023 Form 10K)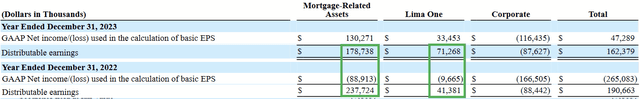
The Lima assets, meanwhile, have had a rising contribution to the distributable earnings (earning available for distribution as a dividend).
Q1 2024 Company Presentation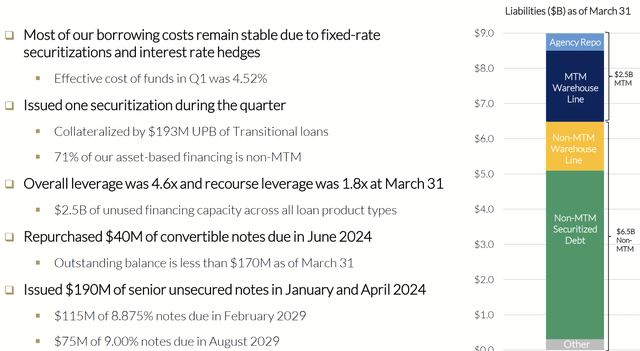
About 28% of their liabilities, meanwhile, are these mark-to-market financing sources.
Q1 2024 Company Presentation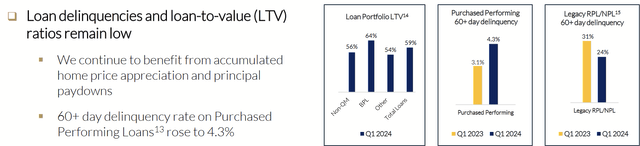
Importantly, though, while delinquencies are up on these loans from Q1 2023, they remain relatively low at 4.3%.
Q1 2024 Company Presentation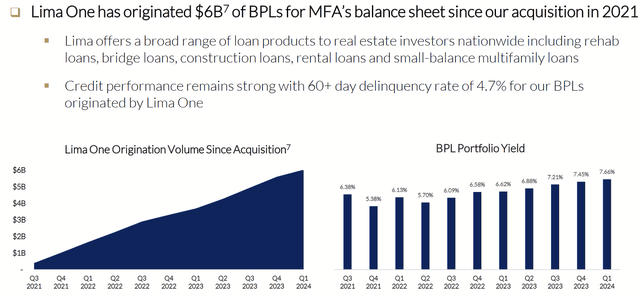
The Lima One loans, meanwhile, have enjoyed a rising yield, low DQ rates, and a steady flow of new originations.
Q1 2024 Company Presentation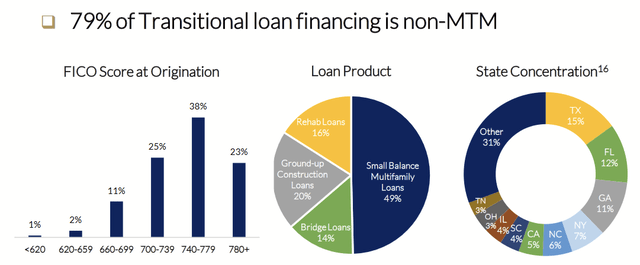
The Lima One loans are largely multifamily, with about half in Texas, Florida, George, New York, and North Carolina.
Q1 2024 Company Presentation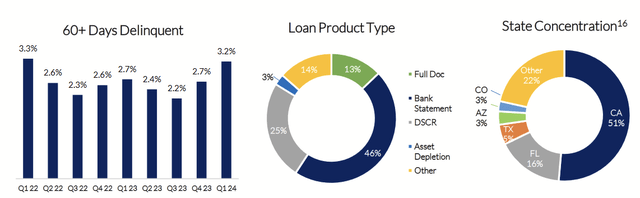
The non-QM loans, meanwhile, are heavily concentrated in California and, to a lesser extent, Florida.
Future Outlook
Overall, I see the situation as improving for MFA as they continue to transition out of their old strategy and focus on loan origination itself through Lima One, which I believe comes with some skin in the game that not all mREITs have. There are two concerns I want to highlight, though.
Interest Spreads
While the coupons on their loans are high, so too are the coupons on their new financing. In Q1 2024 earnings, they mentioned that their newest bonds in April yielded 9%. Regarding asset acquisition, Knutson said:
In some cases, it can make sense to call a deal and re-lever the underlying loans in a new securitization. Even if the cost of debt is marginally higher than in an existing deal, a call and re-lever could unlock significant additional liquidity, which we can redeploy at attractive ROEs. These call rights provide an often underappreciated option that we have to optimize our liability framework in the years ahead.
While he may have a point here, this is something that creates additional squeeze on distributable earnings.
Q1 2024 Company Presentation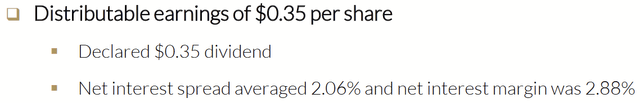
If interest rates do not decline at a fast enough rate, I worry that these could create unnecessarily losses that require a cut in the quarterly dividend, which right now is equal to DE.
Missing Out on Buybacks
Management also announced that the Board had approved a $200M share repurchase program, which is currently about a fifth of the market cap. Knutson clarified:
I’ll also point out that we simultaneously refreshed our share repurchase authorization, and I would characterize both actions…as administrative in nature.
So this isn’t guiding for buybacks at a really good price. As of Q1, tangible book value per share is $17.79. With a dividend yielding 13%, that’s a great return on capital if repurchased.
Q1 2024 Company Presentation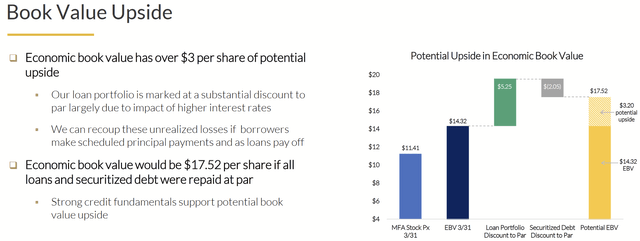
In the slide above, even management seems to believe there is some underappreciated value on its balance sheet. Yet, considering the tight cash flow situation with DE and the continued shift in their financing, it seems to me that management is not as comfortable as it could be. There are companies using market pessimism to buy back their shares right now, and I see that as a key indicator of a company’s financial strength that they can make some space for that.
Conclusion
A fair value for MFA on the high end reasonably stands at the TBV, $17.79. Over time, with the company’s active role in origination and opportunities to re-lever to reduce interest expense, we could even see that and the dividend improve.
In the meantime, the discount to book and current price under $11 exists for a reason. The shares are likely fairly valued in the event that interest rates do not change favorably for MFA, and in case the higher rates persist and lead to more DQs going forward. While this may not eliminate the dividend, it does mean the yield on cost may not prove to be the full 13% over the next few years.
I think MFA is close to being an attractive investment but needs more time to navigate the present situation. Long-term investors will probably benefit from waiting to see them shed the remaining vestiges of MTM financing and achieving a lower payout ratio of DE. In the meantime, MFA isn’t the riskiest investment with the reforms it’s made and is at least an adequate Hold.
Credit: Source link