
Image source, Nathan Wilkins
- Author, Natalie Sherman
- Role, Business reporter, BBC News
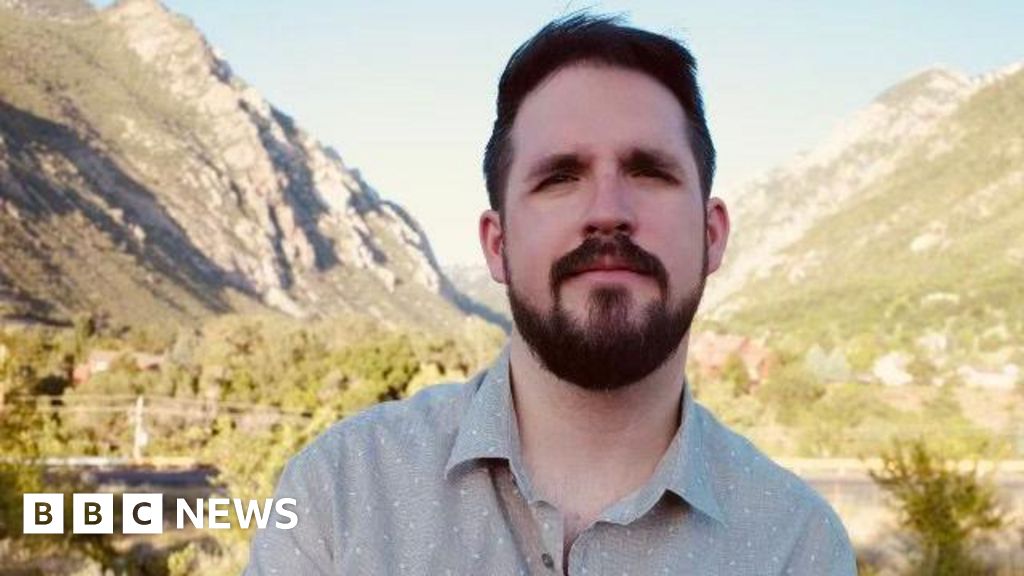
When Nathan Wilkins moved back in with his mother and sister in 2019, he hoped it would help him save money to buy a home.
But in the years since, the US housing market has been transformed by rising rents, surging home prices, and a massive jump in mortgage rates, making homeownership seem like an ever more impossible.
He and his sister are making more money than ever, the 32-year-old insurance adjuster from Utah says. But shelling out $2,500 (£1,960) a month in rent doesn’t leave much left over.
“It’s like I’m playing a game that you can’t win,” he says. “The fact that we’re being priced out just makes me want to throw up.”
Such frustrations are spreading, fuelling dissatisfaction and contributing to the widespread pessimism about the US economy that is looming over the country’s upcoming election.
The median home sale price in the US has jumped by nearly 30% since the end of 2019, hitting $420,000 this spring.
And that’s not factoring in the added costs from higher interest rates, which now stand at roughly 7% for the 30-year, fixed-rate mortgage that is typical in the US, up from about 3% in 2020.
Homebuyers today need an annual income of more than $100,000 – well above the country’s household median of about $75,000 – to comfortably afford a home in most places in the US, research firms such as Zillow and Bankrate say, and face monthly payments that have roughly doubled in just four years.
Image source, Getty Images
“It makes me cry a bit,” says Megan Holter, who started looking to buy in Austin, Texas, back in 2019, when banks were offering her a 30-year fixed rate of about 4.75%.
She halted her search when the pandemic hit, priced out by the surging cost of building materials and homes.
She and her wife finally bought a home this year, but only after swallowing a 6.625% rate – and moving 1,200 miles north to Columbus, Ohio, a spot selected from a spreadsheet she created of cities with lower costs.
“Housing affordability was the number one thing that we’ve been considering for five years,” says the 30-year-old, who also switched jobs from the public sector to the private sector to make homebuying happen.
“We have moved mountains to make it possible.
“I’m just eternally grateful that we can afford it. I know a lot of other people cannot,” she adds.
Just 40.1% of renters expect to ever own a home one day, according to the New York Federal Reserve, the smallest share since the bank started asking renters the question in 2014.
Even homeowners, whose long-term mortgages shield them from immediate financial impact and who benefit from rising property values, tell pollsters that the changes in the market are a source of concern – as they push up property taxes and insurance costs, while making moving a less affordable prospect.
A recent Harris poll found more than 70% of Americans believe the market is only going to get worse.
Image source, Getty Images
The issue is feeding into wider worries about rising living costs, which have jumped 20% since 2021.
It is among the biggest challenges facing President Joe Biden, whose time in office has coincided with the housing market’s transformation and who receives dismal ratings for his handling of the economy in national polls.
Challenger Donald Trump, who fares better, has sought to blame Mr Biden for inflation, and though he does not typically call out housing specifically, he regularly spotlights “skyrocketing” interest rates to argue that the economy is heading in the wrong direction.
“Inflation has been a political noose for Biden in recent years,” says Brian Connolly, professor of business law at the University of Michigan’s Ross School of Business, whose work focuses on housing issues. “Housing costs are another place where people are experiencing this financial squeeze.”
In recent months, the White House has tried to address concerns about affordability head on, offering proposals such as rules to limit closing costs and a $10,000 tax credit for first time homebuyers.
It marks a shift in tone, after years of focusing on the economy’s strengths, including low unemployment. But with few immediate levers for Mr Biden to pull, it’s not clear the efforts are resonating.
His support has especially eroded among younger people – whose record turnout in 2020 helped put him in office. Voters in this demographic are least likely to own homes and most likely to see housing affordability as a top concern.
“I don’t see any platform that purposely looks out for somebody like first-time homebuyers, wanting to ease their pain,” says Braiden Dogherty, a 30-year-old from Florida who works in manufacturing and has been checking for houses daily for three years.
Despite a $50,000 inheritance, no debt, and decent jobs, he and his wife can’t find an affordable two-bedroom near their families in the Orlando area.
He says the problem of housing costs is too big to blame on any one politician or party, but the seeming lack of solutions has contributed to his wider political disillusionment. He is uncertain how he will vote in November.
“I’m fed up,” he says. “Housing is part of it.”
The growing outcry has raised pressure on the US central bank to cut interest rates to bring relief, a move Federal Reserve chairman Jerome Powell has said is likely at some point.
But expectations that a cut would happen early this year, helping to improve the country’s mood, have been steadily pushed back. This reflects concerns that progress in lowering inflation – which was hovering at 3.4% in April, still well above the bank’s 2% target – could be stalling.
Image source, Julia Mokhnatkiina (JM Photos Inc)
Instead, since January mortgage rates have mostly moved higher.
Mimi Than, a 29-year-old who recently bought a three-bedroom condo in the Boston, Massachusetts area, says she is facing roughly $200 more in monthly costs than when she and her husband were pre-approved for a loan in March.
They did not lock in the rate then, unaware borrowing costs might shift significantly. When they returned to their lender in April after making an offer, the interest rate they were offered was 6.9%, up from 6.5%.
She’s hoping that they will drop back later this year, allowing them to refinance.
“I’m obsessively checking the rates,” she says.
Many analysts maintain it is only a matter of time until inflation slows down, clearing the way for a cut.
They note reports by private firms that show rental increases – which play a big role in calculations of US inflation – cooling from the torrid pace of the pandemic amid a jump in apartment supply.
With wages growing, an increase in new homes under construction and rents and home prices rising more slowly, Orphe Divounguy, senior economist at the housing site Zillow, says he sees affordability challenges easing as well – albeit not in time for November’s election.
Image source, Getty Images
“It’s working itself out,” he says. “We still have a long way to go, of course, but we’re seeing some improvement and I think we’re going to see more improvement.”
But there’s a gloomier view.
With more people priced out of homeownership, rental rates may prove more resilient than expected, keeping inflation elevated.
And if mortgage rates do not drop significantly, the step-change in borrowing costs may act as a long-term constraint on supply, as builders pull back and homeowners who secured mortgages when rates were lower forego moving.
Braiden, from Florida, sees no easy fix from the Fed, which he fears helped shape the current crisis by letting rates stay unusually low in the decade after the 2008 financial crisis.
“No matter what happens – whether they raise, lower or hold them – I feel as though the next decade is probably just going to be difficult no matter what for most people,” he says.
Credit: Source link