The Good Brigade
Investment Thesis
Pessimism surrounding Chimera Investment (NYSE:CIM) has brought the stock to a 5-year low, at around $12 per share at the time of this writing. As a mREIT, this isn’t too unusual, as a lot of mortgage REITs trade at cheap valuations due to rising rates in the past that have crushed book values. However, at this price the discount to book value is way too wide, and I think future dividend cuts are unlikely. I think book values and dividends have stabilized, which should support the stock price from here on out. Thus, the bottom seems to be in, and I think Chimera Investment is way too cheap to pass up on for investors.
Company Overview
According to the annual report, the company is “primarily engaged in the business of investing directly or having a beneficial interest in a diversified portfolio of mortgage assets, including residential mortgage loans, Agency RMBS, Non-Agency RMBS, Agency CMBS, business purpose and investor loans, and other real estate-related assets”.
Like any mREIT, they invest in mortgages assets, MBS, and other kinds of mortgage loans by taking borrowed money and earning the spread between the interest they receive from mortgages and the interest they pay on their debts. They then can use leverage to amplify these returns, and as of this writing, the leverage ratio is 3.7x.
As of 2023, the annual report shows a shift in strategy to primarily residential loans, “During 2023, we focused our investment activities primarily on acquiring and securitizing pools of residential mortgage loans…” This strategy has continued into 2024, and “in addition to our securitization and business purpose loan activities, we will explore opportunities to increase our Agency MBS portfolio”. It looks like management has become a little more conservative in focusing on residential loans that are agency backed, which shows they are adjusting their risk tolerance in the current market environment.
I view Chimera Investment as a typical mREIT that has a strong residential loan portfolio, most of which were originated prior to 2008. This is significant to me because I think those loans are shown to perform well and are reliable sources of interest income judging from the long track record. With falling delinquency rates, and a stable weighted average coupon on their loan portfolio, it looks to me that this mREIT has stabilized out and shouldn’t see any more declines in fundamental performance going forward.
Presentation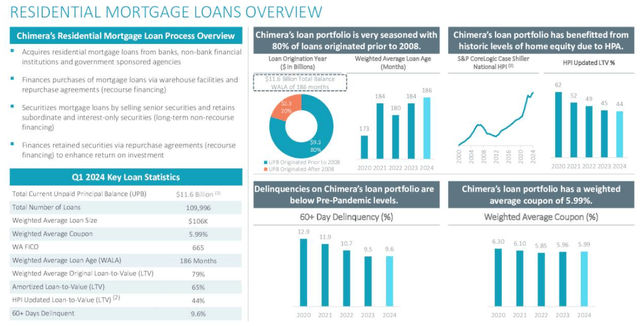
Q1 Earnings Review
Chimera Investment reported Q1 2024 earnings on May 9, 2024. The results were somewhat mixed in my view, but the stock price still seems to be underpricing the fundamental performance of the business. According to the press release:
- 1ST QUARTER GAAP NET INCOME OF $0.45 PER DILUTED COMMON SHARE
- 1ST QUARTER EARNINGS AVAILABLE FOR DISTRIBUTION(1) OF $0.12 PER DILUTED COMMON SHARE
- GAAP BOOK VALUE OF $7.11 PER COMMON SHARE
Note that since the 1 for 3 reverse split, some of these numbers are off, so investors should multiply everything by 3 here to account for the split. I see the fundamentals stabilizing here, and expect it to continue as rates seem to have stopped being hiked, and new home sales continue to hold up in the US. Total shareholder’s equity increased from $2.56 billion to $2.65 billion quarter over quarter, demonstrating some resilience in the book value as the assets continue to hold up their value. Management has been trying to grow their loan portfolio by acquiring new loans and securitize them into attractive vehicles for investors.
Securitization continues to be a highlight for 2024 in my opinion and is a major strategic emphasis for the company. According to the annual report:
During 2024, we expect to continue acquiring and securitizing mortgage loans as well as calling our existing securitizations depending on market conditions. When we securitize mortgage loans, we typically retain the most subordinate classes of securities, which means we are the first-loss security holder.
I view the securitization of residential mortgage loans as attractive as it preserves liquidity and helps management shift capital from low rates of return to high rates of return flexibly. Basically, by securitizing these mortgages into MBS, the company can “finance the acquisition of residential mortgage loans” very cheaply in my view. I think this explains why the leverage ratio is rather low at 3.7x because they can use securitization to their advantage to increase the flexibility of how they borrow money.
Website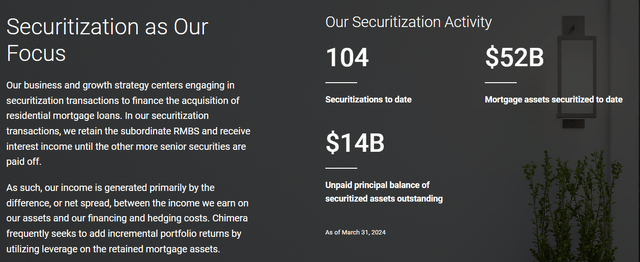
Overall, I think the quarter demonstrates a stabilizing of book value, dividends, and earnings. I view the loan portfolio as attractive and expect the dividends to continue to roll out, given the track record of these high performing loans. Chimera’s focus on securitization appears to be advantageous in this environment, as they can maintain a relatively low leverage profile while still earnings high ROEs. The slight uptick in book value and market value of assets this quarter leads me to believe the recovery is beginning to happen, as interest rates seem to have stabilized around 5% for now.
Presentation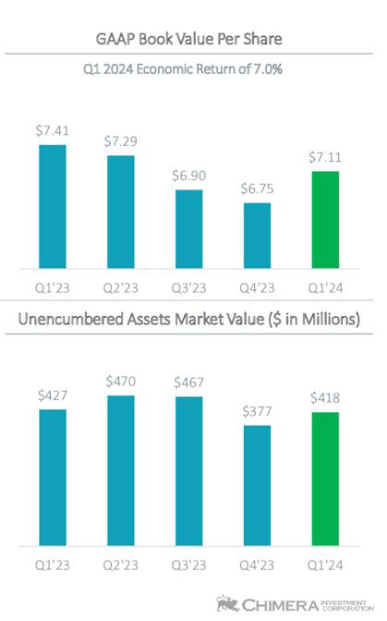
Resilient Performance Despite Macro Headwinds
Despite delayed rate cuts and a somewhat sluggish housing market, I’m actually quite bullish on mREITs as a whole, and believe Chimera has been very resilient to these headwinds. The Federal Reserve has delayed cutting rates for some time, but there is still some chance that they will cut rates, which should drive book value higher for Chimera. According to the Fed, they still want to wait for inflation to get back on track before cutting rates.
My view is that investors don’t need to rely on a rate cut for the thesis to work. Even without rate cuts, the book value and earnings continue to perform well currently, so the fundamentals should drive the stock price regardless of what the Fed does. Ultimately, it looks to me that the company has successfully hedged itself for any interest rate movement as they have said “current hedges are positioned to deal with an uncertain rate environment” in their presentation. With $2 billion of 1-year interest rate swaps, they have well covered their liabilities, so rate cuts aren’t really necessary for the company to continue to widen the profit spread in my view.
Housing continues to bring in mixed results in my view, with existing home sales falling but new homes sales rising. According to CNN:
Meanwhile, sales of existing homes, which make up the vast majority of the housing market, fell 4.3% in March to a seasonally adjusted annual rate of 4.19 million, the sharpest drop in more than a year, the National Association of Realtors reported last week.
I think people are still reluctant to purchase homes because they are unwilling to give up the cheap mortgage rates they’ve locked in at around 2-3%. This could pose a problem to mREITs in general, as it may be hard to find attractive mortgages to buy on the market. Still, Chimera’s focus on securitizing existing residential mortgages gives them a source of liquidity while they prepare for a potential rebound in the housing market. Even with headwinds from the housing market, I think Chimera can still manage their loans and securitizations to weather the storm and keep their earnings intact.
Valuation – $15 Fair Value
I think the stock is significantly undervalued based on book value, and as of this time of writing adjusted for the split book value is $32 per share. If I apply a 50% discount due to potential dividend declines, a sluggish housing market, delayed rate cuts, the stock is in my view still very cheap. So, I think $15 per share fair value is rather fair, as it already accounts for the risks to a mREIT like Chimera.
The stock also trades at 10x FWD earnings non-GAAP, which is close to the sector median. With over a 10% yield, I think the dividends are well covered by earnings and a future dividend cut is unlikely. The bottom is in, in my opinion, and the fundamentals seem to have stabilized. New investment opportunities in mortgages and securitizations should allow the assets to grow from here, so I expect book value to grow steadily.
Liabilities continue to be managed properly, and according to the earnings call transcript:
On the liability side of the balance sheet, we continue to reduce some of our higher cost repo borrowings. We believe the actions taken this quarter on both sides of the balance sheet will benefit our interest — net interest income.
So I see an increase in net assets driven by a reduction in some of the higher cost liabilities to be a positive for valuation as net interest income can continue to grow from here. Then, investors can see the dividend is rather safe in my view and the stock should hold more perceived value in the future. All mREITs tend to be cheap, but I haven’t seen many trade at a whopping 0.4x book value. With the sector median at 1.14x, this margin of safety is impressive and should protect shareholders, assuming book value holds up.
Risks
Like most mREITs, the company faces prepayment risk, interest rate risk, credit risk, and liquidity risks. All mREITs sort of rhyme when it comes to risk, as they are heavily influenced by interest rates, so any hikes could threaten further book value declines. A lot of mortgages can be prepaid before maturity if rates come down, so the company will get a lot of cash flow but struggle to reinvest it at high rates of return. Sometimes borrowers can default and can cause asset impairments to the loan portfolio. All in all, mREITs have similar risks when investing in fixed income assets like mortgages and MBS.
Dividends can be cut if earnings don’t sustain themselves, so investors should note the EAD Chimera earns is a reflection of how well their loans perform. Past dividend performance is no guarantee for future dividend performance, so investors may want to be careful about earnings, as they may not sustain the dividend going forward.
Although leverage is relatively low in my opinion, Chimera must be careful in managing their liabilities and making sure liquidity is strong to meet interest payments on their debts. Hedges may not protect investors from extreme interest rate movements, as most of their swaps are 1-year, which may not protect them completely in the long term.
Buy Chimera Investment
The discount to book value is too big in my view and should close as investors see the business perform well under tough macroeconomic conditions. The focus on securitization is attractive in my view because it allows for management to finance purchases cheaply, earning high ROEs with relatively low leverage. The dividend seems to be well covered by earnings at this moment, so I don’t expect any more future cuts to happen. All in all, another solid mREIT that investors should look into buying in my view.
Credit: Source link