
































krblokhin
The Materials sector has performed well on an absolute basis for much of the year, but relative to the S&P 500 (SPY), the Materials Select Sector SPDR Fund ETF (XLB) has given back some of its alpha that was garnered from early February through the finish of the first quarter. Despite strength in many resource commodities, including base and precious metals, gasses, and chemicals have been less exciting.
Still, I am upgrading Linde plc (NASDAQ:LIN) to a buy. Back in my early days with Seeking Alpha, I had a largely technical sell call on the large cap, and shares indeed pulled back to support I noted in August 2022. But let’s go through more fundamental data to see what might lie ahead for this UK-based ADR.
Materials Sector Sluggish vs. the S&P 500
StockCharts.com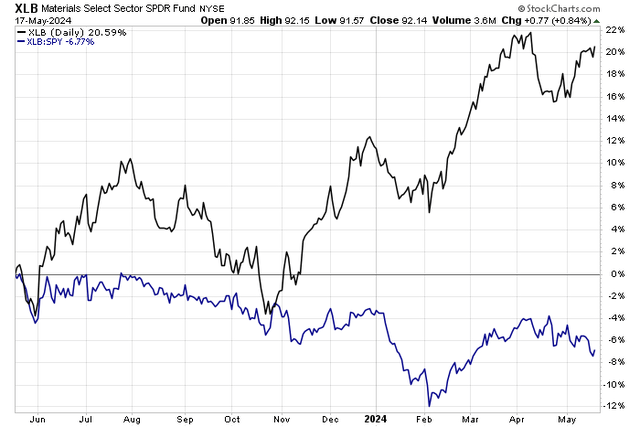
According to Bank of America Global Research, Linde is the largest industrial gas company in the world, with sales nearing $30bn following the merger of Praxair and Linde. It produces and distributes atmospheric and process gases, high-performance surface coatings, and engineering solutions. Linde products, services, and technologies bring productivity and environmental benefits to a wide variety of industries, including aerospace, chemicals, food and beverage, electronics, energy, healthcare, manufacturing, metals, and others.
Earlier this month, Linde reported impressive Q1 results. Non-GAAP EPS of $3.75 beat the consensus estimate by $0.08 while revenue of $8.1 billion was 1% lower than year-ago levels. But operating profit boasted a 6% increase helped by a large 200-basis-point jump in its operating profit margin, as has been the trend since the Praxair merger.
The management team now sees FY 2024 adjusted EPS in the $15.30-$15.60 range, which would be an 8-10% increase compared to FY 2023. The healthy start to the year was driven by Linde’s ability to raise prices along with productivity gains, helping to offset slightly softer volumes.
2024 Guidance
Linde IR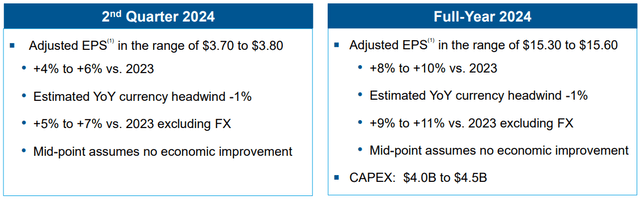
Shares fell after the Q1 report as the guide was seen as slightly light. A lower capex outlook sent a bearish message to the street. Still, Linde’s sale-of-gas backlog was high at $4.9 billion as of the end of last quarter. The firm has raised its dividend by 9% this year and continues to repurchase shares. Key risks to watch out for are a stronger US Dollar, weaker global GDP growth, and a decline in domestic industrial activity.
Linde: Rising Operating Margins, Big Gas Backlog
BofA Global Research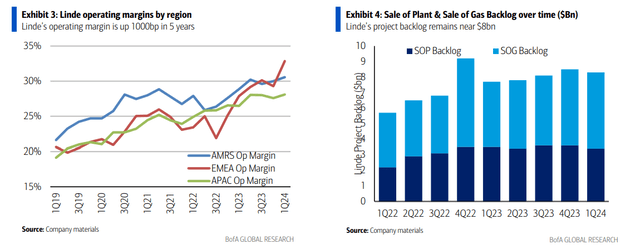
On valuation, analysts at BofA see earnings increasing at a steady 10% rate over the next few years with operating EPS potentially topping $19 by 2026. The Seeking Alpha consensus forecast is about on par with what BofA projects. The company’s top line is seen rising at a low- to mid-single-digit clip in the next two years while significant dividend growth is expected. Free cash flow is decent, but an FCF yield under 3% is not indicative of a value stock.
Linde: Earnings, Valuation, Dividend Yield, Free Cash Flow Forecasts
BofA Global Research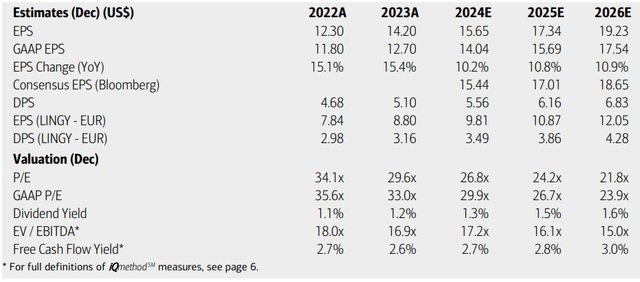
With high and sustained EPS growth over the years ahead, a valuation premium is warranted. If we assume the next 12-month non-GAAP EPS of $16.25 and apply a 28 multiple, then shares should trade near $455. While that is not far from the current price, I like how Linde has grown its margins in all regions and has demonstrated elevated pricing power.
Linde: High Valuation Multiples, But High EPS Growth
Seeking Alpha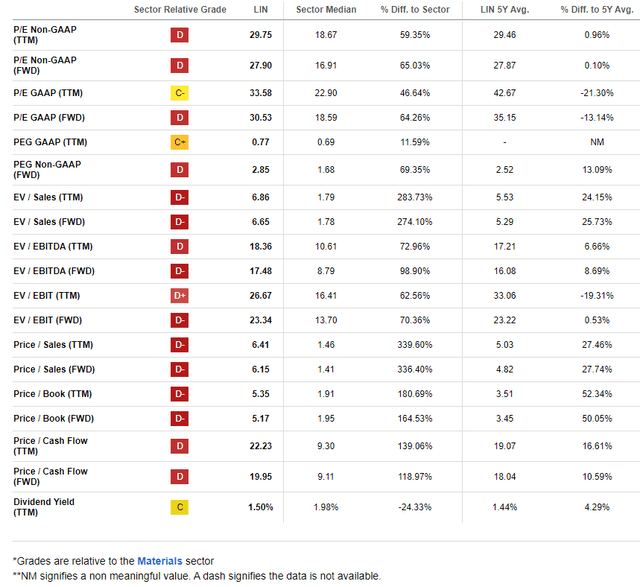
Compared to its peers, Linde sports a high set of valuation multiples, but I expect that to continue as the current operating P/E has held about steady in the past five years. The company’s growth trajectory is healthy, but merely about in line with its competitors.
Where the Materials stock stands out is with its profitability metrics, though the sell side has turned less upbeat about Linde in the last 90 days. Finally, share-price momentum has also become more mixed after a significant pullback in the stock this quarter.
Competitor Analysis
Seeking Alpha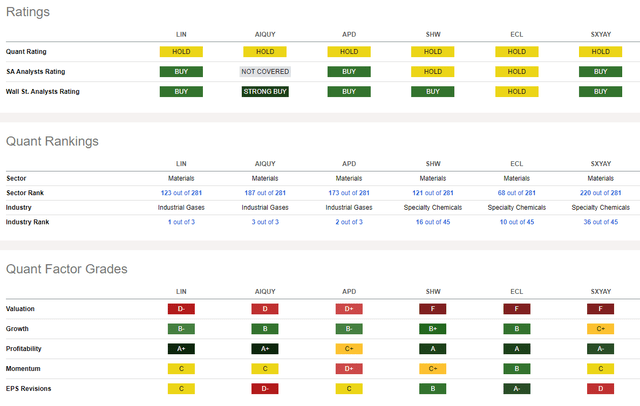
Looking ahead, corporate event data provided by Wall Street Horizon show an unconfirmed Q2 2024 earnings date of Thursday, August 1 BMO. Before that, the management team is expected to present at a pair of upcoming conferences next week and shares trade ex a $1.39 dividend on Tuesday, June 4. Finally, be on the lookout for potential volatility in late July when Linde holds its annual shareholder meeting.
Corporate Event Risk Calendar
Wall Street Horizon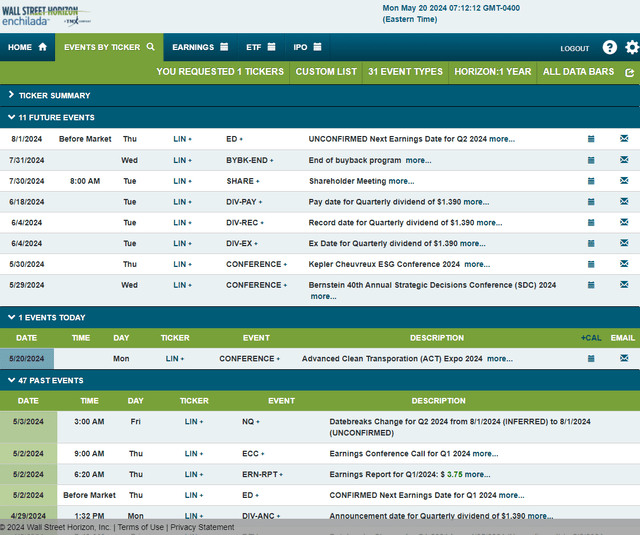
The Technical Take
With shares a bit on the cheap side with fundamental strength, LIN’s chart is constructive. Notice in the graph below that shares are in a pronounced uptrend going back to the end of the third quarter of 2022. A series of higher highs and higher lows is encouraging, but the stock got ahead of itself back in March when the RSI momentum reading approached 90. A decline to trend line support found confluence with the rising 200-day moving average, so long here with a stop under $413 would make sense for active investors.
I am mildly concerned that the 50-day moving average has turned downward in its slope. The bulls will also have to get the stock through the earnings-related gap around the $450 mark. Overall, shares remain in a clear uptrend after reaching nosebleed momentum levels in mid-March. The 10% pullback was healthy, in my view, and higher prices into the second half of the year is my expectation.
LIN: Solid Long-Term Uptrend, Key Support Near $410
StockCharts.com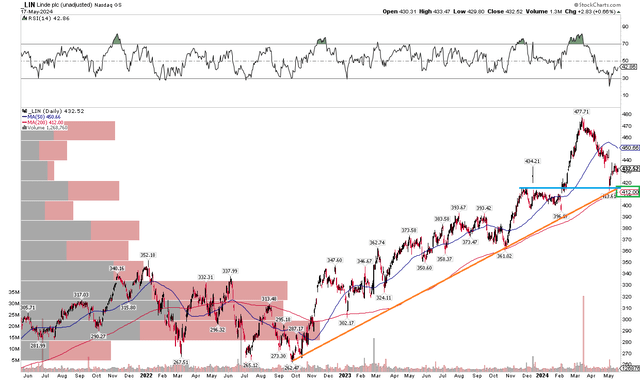
The Bottom Line
I am upgrading Linde to a buy based on fundamentals and a strong momentum trend when taking a step back. While volatility kicked up in April, shares found support on the chart and 10% annualized EPS growth is expected over the quarters ahead.
Credit: Source link









