
Hinterhaus Productions/DigitalVision via Getty Images
Investment Thesis
On Holding (NYSE:ONON) is a company dedicated to sports clothing and that in recent years has stood out for its running shoes, which have very high gross margins thanks to the high sales price that the company has managed to maintain. While its market share is currently extremely small, it is rapidly gaining more and more year-on-year.
I think that if the product continues with the current trend, there’s potential for ON to become a major brand within the sector, but after the recent rise in the share price, I consider it a hold.
Rising Popularity
On Holdings is a Swiss company that is gaining popularity in the running shoes and sportswear niche thanks to its CloudTec and Speedboard technology that seek to provide a premium experience to athletes or people who simply want to have a comfortable pair of shoes.
Although ON shoes are somewhat expensive and a pair usually costs around $150 USD, this contributes to the premium image that the company seeks to project, much like luxury companies that often sell their products at a higher price than would probably be “fair” (I’m not trying to compare ON to a luxury company).
And despite being expensive, we can see using Google Trends as a proxy for the increase in popularity they have had around the world and, as we will see later, ON still has a lot of room to grow.
ON Searches on Google (Google Trends)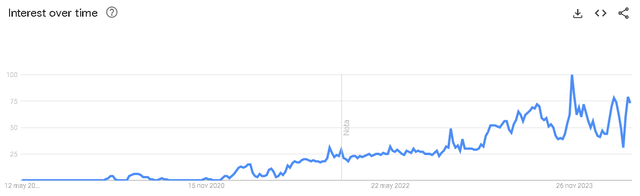
Currently, the United States is being a pillar in the company’s success and although it began in Switzerland, the surrounding countries in Europe seem to be underdeveloped in terms of interest in ON. I think this could change if the company continues to execute its awareness strategy.
Google Trends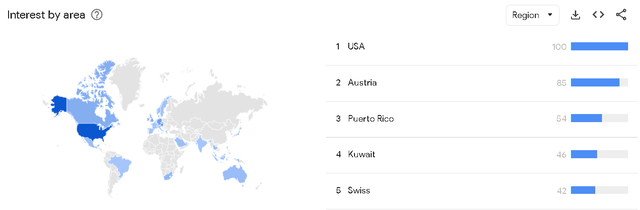
Growth Strategy
Being a company focused on sports clothing, advertising among recognized athletes is an important spot to win, since Nike has shown us in the past the power of being the preferred brand of the favorite athlete of the moment, with the case of Michael Jordan and his Air Jordans, which remain an emblem in the world of sneakers even decades after the athlete’s retirement.
In addition, the company has been gaining a lot of popularity thanks to word of mouth, which is a very powerful tool because if a friend comes to you and tells you that their On Cloud are the most comfortable sneakers they have ever tried and are totally worth the price, as it happened to me, you will undoubtedly want to try them.
ONON Investor Day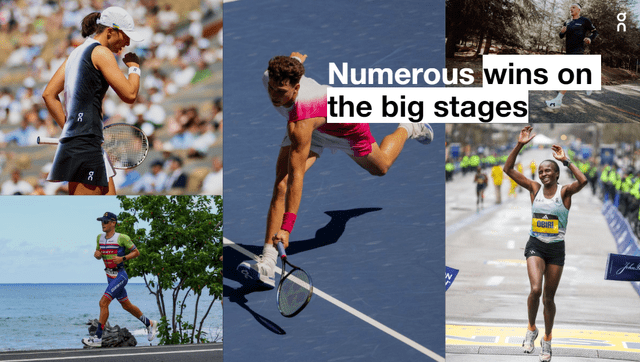
Currently the company is selling two-thirds of its products through intermediaries, such as DICK’s, JD or Foot Locker, which makes sense in an expansion phase where the brand wants to reach as many places as possible as soon as possible. However, I like that the DTC segment is growing at a similar rate to wholesale, since in the long term this will be the best strategy to adopt, removing intermediaries from the middle and being able to further personalize the shopping experience in stores or managing the supply chain for online purchases.
ONON Investor Day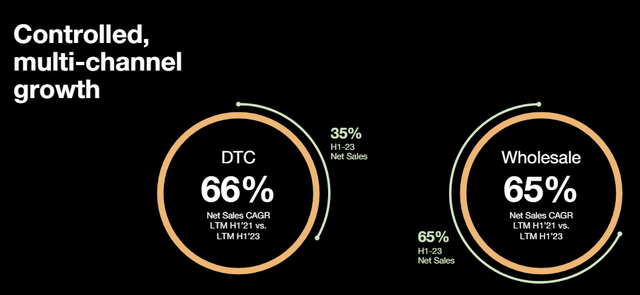
In the following graph we can further notice the opportunity that ONON has and the good trend it has followed. I added up the sales in dollars of all these sportswear brands and considered it as the Total Addressable Market for this exercise, in which we can see how ONON owns less than 2%, but has been gaining market share year after year at an average growth of 55% annually, being the competitor that is growing the most, by far.
The company could triple its sales and still make a little less than Under Armor today. Considering the good reputation the product is having, I see it as a possible scenario.
ONON Market Share (Author’s Compilation)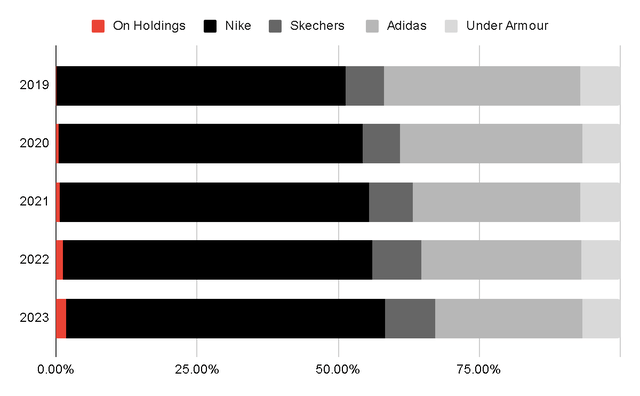
Financial Improvement Potential
Turning to the financial aspect, it is important to note that ONON’s margins are not yet at their maximum potential, since currently its EBITDA margin is at 11.6%, while brands such as adidas (OTCQX:ADDYY) or Skechers (SKX) usually maintain margins closer to 13%. I think ONON could reach and even exceed these margins for two reasons.

First, ONON’s EBITDA potential is not fully exploited because they have been investing 50% of their sales in SG&A, which is good since the company is in full growth and has a product that works, but in the long term this should stabilize more towards 30-40% of its competitors.
| Ticker | EBITDA Margin | SG&A Margin |
|---|---|---|
| DECK | 23% | 32% |
| NKE | 13% | 33% |
| UAA | 7% | 41% |
| SKX | 13% | 42% |
| ONON | 11% | 51% |
Author’s Compilation
But even more important, if we remove the noise generated by investments in growth and only focus on the Gross Margin, we can notice that ONON already has margins much higher than the rest of its competitors, even those of Deckers (DECK), which has the highest EBITDA margin. of the peers.
This makes sense considering that ONON can afford to sell sneakers for $150 dollars without losing customers because of this. On the contrary, it seems that the premium appearance is an important part of the brand and, to be honest, making a pair of sneakers is not that expensive and the price is justified by the brand power, something similar to what happens with iPhones and Apple.

Risks
Although ONON’s story looks promising, the reality is that the risk of this brand becoming a fad is something that must be kept in mind. The sportswear market is extremely competitive and players like Nike (NKE), adidas, Puma or Under Armor (UAA) are not going to make things easy. For a somewhat new brand, the beginning was explosive, but we will have to follow the rest of the story closely.
Another aspect worth mentioning is the fact that the high price of ONON added to the discretionary nature of the product, makes it a cyclical product and in a severe recession or economic crisis, it would be one of the first expenses that a consumer would cut or would be postponed, causing sales to be affected in scenarios like this. Currently, it isn’t so noticeable because they are stealing market share and starting from a small sales base, but as it gains scale, this problem will become more relevant.
The Bottom Line
Investing in ONON depends on trusting the product, considering that it has what it takes to become an important brand within its sector and trusting that management will continue investing in developing the best products and increasing its brand awareness.
While I don’t usually invest without taking valuation into account, this case reminds me of the classic image shared by Terry Smith, where he shows that if you had paid a P/E of 281 for L’Oreal in 1973, you would still have obtained a return of 7% annually over the next 45 years because the exponential growth justified the valuation. I think something like this is happening with ONON, it’s difficult to project its future growth, margins and valuation multiples, but if things go well, the product is so easily scalable that paying the forward P/E of 50 could end up being cheap in a few decades.
Ash Park and Refinitiv Datastream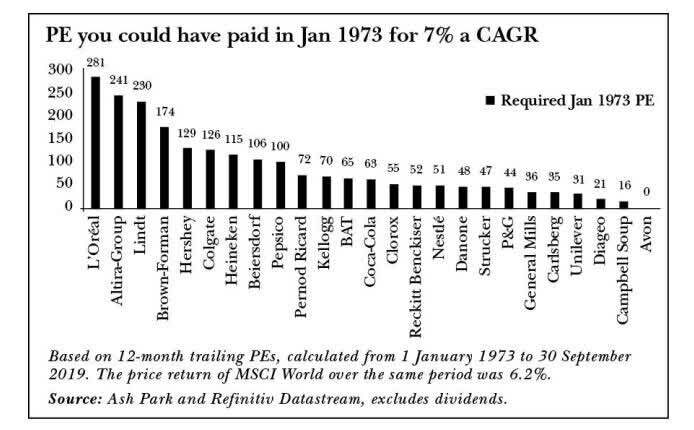
In my case, I consider that after the 20% rise in shares post-results, beating expectations in revenue by 2% but in EPS by 125%, right now the company is a hold, but I will surely be waiting for some correction in the price to take action.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link