
Megapixel8
A year ago, I wrote a cautious article on Ares Commercial Real Estate (NYSE:ACRE), warning that commercial real estate markets were forecasted to weaken and the outlook for ACRE was negative. Since my article, ACRE’s stock performance has continued to lag markets, falling 7.9% compared to a 27% return in the S&P 500 (Figure 1).
Figure 1 – ACRE has lagged markets (Seeking Alpha)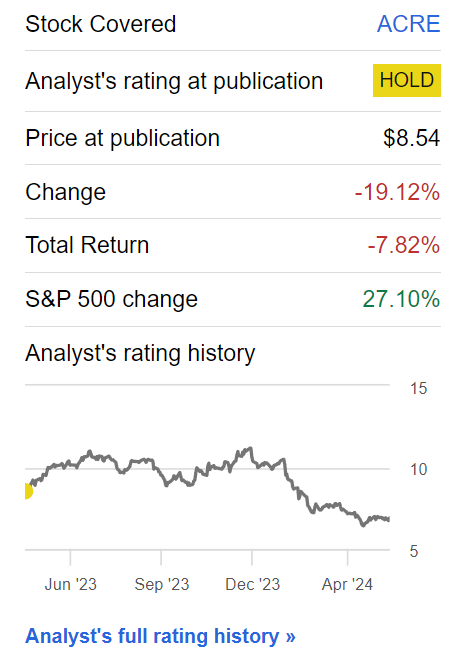
With a year gone by, let us review the concerns I had concerning ACRE to see if they have been resolved, and also revisit my thesis on the stock.
Brief Company Overview
Ares Commercial Real Estate Corporation is a REIT focused on sourcing and investing in senior, directly-originated, short-term commercial loans (Figure 2). ACRE tends to focus on loans ranging from $10-250 million in size with 3 to 5-year terms.
Figure 2 – ACRE investment strategy (ACRE investor presentation)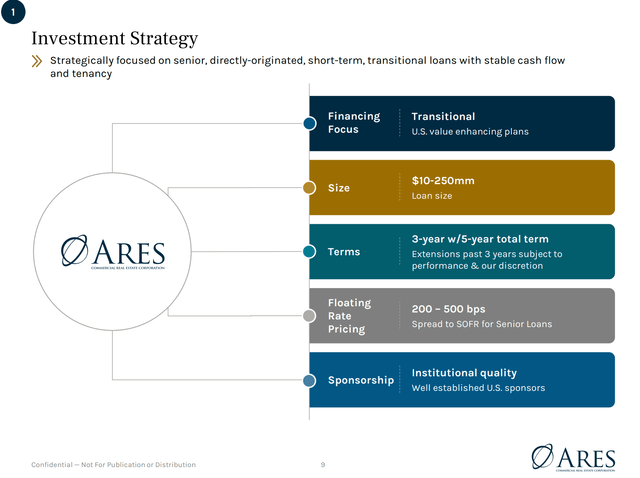
One of the major advantages of ACRE is that it is managed by Ares Capital Management, an alternative asset management behemoth with almost $400 billion in AUM across many diverse sectors and strategies. In particular, Ares has a $49 billion real estate group that can help source and manage ACRE’s loans (Figure 3).
Figure 3 – ACRE is managed by Ares (ACRE investor presentation)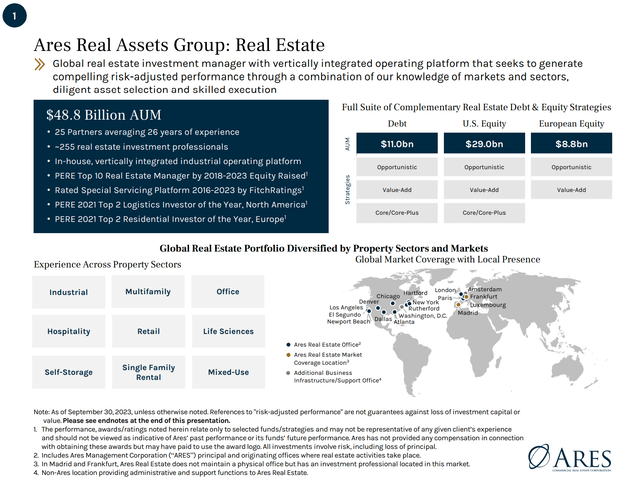
Credit Losses Galore
In my last article, I was mainly concerned with ACRE’s deteriorating credit metrics. For example, in Q1/2023, ACRE took $0.38 / share in provision for credit losses, an 8.6% QoQ increase from Q4/2022’s figure and a dramatic increase from a $0.01 / share release in Q1/2022 (Figure 4).
Figure 4 – ACRE Q1/23 financial summary (ACRE investor presentation)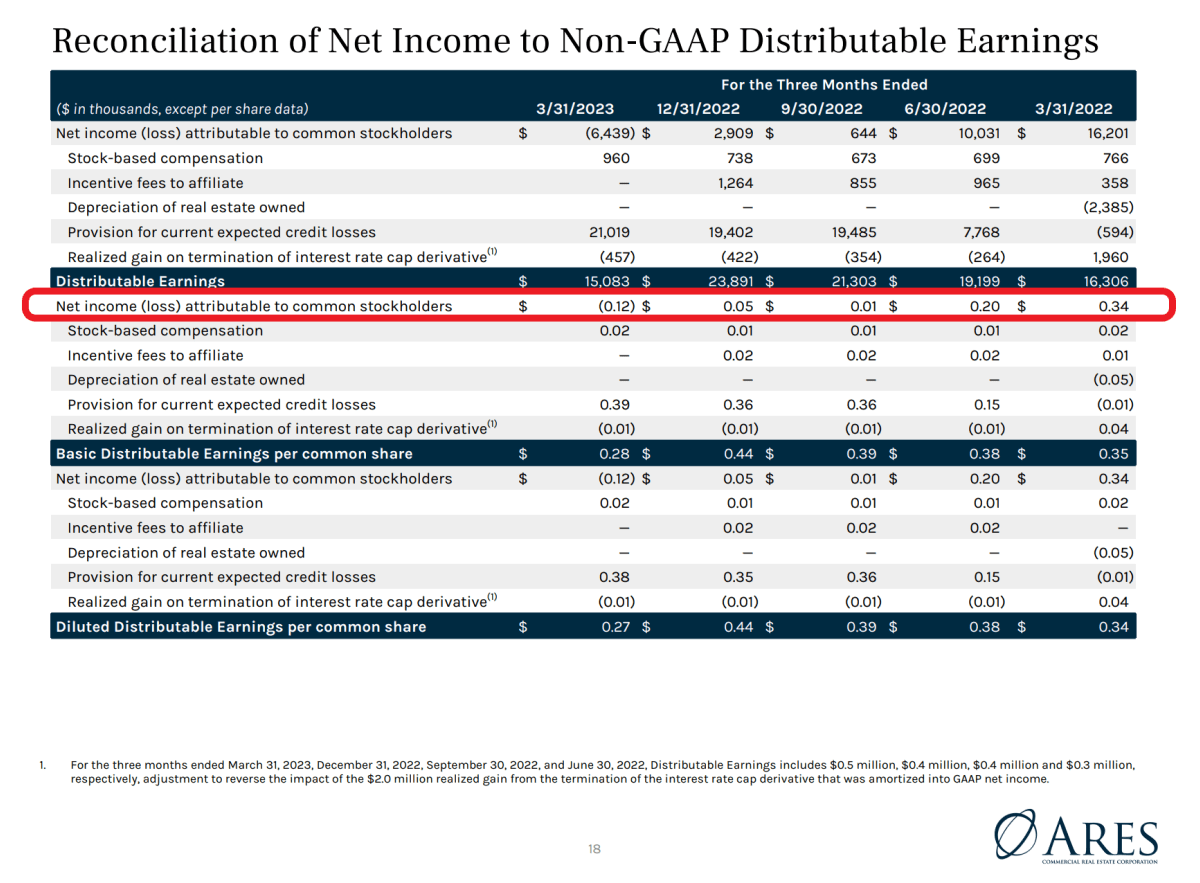
I questioned whether ACRE’s provisioning of current expected credit losses (“CECL”) of 4.0% of gross loans was sufficient, as ACRE had to take sizeable losses on several specific loans (16% and 67% respectively on two loans in Chicago in Q1/23).
In terms of general provisioning, ACRE had only $30 million in provisions against $404 million of risk-rated four loans (7.4% reserve on 2nd worst internal rating at ACRE) and $18 million on $1.7 billion in risk-rated three or better loans (1.1% reserve ratio).
I was particularly worried about $823 million in office loans that ACRE held, as office real estate across the country was facing soaring vacancies due to work-from-home (“WFH”) policies.
Unfortunately, my worries turned out to be prescient, as ACRE had to take an additional $70.8 million or $1.30 / share in CECL provisions in 2023 (Figure 5).
Figure 5 – ACRE Q1/24 financial summary (ACRE investor presentation)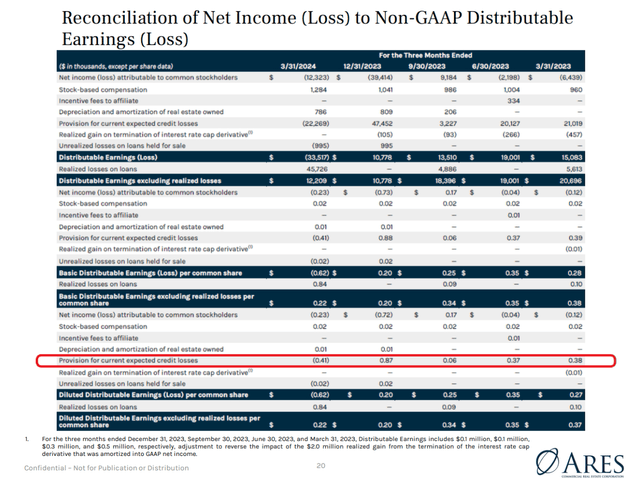
Furthermore, although provisions for CECLs were negative $22 million in Q1/24 or -$0.41 / share, this was because ACRE took realized losses of $42 million on two exited risk-rating 5 loans, while adding $20 million in additional provisions in Q1/24 (Figure 6).
Figure 6 – ACRE CECL trends Q1/24 (ACRE investor presentation)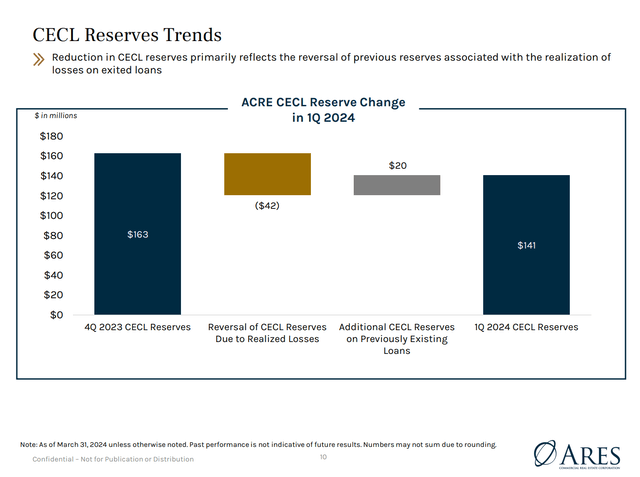
As I had expected, the vast majority of ACRE’s current provisions for credit losses were related to ACRE’s portfolio of office loans. As of March 31, 2024, ACRE had $141 million in CECL reserves, with 61% of CECLs booked against office real estate, 24% against residential real estate, and 15% against other (Figure 7).
Figure 7 – ACRE has $141 million in CECLs (ACRE investor presentation)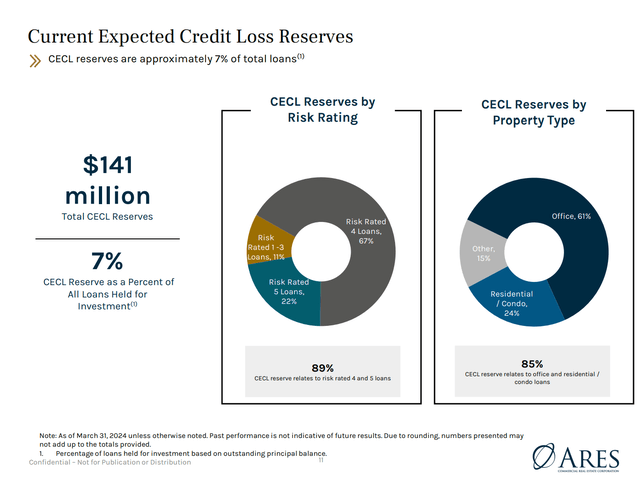
Although ACRE’s loan book has shrunk to $2.0 billion as of Q1/24 (from $2.2 billion as of Q1/23), total CECL reserves have increased to $141 million or 7% of all loans held.
Is 7% CECL Reserves Enough?
As I mentioned in my prior articles, “CRE loan losses are hard to generalize as each property is unique and loan losses can vary,” so it is difficult to say whether 7% CECL reserves is enough to call a bottom.
If we look at ACRE’s risk-rated 4 and 5 loans, the company currently has $125 million of provisions against these loans, or 25% coverage (Figure 8).
Figure 8 – ACRE has $125 million of CECLs against R4 and R5 loans (ACRE investor presentation)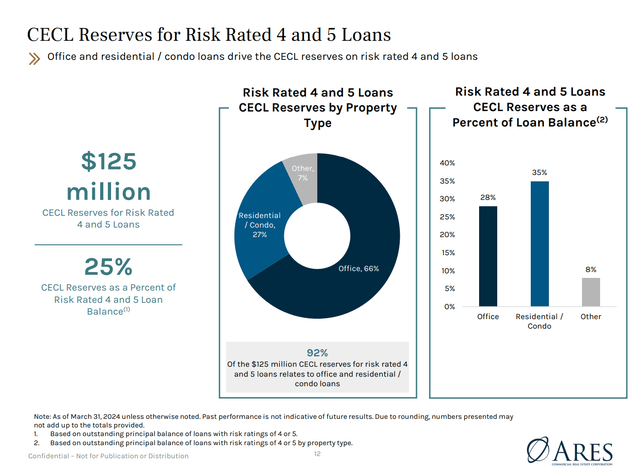
However, as we saw with the realized losses in the quarter, ACRE provisions are often short of actual losses upon default. For example, according to the company’s disclosure, in March 2024, ACRE received a discounted payoff on a senior mortgage loan on an office property in Illinois with an outstanding principal balance of $56.9 million, causing ACRE to recognize a realized loss of $43.1 million on this loan (implying payoff of just $13.8 million).
This example is particularly concerning, as ACRE had been carrying this loan at $49.8 million as recently as December 31, 2023 (loan # 7 in Figure 9). So when the loan came due in February and the borrower defaulted, the property short-sale was only able to bring in net proceeds of $13.8 million, far less than ACRE’s $49.8 million carrying value!
Figure 9 – ACRE office loans, December 31, 2023 (ACRE investor presentation)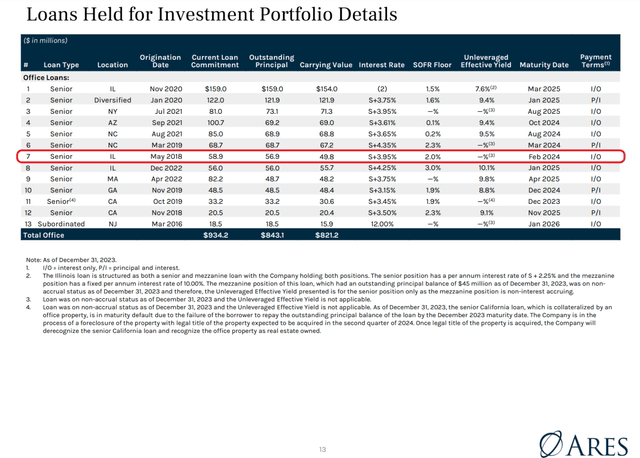
How many more of these landmines are within ACRE’s risk-rating 4 and 5 loans, and how many more of ACRE’s risk-rating 3 loans will migrate to 4 and 5 over the coming quarters?
Flood Of Office Buildings Transacting At Fraction Of Prior Valuations
The root cause of the issue is that despite office vacancies soaring to the highest levels ever (Figure 10) and higher interest rates raising real estate cap rates, commercial real estate valuations were kept in an artificial fantasy / make-belief world where as long as transactions did not occur, both lenders and borrowers were happy to mark their holdings with only small haircuts (like what ACRE did with the $56.9 million loan) and prayed that the Federal Reserve would lower interest rates and bail them out.
Figure 10 – Office vacancies at all-time highs (Moody’s)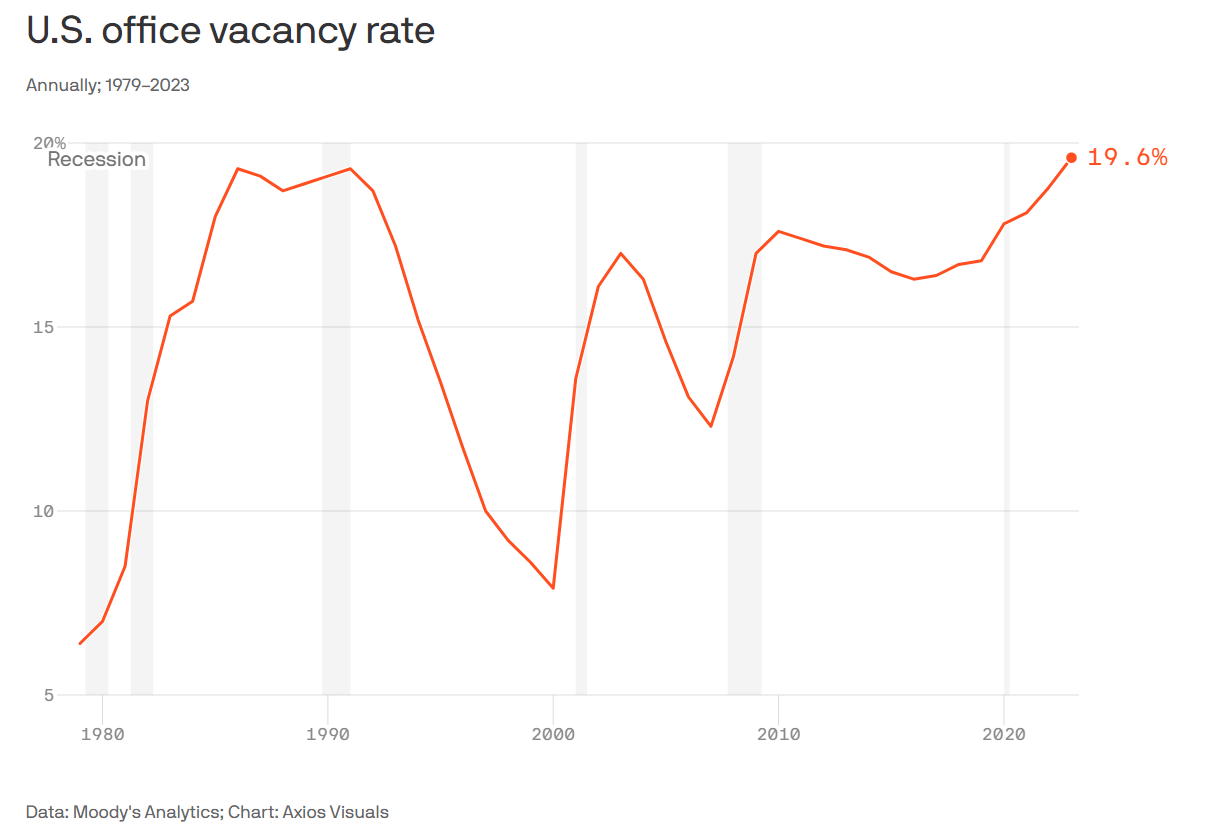
Unfortunately, after 2 years of interest rate increases, many of these short-term commercial mortgages are now coming due, and lenders are increasingly seeing defaults and short-sales like those on ACRE’s problem loans.
Once the floodgates opened, many office buildings were selling for fractions of their last transaction values. For example, the Rosslyn/Xerox Building in Washington D.C. was sold in January for just $25 million, or 17% of the last transaction price of $145 million in 2011. Even tier 1 cities like New York are not immune, as Deutsche Bank recently had to take a $350 million loss at 222 Broadway that last sold for $500 million in 2014. This mark-to-reality is a wake-up call for lenders like ACRE who have kept office loans on their balance sheets with only modest haircuts.
Dividend Cut To Conserve Capital
In order to conserve capital, ACRE also recently cut its distribution by 24% to $0.25 / quarter. This dividend cut must be especially painful for many investors who were ‘bottom fishing’ ACRE shares, attracted by the company’s fat 13%+ yield.
However, after the recent stock plunge, ACRE is once again yielding 14.9%. A high yield should never be the sole reason to buy a security.
ACRE Should Survive; Valuation Looks Interesting
While the macro environment appears terrible, ACRE should survive as it is relatively well-managed and well-capitalized. In fact, valuations on ACRE are starting to look interesting. At $6.91 / share, ACRE is trading at just 0.62x Price-to-Book Value.
In effect, investors are saying they do not trust the provisions ACRE has booked on their loan book and have slapped on an additional $225 million or $$4.13 / share in losses.
However, for those brave souls who want to bottom-pick, I have this old warning from my mentor: “Bottom pickers often end up with smelly fingers”.
Risks To ACRE
In my opinion, the main risk to ACRE is that in the next few quarters, many of ACRE’s loans will be coming up for renewal, at which time, we will see whether ACRE has marked their books properly. I worry that we will get many replays of the $56.9 million loan debacle where ACRE ends up taking huge realized losses as their carrying values were too optimistic.
On the other hand, a lot of losses are already baked in, with ACRE trading at just 0.62x P/BV. If actual losses are better than feared, ACRE may even rally on the back of bad financial results in the next few quarters.
Conclusion
So far, my warnings on ACRE continue to play out as commercial real estate losses continue to pile up. With office real estate markets finally thawing, we are starting to see a mark-to-reality on many office loans that are causing outsized losses to lenders like ACRE.
While ACRE looks cheap trading at 0.62 P/BV and a 14.9% yield, I prefer to wait for the actual turn in commercial real estate markets before jumping in. Better safe than sorry.
Credit: Source link