
Victor Golmer/iStock Editorial via Getty Images
Dear readers/followers,
My investment in KION (OTCPK:KIGRY) stock has been paying off, since purchasing shares, and a respectable position at a low valuation. My last major buy was made during later periods of 2022 – and my stance has produced a TSR of over 35% including the dividend, compared to the S&P 500 as of the time of writing this article.
Still, while we’ve seen the beginnings of recovery, KION still has a long way to go. In this article, I will update my thesis on KION as a business, and the upside that the company may deliver for investors over the longer timeframe. By the long timeframe, I mean a timeframe of over 3 years from this time – which is still how long I expect to own KION before potentially rotating it – depending of course on what the market does in the meantime.
Here is my last piece on KION.
Even if the next few quarters of results should fail to come in as positive as some might expect at this time, the future for this company is, as I see it, very positive – and I’ll show you in this article why exactly this is.
Also, why it’s not necessarily too late for you to enter here, even if the returns that I have already seen, and will see in the future, are less likely in the same timeframe?
KION – Moving to €50/share, and beyond in the future
The company has actually, during only a few weeks ago, already hit that €50/share, before declining back down due to both macro and market.
KION Stock price, Google Finance (KION Stock price, Google Finance)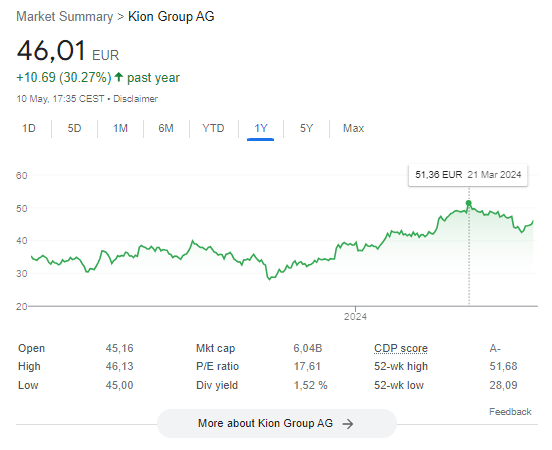
There’s quite a bit of information to digest here, so let’s begin with the 1Q24 period and what we saw here.
Order and revenue was up sequentially, but down year-over-year, but with a significant increase to the ever-important profit. The company’s EPS was up by more than 50% YoY and over 30% sequentially, fully confirming the ongoing reversal we’re seeing here for KION. Margin was up over 200 bps YoY, and over 70 bps sequentially, with EBIT up 45% YoY.
The company’s full-year guidance is unchanged and confirmed as of the first quarter, and solid revenues support the second-best quarterly adjusted EBIT for the company.
As you now, if you follow the company and my articles on it, KION is a play on two segments – ITS and SCS. Both of these segments saw an upside in the company. The ITS segment saw margin growth to 11.1, with a significant increase of 7% in revenue. Adjusted EBIT for the segment reached a record quarterly profit level.
KION IR (KION IR)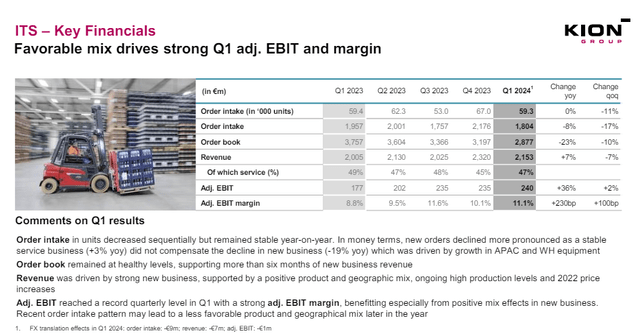
Remember, I bought the company and started buying the shares back in -22, below the €20/share level. Not my entire position, unfortunately – but a fair bit, with a current cost basis of just over €26/share. This means that I’m slowly approaching a triple-digit return for my investment in KION.
SCS is seeing more, shall we say, sequential improvements in profitability and upside. Margins are now at 2.6%, but up 170 bps year-over-year, with a good order intake and a higher share of service contracts. This segment is less “explosive” than the former, and we shouldn’t expect sudden moves given the sales mix.
Overall, 1Q24 represents a very solid beginning to the year – slow but fully supporting the full-year KPI guidance.
The company’s P&L as a result of the 1Q24, is looking good. NWC was stable, the company generated over €50M of CF during the quarter, and this includes over €30M in taxes and changes in liabilities. The company’s net debt is now down to net financial debt at 0.7x, with an industrial net debt of 1.8x as of March 2024.
Again, this is confirmation of 2024.
KION IR (KION IR)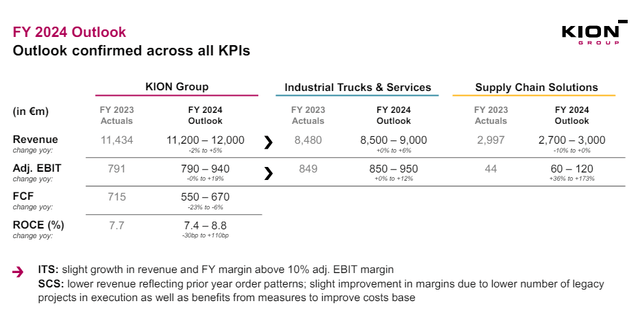
And what I want to see is confirmation and continued encouragement for my long-term thesis for KION – I’m getting that here. The company’s focus on Mobile Automation, which in turn is a focus for many of its customers, is beneficial, with focus on projects like LogiMAT and KAnIS. The company’s expectations are in turn based on a fairly modest growth on a forward basis, with only 3% for global, and developed countries growing less than 1.6%.
To hit its 2024E targets, the company expects only slight growth in both ITS and SCS, but rather a continuing reversal to higher profitability which we’ve already seen.
A reminder here that KION has materially improved, going from leverage of 4x to less than 2x in less than 10 years. The company now has a total of €1.6B+ in cash or equivalents/undrawn liquidity available, and this is enough to cover every single maturity until 2030.
So talking about the company “not being safe”, that’s not really possible anymore.
As I said, I’ve already seen close to a 100% RoR in my investment here. But I continue to believe that this is only the beginning for KION. This company has quite a bit still to go before I would consider it “fully valued”.
And this company is, as you may recall, the world leader in key areas in logistics and transport.
KION IR (KION IR)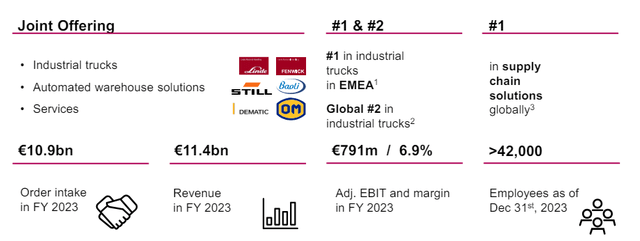
It has appealing sales mixes, with a 44% service business and a 65%+ EMEA focus, with a fair way to grow in APAC and the Americas both. While the company is unlikely to go past Toyota in Industrial trucks, Toyota is unlikely to beat KION in automation in the near term. The company’s plan from a forward perspective is to increase R&D spending to gain market share. As of 2023, the R&D spend is up from 2.6-2.9% to over 3%, with focus on new platforms, sustainability as well as more focus on automation.
KION IR (KION IR)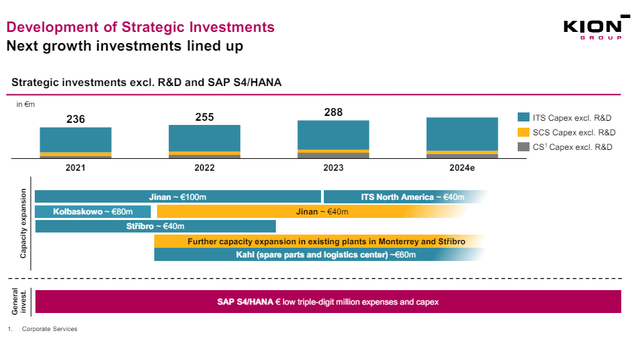
In the future, I expect upsides to be based around the solid and positive margins of emerging markets, sustainable solutions, growth of continued e-commerce, and continued urbanization due to demographic changes – all of which have growth implications for the company’s core sectors.
I believe the last few years should be seen as a temporary weakness, with 2023 not representing the long-term expectations for this market or what it’s capable of performing.
Also, the company’s valuation makes, I believe, this company one of the plays in the field that you should consider even now.
At the same time, it wouldn’t be fair of me to not give you the risks associated with the company – so let’s do that.
KION – Risks and Upsides
While KION has excellent growth prospects, the company’s primary challenges will be related to investing enough to efficiently enable the growth, without cutting into margins and returns for the operations, with key opportunities in e-commerce and e-procurement in both trucks and automation.
The primary risks here include a shift toward automation opening up the market for new entrants with better solutions, and the hardware for Warehouse systems and forklifts being purchased at two different stages, which means that being a company that offers both can be somewhat tricky in terms of revenue synergies. This, coupled with macro volatility, makes for the company’s two core growth risks here.
On the positive side, we have KION’s market-leading position, and the company’s products and technologies, including Dematic into the mix, the company is now ideally positioned to enjoy upside from Warehouse automation, enabling a growth potential of 4-7% annually over the next few years. If this is achieved, and this also translates to margins and earnings, then the company has no business trading at a low multiple.
What this means for valuation is as follows.
KION valuation – plenty to like here, despite already having moved from sub-€20/share
Obviously, the right time to “BUY” KION was below €25/share. However, if you missed out on this, that doesn’t mean that there’s no upside to be had here.
Much of that upside is not based on dividends – because yield here is only around 1.5% – but instead growth. Let me show you some of the expectations the market has for KION here.
KION Upside F.A.S.T graphs (KION Upside F.A.S.T graphs)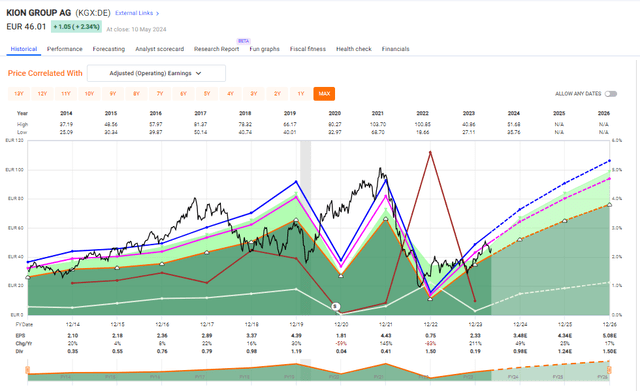
A few things are clear from this. First, the company has been valued, at least at times, at over €100/share. If the company ever went back there under current circumstances, I would be selling. Secondly, the company has been through a slump as of late but is now recovering from that slump.
Third, the current valuation, while over 16x P/E normalized, is nowhere near indicative of where the company could go, if these forecasts of double-digit growth materialize. And to remind you, the 2024E forecasts for the company have been confirmed as of 1Q24.
A look at the KION ADR page will tell you that I am the only analyst to cover KION on SA with any frequency. The hours of research I have put into the company leads me to a fairly good idea of what the company does, and where it believes itself capable of going.
While the thesis is now materially less attractive than before, it’s still an attractive thesis with double-digit potential, even triple digits.
How?
On the longest-term normalized P/E, we have, 11 years, KION tends to be valued at around 21x P/E. If 21x P/E is the company’s valuation we’ll see as it continues to grow, at an estimated 26%+ annualized rate until 2026E, then this is the annualized RoR you’d be able to expect during that time.
KION F.A.S.T Graphs Upside (KION F.A.S.T Graphs Upside)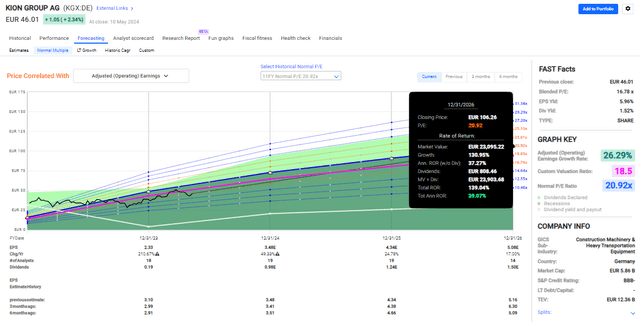
However, do note that this expects that price above €100/share, which unless there’s continued supporting growth there, I’d probably be rotating my stake at that time. This is what I would consider a “positive” case, with almost 40% annualized.
However, we can go much more conservative than that.
How about expecting KION to not even manage 15x P/E, despite that 20x+ normalized, and a relatively clear pathway to EPS growth? What would the company then give you until 2026E?
Around 22% annualized, or almost 70% until 2026E.
F.A.S.T Graphs KION Upside (F.A.S.T Graphs KION Upside)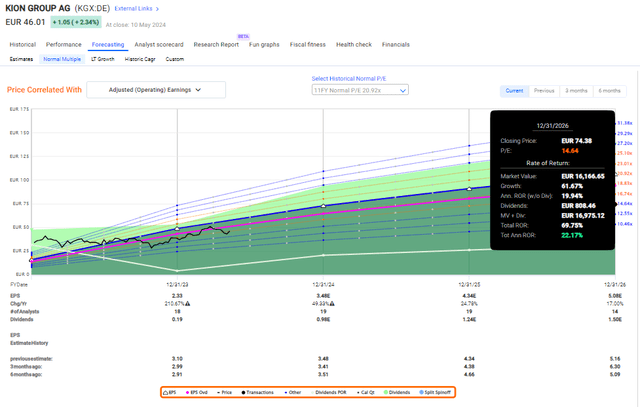
At what point, under the current circumstances, would we be looking at a negative RoR?
The company would have to move below an 8-9x P/E, which would be around €20/share price during a time when the company is expected to grow double digits.
Are you understanding why I consider such a scenario to be less than likely here?
In my last article, I went with a €78/share PT. I am upping this to €80/share to slightly reflect the outperformance in 1Q in a few KPIs, as well as the somewhat clearer 2-3-year upside I see here. I would be surprised if the company did not achieve a €70-80/share price target until 2026.
On this basis, I give you the following thesis and upside for KION.
Thesis
My thesis on KION is as follows:
-
KION Group is an attractive capital goods play with an emphasis on intralogistics solutions, automation, and warehouse technologies – things like forklifts, to put it simply. The upside for 2024E is still there, even if the company has recovered a meaningful amount in its valuation when it once again climbed over €40/share.
-
The company is undervalued and forecasts imply a significant upside over the coming 5 years, with an upside of over 100% – and this upside and undervaluation is still very much there.
-
KION is a “BUY” with a price target of €80/share, updated for 2024E, but I am not shifting it further at this time, even if a higher upside of €120/share is certainly possible in a bullish context. Because of this, I say that the company is a very good prospect here, if you’re willing to put up with low yield.
Remember, I’m all about:
-
Buying undervalued – even if that undervaluation is slight, and not mind-numbingly massive – companies at a discount, allowing them to normalize over time and harvesting capital gains and dividends in the meantime.
-
If the company goes well beyond normalization and goes into overvaluation, I harvest gains and rotate my position into other undervalued stocks, repeating #1.
-
If the company doesn’t go into overvaluation, but hovers within a fair value, or goes back down to undervaluation, I buy more as time allows.
-
I reinvest proceeds from dividends, savings from work, or other cash inflows as specified in #1.
Here are my criteria and how the company fulfills them (Italicized).
-
This company is overall qualitative.
-
This company is fundamentally safe/conservative & well-run.
-
This company pays a well-covered dividend.
-
This company is currently cheap.
-
This company has a realistic upside based on earnings growth or multiple expansion/reversion.
That means that the company still fulfills all of my criteria for attractive valuation-oriented investing. I’m still at a “BUY”, but I will no longer call it “cheap” above €45/share.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link