
Robert Way
Brief Review Of Alibaba’s Q4 FY2024 Report
In light of reporting mixed results for Q4 FY2024 (Mar-24), Alibaba Group Holding Limited (NYSE:BABA) stock is sliding by ~7% in today’s trading session as of writing, reversing some of its recent gains. While Alibaba’s bottom-line performance was disappointing, the ongoing top-line re-acceleration is heartening for long-term investors as Alibaba’s increased investments in its core businesses are starting to bear fruit!
Alibaba Q4 FY2024 Earnings Presentation Alibaba Q4 FY2024 Earnings Presentation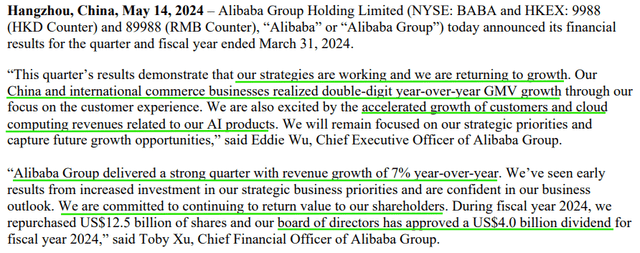
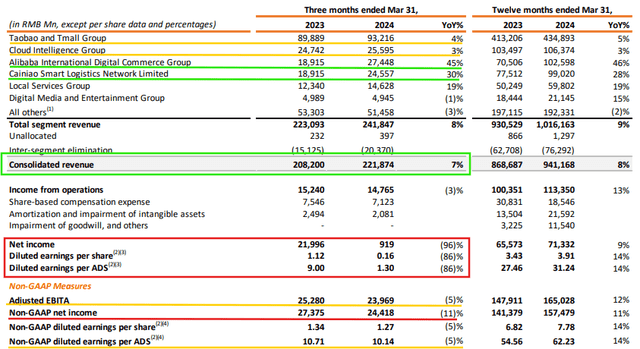
For Q4 FY2024, Alibaba reported revenues of $30.7B [RMB 221.87B vs. est. RMB 219.80B, a beat of ~1%], driven by strong top-line momentum in Alibaba International Digital Commerce [AIDC] Group (+45% y/y) and Cainiao Smart Logistics (+30% y/y), coupled with healthy growth within Taobao & Tmall Group [TTG] and Alibaba Cloud [triple digit growth in AI products & services].
Alibaba Q4 FY2024 Earnings Presentation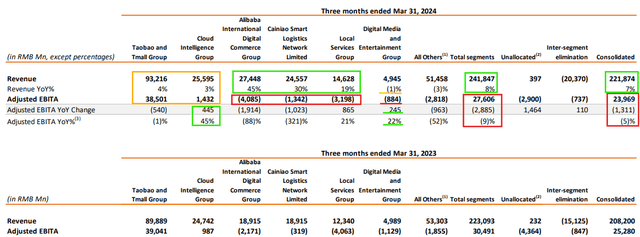
Now, while Alibaba’s revenue growth accelerated from 5% y/y in Q3 to 7% y/y in Q4, its profitability took a hit this quarter, with adj. EBITDA sinking -5% y/y to RMB 23.97B and operating income declining -3% y/y to RMB 14.76B. Overall, Alibaba’s non-GAAP net income fell -11% y/y; however, aggressive stock buybacks boosted non-GAAP EPS to limit the decline to -5% y/y.
On a GAAP basis, Alibaba’s net income collapsed -96% y/y in Q4 FY2024 -primarily due to mark-to-market losses on its publicly listed investments. While this is an ugly headline number, it is inconsequential in the big picture.
In “Alibaba Just Took A Leaf Out Of A Big Tech Giant’s Winning Playbook,” I wrote the following:
In the hunt for future growth, Alibaba is refocusing on its core e-commerce and cloud businesses, with plans to increase investments in 2024. By lowering its take rates, Alibaba is looking to boost GMV through improved usage frequency across its e-commerce assets (primarily, Taobao and Tmall group). The long-term strategic plan here is to monetize via advertising, which is something Amazon has done and is doing incredibly well! In my view, Alibaba could build a multibillion dollar, high-margin advertising services business over the long run given its humongous e-commerce presence [1B+ users].
As evidenced by double-digit GMV growth in Taobao & Tmall Group, Alibaba’s increased investments in improving TTG’s price competitiveness and user experience are starting to bear fruit. Furthermore, the 88VIP membership base is growing at a double-digit rate, surpassing 35M in Q4 FY2024.
Alibaba Q4 FY2024 Earnings Presentation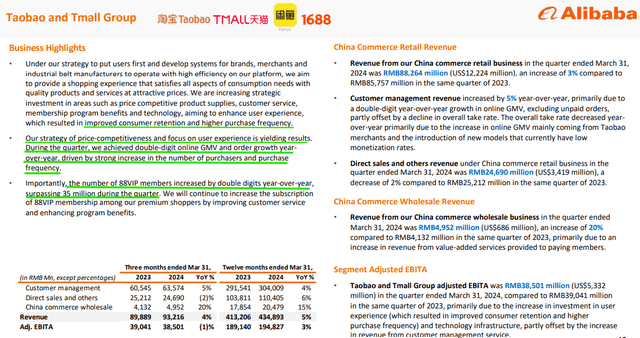
While lower take rates are hurting TTG’s profitability (adj. EBITDA down -1% y/y, adj. EBITDA margin down from 43.4% in Q4 FY2023 to 41.3% in Q4 FY2024), Alibaba’s core TTG business is growing at a healthy clip once again.
The long-term strategy here is to boost GMV across e-commerce assets [increase market share] and then monetize via ads! As of Q4 FY2024, the first part of BABA’s strategy is clearly working, and Alibaba’s management reiterated confidence in the monetization part on the Q4 FY2024 earnings call. Hence, long-term investors should look beyond temporary earnings weakness in the TTG business.
Now, let’s shift our focus to the cloud business.
With Alibaba reducing low-margin project-based contracts within Alibaba Cloud, overall growth of +3% y/y for Cloud Intelligence Group looks subdued; however, when we look under the surface, there’s a very positive trend -> Alibaba’s core public cloud offerings (elastic compute, database, and AI products) grew by double-digit y/y in Q4 FY2024, with acceleration in AI-related revenue [which is growing at a triple-digit y/y growth rate]!
Alibaba Q4 FY2024 Earnings Presentation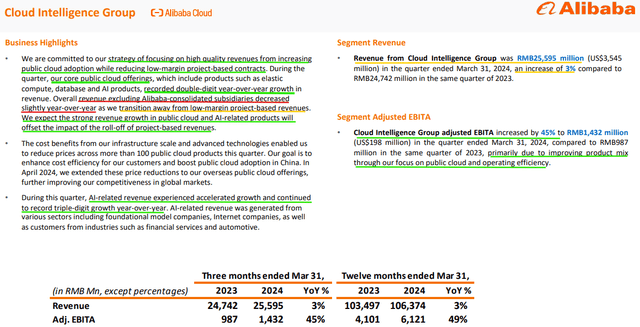
In Q4 FY2024, Alibaba Cloud’s adj. EBITA rose by 45% y/y to $198M, primarily due to improving product mix through Alibaba’s focus on public cloud and operating efficiency. As we have discussed in the past, Alibaba Cloud has a long runway of growth ahead of itself, and as a BABA shareholder, I am delighted to see improving underlying growth and profitability trends here.
Over the last twelve months, Alibaba has delivered ~$21.6B in free cash flow and returned ~$14.8B to shareholders via stock buybacks [$12.3B] and dividends [$2.5B] (paid in January 2024). With its management prioritizing top-line growth in its core businesses by elevating CAPEX spending, Alibaba’s free cash flow generation is taking a severe hit right now. However, Alibaba building a digital advertising business on top of its e-commerce platform [akin to Amazon] promises to be a fantastic long-term revenue and profit growth opportunity, i.e., the long-term gain far outweighs the short-term pain.
Alibaba Q4 FY2024 Earnings Presentation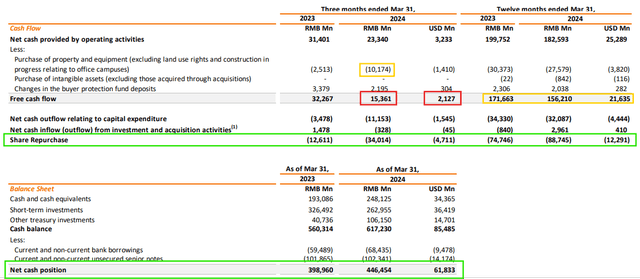
Yes, Alibaba will have to weather short-term pain caused by a heavy re-investment cycle, but BABA’s net cash balance of $61.8B is ample dry powder to support this aggressive growth strategy. With monetization expected to improve in the back half of FY2025, Alibaba’s management remains confident about its cash flow generation prospects.
In Q4 FY2024, Alibaba repurchased 524M ordinary shares (65M ADSs) for $4.8B to achieve a net reduction of -2.6% in BABA’s outstanding share count, which stood at 19.47B ordinary shares (2.434B ADSs). This was a significant jump in buyback spending, and given Alibaba’s buyback program still has ~$30B in authorized capital remaining, we can expect management to continue to deploy more capital towards buybacks as long as BABA stock valuation remains depressed.
Alibaba Q4 FY2024 Earnings Presentation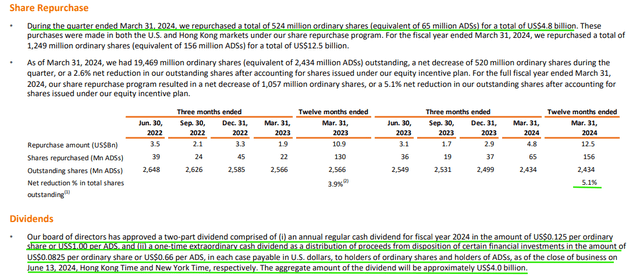
During the earnings call, Alibaba’s management reiterated their goal of achieving a net share count reduction target of 3% per year for the next 3 years (assuming an increase in BABA’s share price), with annual buybacks estimated to be around $12B. Additionally, they unveiled a two-part $4B dividend for FY2024: an annual dividend of $1 per ADS and a one-time extraordinary dividend of $0.66 per ADS.
With Alibaba undergoing a heavy re-investment cycle, I do not expect BABA’s management to be as aggressive with their stock buybacks as they were in Q4 FY2024. However, if BABA stock remains depressed, management could easily afford to be more aggressive, given Alibaba’s massive cash hoard. In the past, we have discussed management’s shareholder-friendly approach at length, and given Alibaba’s recent buybacks and dividends, I am happy with Alibaba’s shareholder return program.
In my view, Alibaba is a fundamentally sound business that will continue to generate and return billions of dollars back to shareholders for the foreseeable future despite undertaking a heavy investment cycle within its core businesses over the upcoming quarters. While headline numbers for Q4 were somewhat underwhelming, Alibaba’s core businesses are improving underneath the surface, as we learned in this note.
Now, let’s take a look at Alibaba’s valuation.
Alibaba Fair Value And Expected Return
In an update on Alibaba last summer, I wrote the following –
While Alibaba is struggling to find revenue growth amid economic doldrums in China, BABA’s management has made several shareholder-friendly moves in recent quarters, including cost optimization efforts across the business (improving profitability and cash flow generation), enhancement of Alibaba’s capital return program, and business reorganization (breakup into six different units announced in Q1). In my view, all of these moves are set to power a recovery in Alibaba’s stock over the coming 12-18 months, with the stock currently trading at a depressed EV/FCF multiple of just ~6-7x.
Today, Alibaba’s top line is re-accelerating, but profitability [FCF generation] is under huge pressure [amid heavy CAPEX spending]. That said, from a relative valuation standpoint, Alibaba stock continues to look deeply undervalued at ~9x P/FCF and ~6x EV/FCF [based on TTM FCF: $21.6B, market cap: $191.43B, net cash: $61.8B].
Here’s my updated valuation model for Alibaba:
TQI Valuation Model (Free to use at TQIG.org)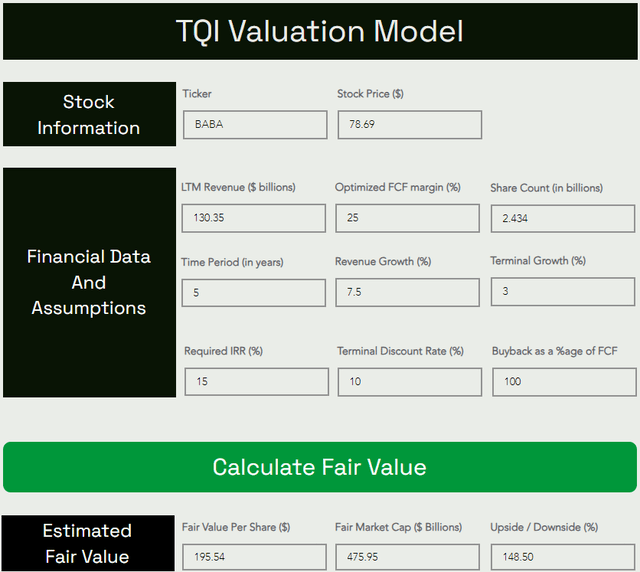
As you can see above, Alibaba is worth ~$195.54 per share or $476B, i.e., it is deeply undervalued at current levels. Assuming a conservative exit multiple of ~15x P/FCF (a “China” discount is embedded into this assumption), Alibaba’s stock could be trading at ~$490.45 five years from now (by 2029). This price target implies a 5-year CAGR return of ~44.2%.
TQI Valuation Model (Free to use at TQIG.org)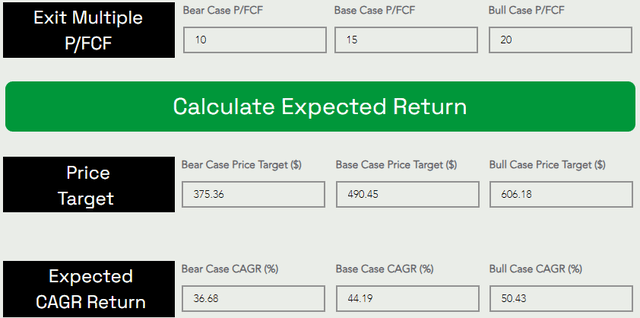
Considering the asymmetric risk/reward on offer (44%+ CAGR return for the next 5 years), I continue to view Alibaba as an incredible investment opportunity! While ongoing geopolitical tensions, regulatory crackdowns, and economic problems in China have led to ultra-negative investor sentiment for Chinese equities, investors are being handsomely compensated for taking on these additional risks. At ~9x P/FCF and ~6x EV/FCF, Alibaba Group Holding Limited remains a no-brainer buy for long-term investors, given its robust financial performance in the face of a challenging operating environment.
Concluding Thoughts
Over the last several quarters, I have written multiple bullish reports on Alibaba, citing its solid business fundamentals and dirt-cheap valuation:
Author’s Coverage on BABA (Seeking Alpha)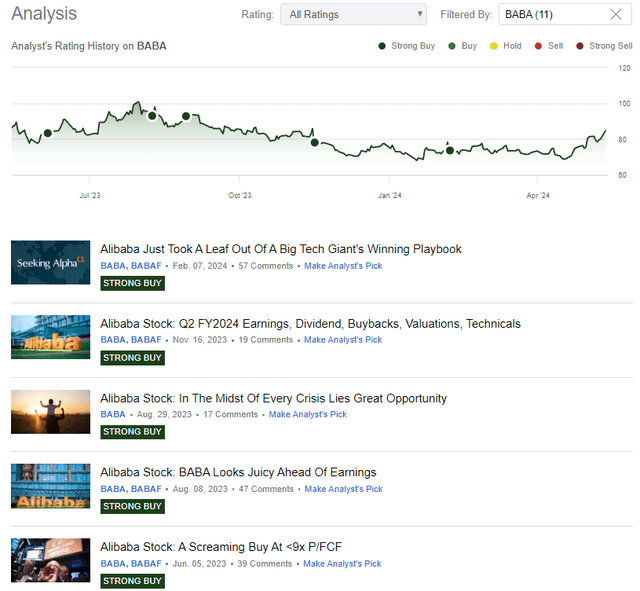
While BABA stock has continued to tread water around multi-year lows for several quarters now, the underlying improvement in Alibaba’s core businesses observed in today’s note provides ample reason for long-term investors to get more bullish on Alibaba. Amid macroeconomic stress in China, Alibaba’s top-line growth has slowed to a single-digit rate; however, the Chinese tech conglomerate is still a free cash flow and capital return machine.
With the Chinese financial markets and economy in turmoil, China’s government and regulatory authorities have shown a willingness to ease up their policy stance and crackdown on tech giants. And, Alibaba’s co-founders Jack Ma and Joe Tsai purchased BABA shares worth $200M earlier this year.
Technically, Alibaba stock is seeing another strong rejection from the upper trend line of a falling wedge pattern in light of its Q4 FY2024 report. However, BABA stock looks like a coiled spring ready to explode higher at any time, given positive sloping momentum indicators [RSI and MACD].
WeBull Desktop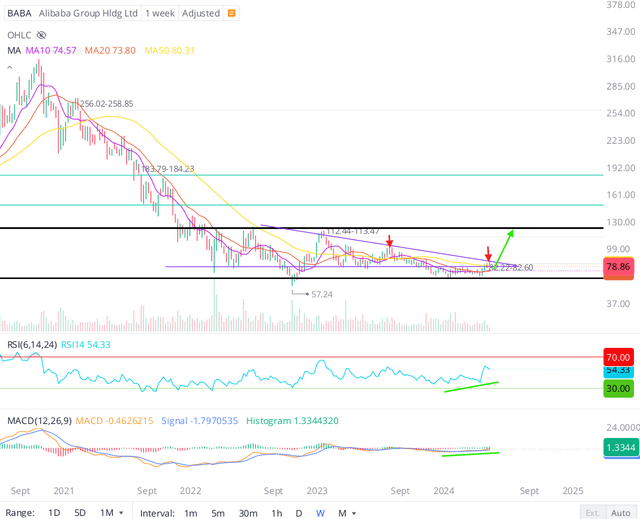
As long as Alibaba holds near-term moving averages-10-wk and 20-wk [low $70s]- the short-term trend here is bullish. A breakdown of the low $70s could lead to a re-test of cycle lows in the low-to-mid-$50s; however, I think Mr. Market will reward Alibaba’s improving business fundamentals sooner rather than later.
Key Takeaway: I continue to rate Alibaba a “Strong Buy” in the $70s.
Thanks for reading, and happy investing! Please share your thoughts, questions, and/or concerns in the comments section below.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link