
VV Shots
In my previous articles (such as this article), I recognized quite early on that Citigroup’s (NYSE:C) (NEOE:CITI:CA) strategic restructure is the genuine focus. It was clear that Jane Fraser’s plan wasn’t just a cosmetic or “a lipstick on a pig” exercise, unlike the 12 or so prior attempted restructures.
The key signs for me were:
- Abandoning the global ambition of the Global Consumer Bank (the prior strategy didn’t make any sense whatsoever to me);
- Committed investment in high ROE and capital-light business lines such as Services and Wealth Management divisions;
- Outsized (and some would argue a belated catch-up) investment program focused on digitizing and modernizing the firm; and
- Commitment to deal with Citigroup’s bloated cost structure and famous internal bureaucracy.
All of these aspects were music to my ear, and purposefully designed (amongst other key objectives) to reduce Citigroup’s capital ratios in the medium to long term.
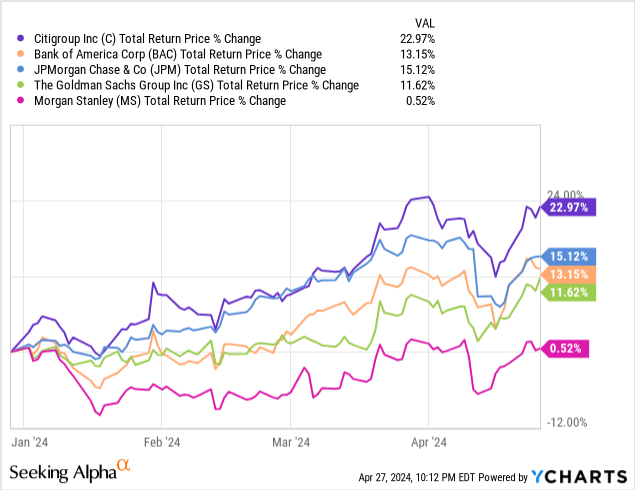
For the longest time, Mr. Market remained skeptical, but more recently the sentiments around the Citigroup narrative are beginning to finally change and recognize the significant progress being made by the management team. So far in 2024, Citi is one of the best-performing large banks:
My strong conviction in Citigroup’s turnaround meant that I was compelled to purchase long-term options when the stock was trading at sub $40 levels (as per my X account):
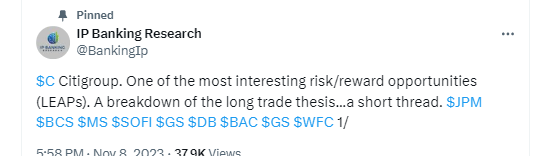
IP Banking Research X Account
The returns so far have been in the order of ~4x, however. I do believe there is a long runaway remaining provided the team continues to execute and the economy avoids a serious recession.
Citigroup Targets for 2025-2026 Period
Citigroup management has consistently stuck to its target of 11% to 12% RoTCE by the medium term (which is 2025 to 2026 period). If Citi can meet these targets, then the share price should trade at around 1x to 1.2x of tangible book value (“TBV”) depending on assumptions made on its cost of capital. I expect Citi’s TBV to reach ~$100 by the end of 2025, so that points to a valuation of between $100 and $120.
Many investors are of course skeptical that Citi can meet these targets. My base case, when buying the long-term call options, has been that Citi will come short as well and only manage to deliver ~10% RoTCE and be rewarded with a valuation of 0.8x TBV, translating to a $80 share price.
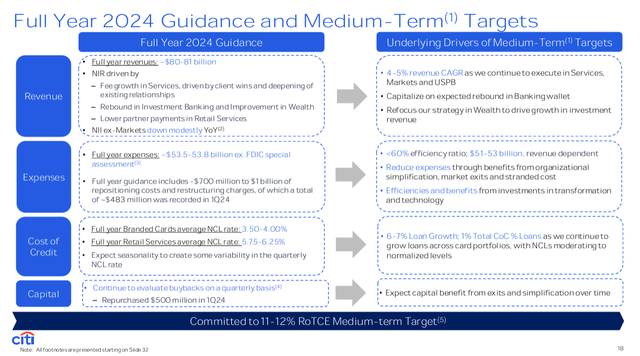
To meet its target of 11% to 12% RoTCE in the medium term, Citi is making certain assumptions about Revenue, Costs, and Capital:
- forecasts revenue CAGR of 4% to 5%;
- costs to reduce in absolute terms in 2024 and beyond;
- capital targets to include the impact of Basel 3 as currently proposed
Citi has reaffirmed its guidance in the Q1-2024 earnings call:
Citigroup Investor Relations
Citi has executed exceptionally well and more quickly than expected on the cost side. Citi is now guiding for lower costs in sequential quarters for 2024 and 2025. The main uncertainty though in reaching its targets now is on the Revenue line, and this came through clearly in some of the analysts’ questions on the Q1-2024 earnings call:
GLENN SCHORR: … I think people have totally bought into the expense story, so a lot of credit to you guys. I think where I, personally, and others still have questions on is on the revenue side and getting to those 4% to 5% medium-term targets…. So, could you take us just conceptually where we’re going to where you think you’ll drive that growth from, from this baseline where we’re at now?
MARK MASON: Sure. And good morning, Glenn, and we appreciate the acknowledgment around the expenses. ….. So Services up 14% with growth in both TTS, between cross-border, clearing, commercial cards, but also and Securities Services, right, with the growth that we’re seeing from continued momentum in assets under custody. We expect that trend to continue with existing clients and new clients as well as how we do more with our commercial market commercial middle market business, excuse me. So NIR growth there. The Investment Banking piece is the other driver of fees. We’re seeing that wallet start to rebound. We’re part of that rebound. The announced transactions, we’re part of those in sectors that we’ve been investing in. We’re bringing in new talent to help us realize and experience that. And even in Wealth, where we’re not pleased with the top line performance this quarter of down 4%. When you look through that, we do have good underlying NIR growth in the quarter in Wealth and that’s up 11% year-over-year and it’s in the area that Andy and the team is leaning in on which is investments and not just in one region, but across all the regions. And then finally, the USPB piece which is showing good NIR growth as well, so the long and short of it is that the 4% growth that’s implied in $80 billion to $81 billion is going to be continued momentum, largely in fees, helping us to deliver for our clients and make continued progress towards that medium-term target.
While uncertainties relate to the Revenue picture and are somewhat macro-dependent, there are several tailwinds. Firstly, recovery in Investment Banking (“IB”) fees wallet is currently in progress following a rather depressed 2023. Normalizing IB fees should support the 4% to 5% Revenue CAGR guidance. Additionally, the Services division revenue trajectory has significant in-built momentum, whereas the Markets division 2nd half 2023 comparables are not demanding either. So overall, I am broadly constructive in respect of the Revenue picture for 2024 and beyond.
In the alternate scenario, if revenues do fall short, management indicated that they will press the cost levers even harder to offset some of that impact.
Capital Is The Key Catalyst For A Melt Up
The current Citigroup management plan is factoring in somewhat conservative assumptions around its capital targets. Firstly, it assumes that Basel 3, as proposed, will require it to hold more capital.
The Fed chair, Mr. Powell, made it clear that that US regulators are likely to significantly change their plan to require large lenders to hold more capital. This is very bullish for the large U.S. banks, and especially so for Citigroup.
However, the very near catalyst could be the Fed’s stress tests (otherwise known as “CCAR”) which outcomes are due to be released at the end of June 2024. These have the potential to materially reduce Citi’s capital ratios and release a significant amount of capital for share buybacks. Given Citi is trading at ~0.6x expected TBV by the end of 2025, this could be exceptionally accretive for shareholders.
Why am I constructive on the 2024 CCAR?
I will be the first one to admit that predicting CCAR outcomes for individual banks is challenging. The Fed’s models are essentially a black box for the large banks by design to ensure the banks are not able to manipulate the outcomes.
So why do I believe there is a high likelihood of a positive outcome for the 2024 CCAR cycle?
There are two key reasons.
Firstly, one of the key inputs for the CCAR calculation is Pre Provision Net Revenue (“PPNR”) which comprises the projections of revenue generated from Citi’s operations. All else being equal, stable and/or accrual business lines (such as Services) are given more credence in the PPNR projection compared to more volatile business lines such as Markets. The prior CCAR test was based on projections based on FY 2022 numbers, since then, Services revenue has grown by almost $3 billion in 2023 and projected to increase further in 2024.
Secondly, during 2023 Citi has completed the disposal of many of its international consumer bank franchises, which should also result in lower projected loan loss provisions under the CCAR methodology.
So overall, whilst cognizant of the inherent uncertainties, I am cautiously optimistic in respect of the 2024 CCAR cycle.
Final Thoughts
The sentiments around the Citigroup turnaround are certainly changing. More and more in the analysts community are recognizing that the new management is executing well and ahead of projections and expectations.
The capital trajectory is of paramount importance. If Citi can reduce its targeted capital ratios, then meeting its target of 11% to 12% becomes so much easier due to the denominator effect (capital is the denominator in the RoTCE calculation). This is a real game-changer, as it could also facilitate massive share buybacks near term. This is why the end of June is a critical time for Citigroup investors, and I intend to trade around this date as well.
If it is a positive CCAR cycle for Citigroup, the shares could easily melt-up.
I have been an early believer in Jane Fraser’s strategic overhaul and I believe that in the next 12 months, the success of the strategy should become much more visible in the numbers as well.
Credit: Source link