
webphotographeer
Hibbett, Inc. (NASDAQ:HIBB) today announced that JD Sports Fashion (OTCPK:JDSPY, JDDSF) has proposed to acquire Hibbett at a price of $87.50 per share to be paid in cash, representing a premium of 20.7% from the stock’s close price on the 22nd of April. The acquisition comes after relatively soft Q4 sales and a significant stock run. While the financials have performed well overall, I believe that the announced acquisition is promising for shareholders – I estimate the stock’s fair value to be less than the acquisition price through a discounted cash flow (“DCF”) model.
I previously wrote a write-up titled “Hibbett’s Undervaluation Has Been Corrected,” downgrading my rating on the stock as the valuation seemed fair after the significant stock run. Since, the stock has now appreciated by 29% compared to an S&P 500 (SP500) appreciation of 4% as the acquisition announcement sent the stock price near the announced acquisition value.
My Rating History on HIBB (Seeking Alpha)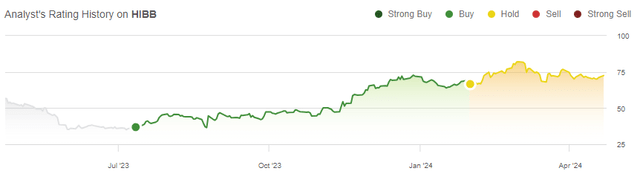
Announced Acquisition of Hibbett
As said, the announced acquisition by JD Sports includes a cash consideration of $87.50 per Hibbett share, representing a good premium compared to the stock price. The total enterprise value for Hibbett is $1.1 billion at the given acquisition price. No further share buybacks or dividends are to be done. Currently, the deal is expected to close in the second half of 2024.
The deal is still subject to Hibbett’s shareholders’ approval and regulatory approval. I don’t see any significant roadblocks in the finalization of the deal – the board of directors has already unanimously approved the deal, and in my opinion the cash consideration should be large enough for Hibbett’s shareholders. In the press release about the transaction, Hibbett’s Chairman of the Board of Directors, Anthony Crudele, commented the following:
“The transaction with JD Sports will create immediate, certain and substantial value for Hibbett stockholders while ensuring that our brands are well-positioned to continue to serve the customers and communities that have always been the central focus of Hibbett’s business. The Board unanimously agreed that this transaction is the best path to maximize the value of Hibbett, and I am proud of what this company and our outstanding team have accomplished for all stakeholders.”
Regulatory approval seems to be the only real concern in the transaction’s approval process. As the sector is filled with large direct & indirect competitors such as Foot Locker (FL) and Big 5 Sporting Goods (BGFV), I don’t believe that a regulatory block is likely to happen.
Hibbett Q4 Financials
After my previous write-up, Hibbett announced its Q4 results, showing revenues of $466.6 million, missing estimates by $10.9 million. Despite weaker-than-expected revenues, the announced GAAP EPS of $2.55 missed estimates only by $0.01. Compared to my expectations of a 5% revenue growth in FY2025, Hibbett also sees revenues flat to up 2% in the fiscal year, showing a slightly worse revenue trajectory than I anticipated with a potential uptick in demand. Continuing the good profitability, though, the EPS is expected at $8.00 to $8.75, compared to $8.17 in FY2024.
Compared to my expectations, the financial trajectory is overall progressing fairly well – I don’t see large changes in my fair value assumption for the stock. Profitability has been kept at a great level, being the main driver of the substantial share appreciation in recent times.
HIBB Stock – Updated Valuation
To evaluate the deal, I updated by DCF model. The model doesn’t need huge changes; I’ve slightly altered the growth downwards, but adjusted the cash flow conversion up a bit in the next couple of years. I keep the sustainable EBIT margin estimate at 7.9%, although the given FY2025 guidance could translate into a slightly higher margin.
With the mentioned estimates, the DCF model estimates Hibbett’s fair value at $74.78, around 15% below the proposed acquisition price; I believe that JD Sports’ proposed acquisition is a good deal for Hibbett’s shareholders. In my previous write-up, the DCF model estimated a fair value of $79.43 for the stock, mainly due to lower interest rates in January.
DCF Model (Author’s Calculation)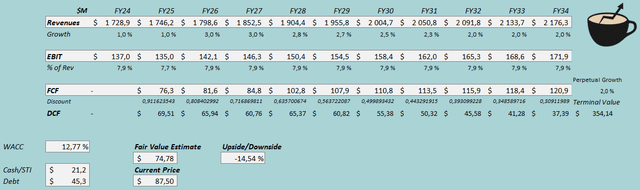
A weighted average cost of capital of 12.77% is used in the DCF model. The used WACC is derived from a capital asset pricing model:
CAPM (Author’s Calculation)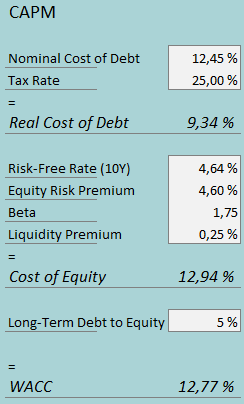
In the most recent reported quarter, Hibbett had $1.4 million in interest expenses. With the company’s current amount of interest-bearing debt, Hibbett’s annualized interest rate comes up to 12.45%. Hibbett’s debt-to-equity is very reasonable, and I expect a long-term debt-to-equity ratio of 5%.
For the risk-free rate on the cost of equity side, I use the United States’ 10-year bond yield (US10Y) of 4.64%. The equity risk premium of 4.60% is Professor Aswath Damodaran’s latest estimate for the United States, updated on the 5th of January. I still use the same beta of 1.75 as in the previous write-up. Finally, I add a small liquidity premium of 0.25%, creating a cost of equity of 12.94% and a WACC of 12.77%. The WACC is up from a previous estimate of 11.58% mainly due to a higher risk-free rate, but also due to lower debt & higher interest.
Takeaway
JD Sports announced to buy Hibbett at a valuation of $87.50 per share, and in my opinion, the deal seems likely to close. While Q4 financials have shown poorer-than-expected sales, Hibbett is still keeping up a great level of profitability, especially with a good FY2025 EPS outlook. Still, the announced transaction by JD Sports Fashion Plc for Hibbett, Inc. seems good, as the transaction sum is above my DCF model’s fair value estimate. I keep my rating at hold as the stock price already reflects the announced acquisition price.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link