
Henrik Sorensen/DigitalVision via Getty Images
In our last coverage of NextEra Energy Partners, LP (NYSE:NEP), we talked mainly about everyone’s favorite breakfast item. Toast.
Our take is that inflation will prove stickier than expected and even the normalization of the 3-month-10 Year Treasury relationship suggests a 5.5% 10 year note. If that outlook comes to pass, NEP and its distribution will be toast by year end 2024. In the alternative scenario, where we actually justify more than 175 basis points of cuts, because we hit a severe recession, expect the BB spread to blow out and once again, NEP distribution will be toast.
Source: Cry, Yell Or Fold?
Some readers have protested to such a forecast, as they feel we are being too negative. We would love to have a more optimistic bent, but neither risk-free rates, nor those high-yield ones, have any margin for error. Those are the worst times to buy.
How has that played out for NEP? Well, the stock price is down about 6%, and if you count the distribution, your total return was negative 3.7%. But we have some key developments here. Just see the second and third panels.

Earnings Update
NEP’s Q4 2023 was a mess and a miss. Adjusted EBITDA missed (about 3% lower than consensus estimates) and cash available for distribution (CAFD) really missed. Here, “really missed” means that we were about 40% lower than the lowest estimate for CAFD. The culprit was primarily wind segment results, with weaker generation across key subsegments. Even cash EBITDA, which disregards a few key detractors, was severely under estimates.
NEP threw another curveball for the bulls, with 2024 guidance in line with 2023 guidance.
NextEra Energy Partners is introducing December 31, 2024 run rate expectations for adjusted EBITDA in a range of $1.9 billion to $2.1 billion and cash available for distribution in a range of $730 million to $820 million reflecting calendar year 2025 expectations for the forecasted portfolio at year end 2024
Source: NEP Q4 2023 Conference Call Transcript.
All of that seemed a moot point for the bulls, and we think there were three reasons the stocks did not tank hard on the news.
The first being that on a medium term basis, we were still quite oversold. The stock was once an $85 stock. So when you have lost 70% of your value, investors tend to be more forgiving. The second reason is that the market was levitating as Powell loosened financial conditions with panache in November 2023. Broader market trends always influence the direction of most stocks, and it is hard for bears to make headway when the tide is rising. Finally, NEP did what seemed impossible to many. They raised the distribution.
Macro Update
As we showed up, both the 10 (US10Y) and 1 year Treasury rates have been screaming higher. NEP was first and foremost a baby of the ZIRP (Zero Interest Rate Policy) era and will be impacted by this. The Federal Reserve’s unofficial outlet, Nick Timiraos, confirmed that the market interpreted Powell’s comments correctly. Inflation is running hotter than expected, and rate cuts are unlikely this year. Even if we see one, it won’t be an aggressive rate cutting cycle just yet.
On the other side of the ledger, currently there is close to peak euphoria in the market, as evidenced by credit spreads. Our favorite metric here is BB and B spread. In other words, the spread between junk and terrible junk.
Daily Shot As Shared On X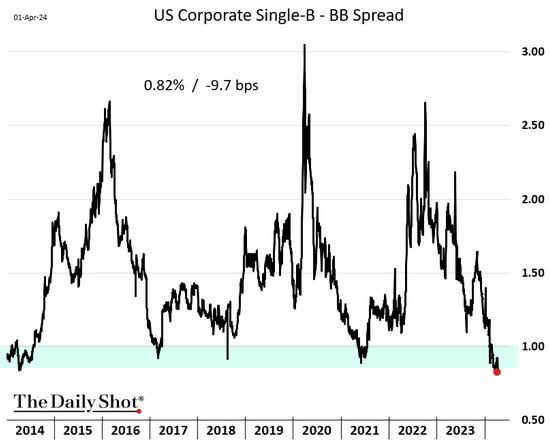
When it is this low, you know things can really blow.
Our Outlook & Verdict
It is difficult to find consensus estimates for NEP’s non-GAAP metrics, but the earnings direction is a fairly good guide. While the numbers differ, the direction is the same as CAFD. Just look at that deterioration over the last 3 to 6 months.
Seeking Alpha
NEP appears to be extremely cheap based on the distribution yield, but more appropriate valuations like EV to EBITDA show that the firm is fairly expensive. So far, it has been a game of poker where NEP raised the distribution even while falling flat on every real metric that counts. Stay tuned for Q1 results, expected pre-market on Tuesday, April 23rd.
The idea? Raise the distribution and raise the stock price. Then they can issue equity for those buyouts. Those buyouts total over $4.0 billion between 2026 and 2032. So debt won’t be an option and equity won’t be fun unless it is at twice the current price.
We think the distribution will be seriously questioned in the next few months, but even if it is not, anything that they do pay, subtracts from the terminal value. The company has delivered total returns of just 27.37% over the last decade, and that is inclusive of the distribution.

So we would not count on the current distribution becoming your annualized total return profile in the next 5 years. We rate NextEra Energy Partners, LP units a Sell and think there is substantial downside once the distribution is realigned.
Please note that this is not financial advice. It may seem like it, sound like it, but surprisingly, it is not. Investors are expected to do their own due diligence and consult a professional who knows their objectives and constraints.
Credit: Source link