MotionIsland/iStock via Getty Images
D.R. Horton (NYSE:DHI) has enjoyed an amazing run since we initiated our bullish view with a “Strong Buy” rating way back in October 2022. Since then, DHI has gained by 105.9% over 18 months, far exceeding the 36.1% gain on the S&P 500 Index (SP500) and the 79.0% gain on the SPDR S&P Homebuilders ETF (XHB) over the same period.
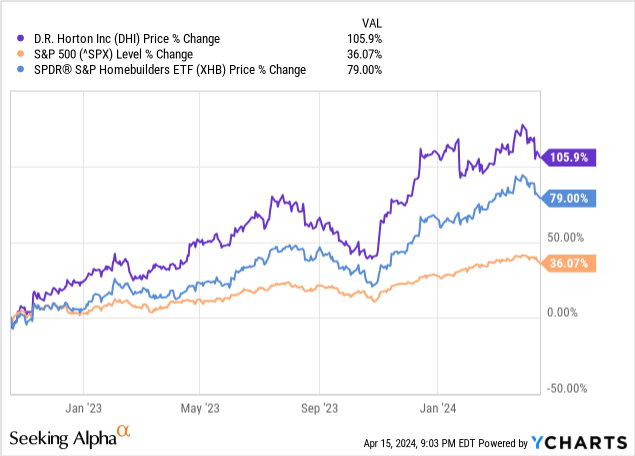
Our recommendation for homebuilders to outperform as the Federal Reserve was aggressively hiking interest rates, was overwhelmingly unpopular and dismissed by many readers. And it is understandable why our idea may seem too risky for some investors back then. Nonetheless, we held firm to our conviction that the acute housing shortage problem would support residential real estate prices and present meaningful upside potential for DHI’s earnings over the next few years. DHI’s homebuilding business was also fundamentally sound and grossly undervalued due to the overwhelming fear that persisted even after the market bottomed in October 2022.
What We Got Wrong
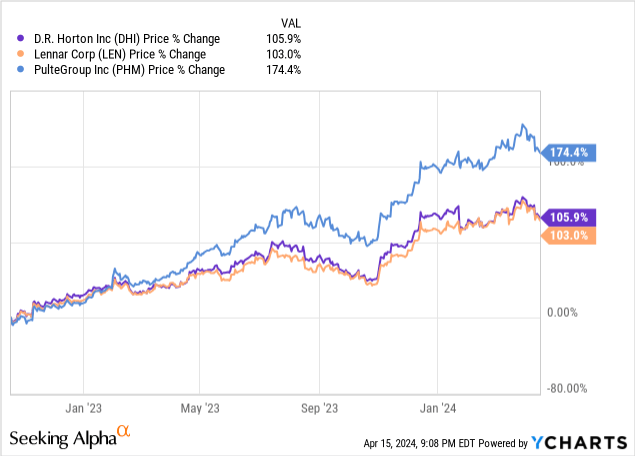
We selected DHI after a comparison with other large homebuilders including Lennar Corp. (LEN) and PulteGroup Inc. (PHM). Admittedly, this is where we missed. PulteGroup turned out to be the best performer among the group, delivering a staggering 174.4% gain over the period. Meanwhile, Lennar Corp’s performance was only marginally below DHI.
Looking ahead, we still prefer DHI’s target market, which is more skewed towards capturing entry-level home buyers. According to data published in DHI’s Q1 FY2024 investor presentation slides, 70% of homes closed by the company were priced under US$400k.
D.R. Horton Q1 FY 2024 Investor Presentation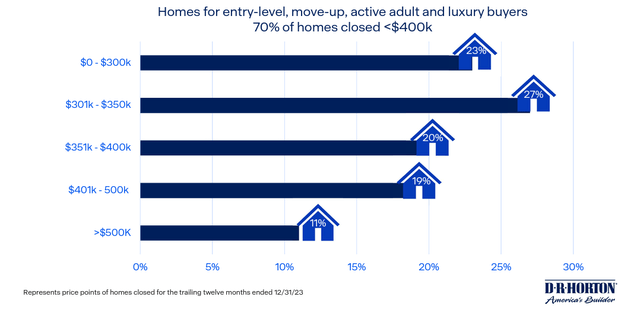
Our conviction remains unchanged that demand for new housing will be driven by inward migration of skilled workers and new household formation among the millennial cohort (age 25-35). Thus, we expect multi-family and low to mid-end single-family real estate will continue to enjoy robust demand given the low-to-middle income profile of these demographic groups.
No Change To Bullish Outlook
Today, the underlying factors driving the acute housing shortage remain largely unchanged, and we see little evidence to suggest that the relevant authorities are making any progress towards solving the problem.
Not only has inward migration picked up significantly during the Biden administration, which adds to immediate and projected demand for housing in the next few years. But pent-up demand for housing from regular household formation continues to remain strong. Various anecdotal evidence from industry observers indicates that buyers are simply holding back purchases in anticipation that mortgage rates will eventually moderate with rate cuts by the Fed.
Center for Immigration Studies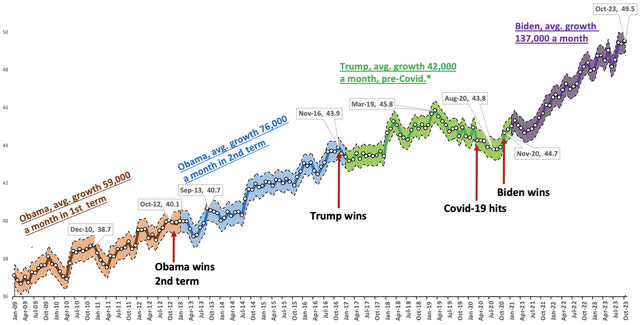
These factors driving our bullish thesis for homebuilders remain, while the industry continues to underbuild due to rising labour and material costs.
High borrowing costs have also disproportionately benefitted giant homebuilders like DHI with economies of scale and financial strength, allowing the company to gain market share from smaller builders.
Valuations Remain Compelling Relative To Broader S&P 500
Despite DHI’s impressive gains since we initiated our bullish view, the stock is still trading at an attractive TTM P/E multiple of just 10.9x at the time of writing. This, versus the S&P 500 Index which is trading at around 27.5x, not only presents an opportunity for investors to reduce risk by rotating out of tech-heavy exposure and into value, but we also think DHI provides much more upside potential.
Accordingly, we are reiterating our “Strong Buy” rating on DHI. We see the recent dip in the price action as an attractive opportunity for investors to accumulate.
Credit: Source link