George Pachantouris/Moment via Getty Images
Sometimes, it can be difficult to place a company. Some are just clearly attractive, while others are clearly unattractive. But every so often, there are firms that sit somewhere in the middle. One company that I could point to where this was the case, at least for me, is The First of Long Island Corporation (NASDAQ:FLIC). On the one hand, shares are incredibly cheap relative to book value. But on the other hand, there are other ways in which the business is unremarkable. It also has a high uninsured deposit exposure and recent financial performance has been anything but great. When faced with a mixed opportunity like this, the best thing I can do is to be cautious and err on the conservative side. And in this instance, that leads me to rate the enterprise a ‘hold’.
A bank I’ll pass on
According to the management team at First of Long Island, the institution dates back to its founding in 1927. Since its humble beginnings, it has grown into a multifaceted enterprise with 41 branch locations largely centered around the Nassau and Suffolk Counties of Long Island, and also throughout the five boroughs of New York City. Just like most any regional bank, the enterprise offers customers a wide array of services. Examples of the products offered include deposit accounts, loans for small and medium sized businesses, home equity lines of credit, residential mortgage loans, construction and land development loans, consumer loans, and more. The bank also has other services that it offers such as investment management services, trust services, estate and custody services, and more.
Author – SEC EDGAR Data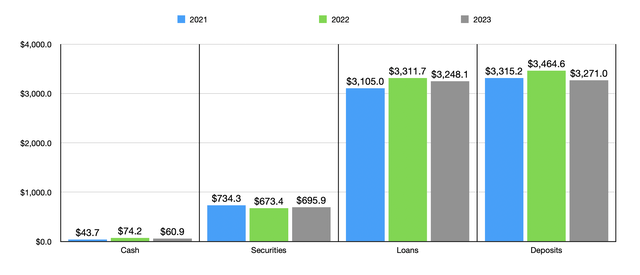
Recent financial performance achieved by the bank has been mixed and, in some respects, disappointing. Consider, for instance, the value of deposits on its books. Deposits grew from $3.32 billion in 2021 to $3.46 billion in 2022. After seeing a small decline in deposits in the first quarter of 2023, there was a rebound in the second quarter. But that was short lived. By the end of 2023, deposits had declined to $3.27 billion. The good news is that uninsured deposit exposure had fallen from 58% at the end of 2022 to 38% today. But that’s still above the 30% threshold that I set as a maximum for what I typically prefer in this space.
Author – SEC EDGAR Data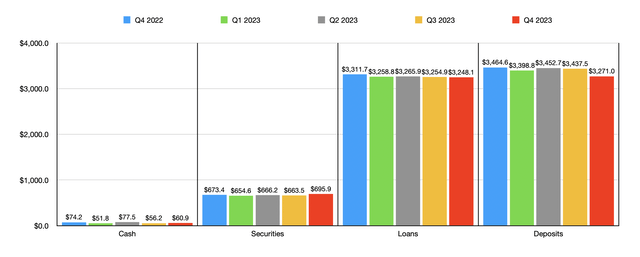
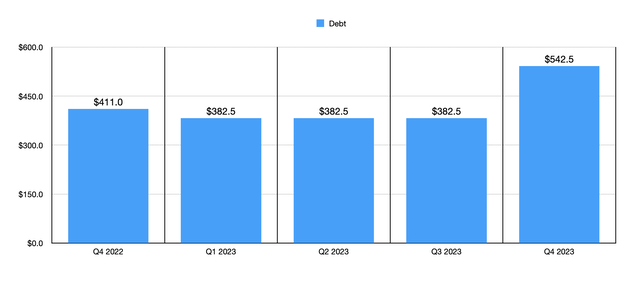
On the loan side, the picture has followed a similar trajectory. After rising from $3.11 billion in 2021 to $3.31 billion in 2022, loans dropped to $3.25 billion in 2023. There have been other ways in which the institution has shown mixed results. The value of securities on its books, for instance, did rise from $673.4 million in 2022 to $695.9 million in 2023. That’s a positive. But that’s still down from the $734.3 million that the bank had in 2021. The value of cash has remained in a fairly narrow range, particularly over the past few quarters. But debt has actually increased. Back in 2021, it came in at $311.3 million. By the end of 2023, it had grown to $542.5 million. And the vast majority of that increase from 2021 occurred from the third quarter of last year to the final quarter.
Author – SEC EDGAR Data Author – SEC EDGAR Data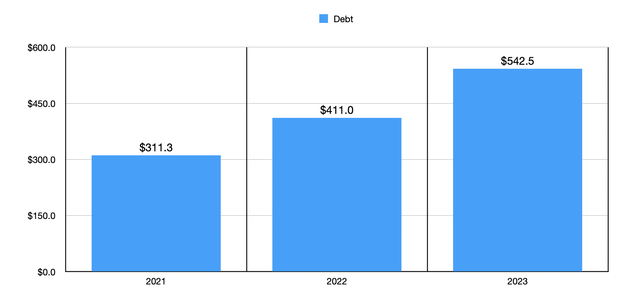
This pain on the balance sheet has proven instrumental in impacting the income statement for the bank. After seeing net interest income rise from $106.8 million in 2021 to $113.4 million in 2022, it plunged to $87.2 million last year. That drop was driven in part by a decline in the value of loans and higher interest payments needed to be paid out to depositors in order to keep their funds within the bank. The rise in debt also has proven to be a problem here, especially when you consider the role that higher interest rates can’t play on the picture. As the chart below illustrates, other profitability metrics for the bank have not fared particularly well. Non-interest income declined by nearly half from $11.9 million in 2022 to $6.3 million in 2023. And net profits plunged from $46.9 million to $26.2 million.
Author – SEC EDGAR Data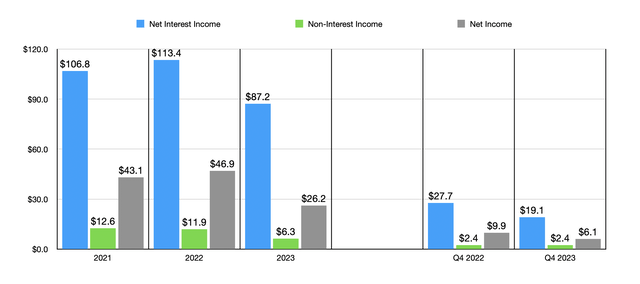
Almost without exception, the data that we have covered up to this point has been disappointing. But the upside to this is that the price to book multiple of the bank is quite low. Unfortunately, the book value per share has jumped all over the place, with no clear trend over the past several quarters. That is likely factoring into the overall price to book multiple of 0.63, as would be the other weak spots for the institution. In fact, as part of my analysis, I compared First of Long Island to five similar firms. As you can see in the chart below, it has the lowest price to book multiple at this time. Keeping all else the same, this can be a net positive because it could indicate significant upside potential. But when we start looking at the picture in other ways, things start to look less than ideal.
Author – SEC EDGAR Data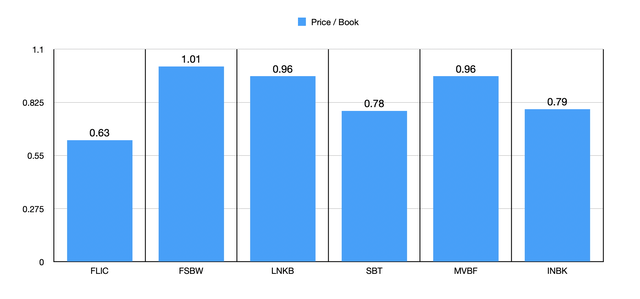
In the next chart, you can see the price to earnings multiple, not only for First of Long Island, but also for these same five companies as before. With a reading of 9.1, the institution is basically at the high end of what I typically prefer. There are some banks that still trade at levels of between 6 and 9 and that’s where I feel most comfortable. As the aforementioned chart illustrates, only two of the five companies that I compared it to have price to earnings multiples lower than what it does. So that places it around the middle of the pack.
Author – SEC EDGAR Data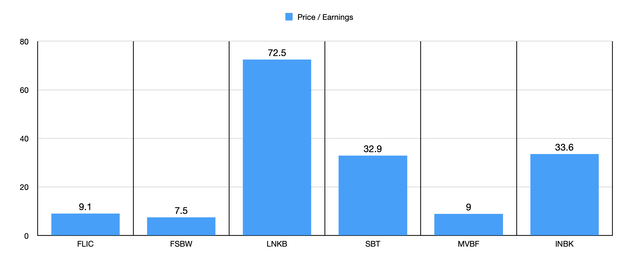
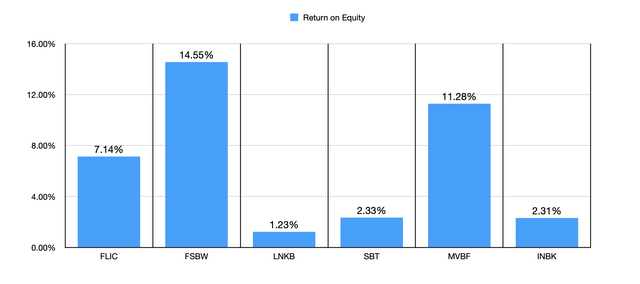
Of course, sometimes institutions deserve to trade where they do. And one thing that we can look at to see whether or not this is the case would be its return relative to other measures. Return on assets, for instance, are particularly low for the bank at only 0.62%. As the first chart below illustrates, this is not the lowest of the group by any means. But I have seen multiple institutions with readings of 1% or higher. There’s also the topic of return on equity. And once again, First of Long Island seems to be around the middle of the pack on this front.
Author – SEC EDGAR Data Author – SEC EDGAR Data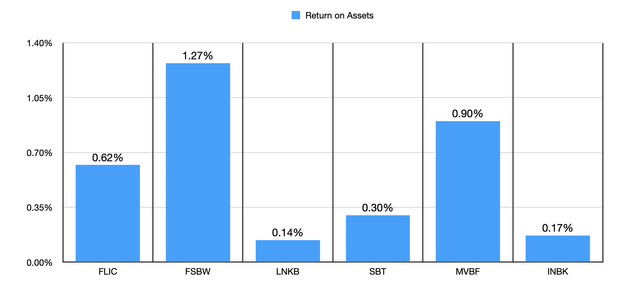
Takeaway
Operationally speaking, First of Long Island is fairly unremarkable. What I do like about the bank is that shares are very cheap relative to book value. And relative to the other firms that I compared it to, certain metrics place it in the middle of the pack or thereabouts. But when you start looking at other factors, it becomes quite clear that the picture is problematic. Despite how cheap the stock is, the large number of issues like declining deposits, high uninsured deposit exposure, declining loan values, and a drop in revenue and profits, leads me to believe that a ‘hold’ rating only makes sense at this point in time.
Credit: Source link