
Emanuel M Schwermer/DigitalVision via Getty Images
Freeport-McMoRan (NYSE: NYSE:FCX) is up almost 50% from its late-November 2023 lows, when we last recommended investing. The company has been supported by strong global economic strength and strength in metal demand. That’s combined with continued concerns about a copper shortage. As we’ll see throughout this article, the company runs a strong investment, but its $70 billion valuation isn’t justified.
Freeport-McMoRan 2023 Accomplishments
The company had a strong 2023, with continued growth supported by hefty investments.
Freeport-McMoRan Investor Presentation
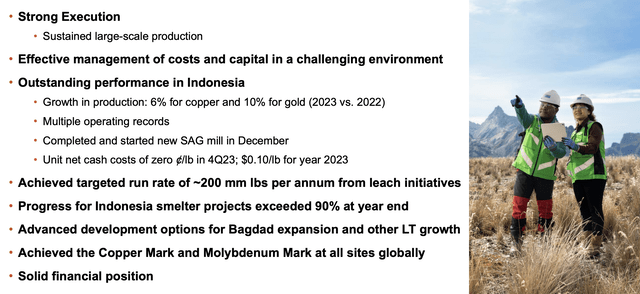
The company saw strong Indonesian performance, with 6% copper and 10% gold production growth. The company continued to set operational records, and the company finished the year with $0 / pound in net cash costs in the last quarter. That’s supported by the massive gold production of the asset. The company is continuing to build new smelter projects and expand here.
The company’s new leach initiatives have achieved run-rate of 200 million pounds / year in new production and the company is working to expand that.
Freeport-McMoRan Investor Presentation
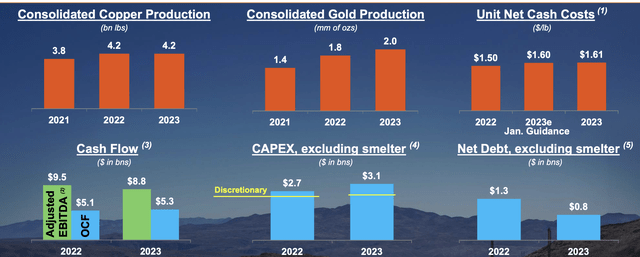
Across the company’s business the company saw 4.2 billion pounds of consolidated copper production and 2 million ounces of consolidated gold production in 2023. Net cash costs sat at $1.61 / pound counting that rising gold production, indicating that overall costs rose for the company. That means the gold growth didn’t help margins.
The company saw $5.3 billion in operating cash flow, up from $5.1 billion, but with even faster growth in capex, FCF dropped to $2.2 billion a 3% FCF yield on its current market cap. Net debt is virtually 0, but with the company’s FCF low, it’ll be tough to continue driving strong returns.
Freeport-McMoRan Business Positioning
The company’s overall business did close out the year fairly well.
Freeport-McMoRan Investor Presentation
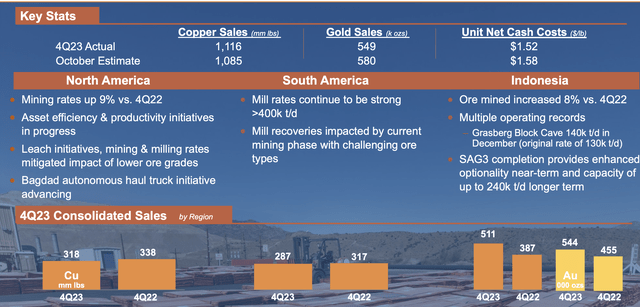
Net cash costs were slower, with copper sales several % above October estimates. Gold sales dropped ~5%, but net cash costs dropped as well. The company has continued to focus on efficiency by region, but it also continues to be carried by substantial strength from its Indonesian assets where ore mined has grown.
Freeport-McMoRan Investor Presentation
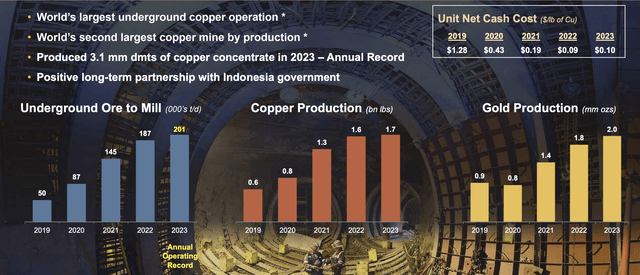
The company currently runs the largest underground mine in the world at Grasberg with 1.7 billion pounds in annual production and gold production ramping up. That has enabled cash costs to drop substantially. However, as seen with the YoY copper, we see Grasberg underground ramp up as nearing the end.
The company is looking for longer term licenses, but this is a valuable and very profitable asset. Looking at what Indonesia is doing with dominating the nickel markets, and the smelter requirements the last time, we see this as being a long-term risk to this mine.
Freeport-McMoRan Growth Plan
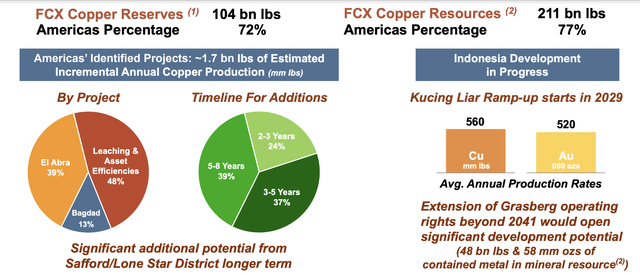
The company is continuing to chase growth with its impressive reserves, but it only has incremental opportunities.
Freeport-McMoRan Investor Presentation
The company has 4.2 billion pounds of copper, and has identified projects it hopes to provide ~1.7 million pounds in incremental projects. That doesn’t count Kucing Liar, a new Indonesian project that could potentially lead to very substantial gold production. However, it depends on a rights extension for true value and won’t start until 2029.
Even optimistically, the company’s 2030 production will hit ~6.5 billion pounds in copper production. That doesn’t count a decline in existing assets. The company’s reserves are ~25 years of production and the company’s forecasts show modest production increases.
Freeport-McMoRan Cash Flow
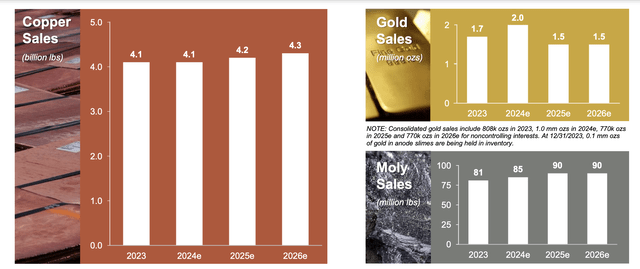
Most importantly for the company’s assets its 2023 gold sales are expected to spike in 2024 in a higher price environment before declining substantially.
Freeport-McMoRan Investor Presentation
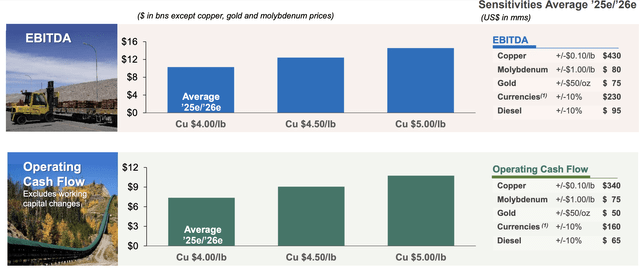
The company expects 4.1 billion pounds of copper and 2 million ounces of gold. It’s being helped by higher gold prices at almost $2350 / ounce. That’s a strong spike from the start of the year, with around 15% growth in gold prices. The company’s operating cash flow growth is $50 million per $50 / ounce price change. That means ~$350 million in operating cash flow growth for 2024.
Freeport-McMoRan Investor Presentation
The company’s 2025/2026 forecast even in a higher priced environment is important to our thesis that the company is overvalued. Current copper prices are $4.25 / pound. That means operating cash flow will be ~$8 billion. The company’s non discretionary capex is ~$2.6 billion and its true overall capex is $3.8 billion. That means ~$4.2 billion in FCF, a 6% FCF yield.
That’s a reasonable yield but it’s not the yield to drive long-term shareholder returns. This is also for the years 2025/2026 so already 1/2 years from now. That weak cash flow in the future shows the company has a minimal growth forecast.
Thesis Risk
The largest risk to our thesis is copper prices with a looming shortage. Large amounts of money is going into subsidizing clean energy, which could also help cause copper demand to spike. That combination, with higher prices, could improve Freeport-McMoRan’s cash flow, and make the company a justified investment at its valuation.
Conclusion
Freeport-McMoRan has an impressive portfolio of assets. The company has seen strong appreciation in its share price to a market capitalization of $70 billion and its continued to fund its small dividend. There’s no denying that the company continues to run a tight ship, and it’s continued to focus on growth for the long run.
The company’s 2025/2026 forecast at current copper prices is a FCF yield at a mere 6%. There’s a chance that copper prices can appreciate substantially, however, any downturn in what’s a historically expensive market could change that substantially. Given the volatility of commodity prices, a marginal growth forecast, and a high share price, we recommend against investing in Freeport-McMoRan right now.
Credit: Source link