
PORNCHAI SODA/iStock via Getty Images
Investment action
I recommended a buy rating for Five Below, Inc. (NASDAQ:FIVE) when I wrote about it the last time, as I believe growth momentum has continued into 4Q23, which sets up a very good outlook for FY24. Based on my current outlook and analysis, I reiterate my buy rating. I don’t see any fundamental weakness from the recent earnings update that suggests FIVE is off track in meeting its FY26 EPS target and FY30 store opening targets. I do acknowledge that the shrink headwind (theft in this instance) is a surprise, but that is not an unmanageable situation. With the measures implemented to manage shrink, I am positive that FIVE can resolve this, and we should see positive results in the coming quarters.
Review
FIVE reported 4Q24 same store sales growth [SSSG] of 3.1%, driven by transaction growth of 3.9% and an average ticket size decline of 0.8%. The strength in transaction growth was notable and supports my previous view that momentum has flowed into 4Q23 given that this is the fifth consecutive quarter of positive transaction growth from new and returning customers. Although if we split the performance by months, it implies that January (2% growth) saw sequential deceleration, I don’t think this implies anything major given that January last year was a very tough month with better weather. FIVE also saw gross margin expand by 94bps to 41.2%, driven by lower freight costs but offset by higher than expected shrink headwinds. Combining this headwind with higher incentive compensation, it led to a FIVE underperforming consensus on EBIT margin (20.1% vs. 20.7%). FIVE EPS also came in lower than at $3.65 vs. $3.78.
While I like this set of results, the market clearly didn’t. My assessment is that the market was really shocked by the shrink headwinds, which honestly was quite a surprise to me as well. For context, shrink headwind was 160 bps, and this was higher than expected from FIVE’s most recent physical audit, which was just completed in January. Back in January, management noted that the shrink rate was in line with what was observed earlier in the year. This guide-and-under deliver basically opened up the pandora box as the market starts to be more concerned about more shrink headwinds in FY24 (consensus downgraded their 1/2Q gross margin estimates immediately after results). This also leads to doubts about whether FIVE actually has measures in place to manage this shrink headwind. I am willing to give FIVE the benefit of doubt that this is manageable and am looking forward to positive results from the reduction of self-checkout (switch to assisted self-checkout or over-the-counter), along with other measures at high-shrink locations. Also, from a more general perspective, shrink is not an issue isolated to FIVE; even Walmart (WMT) faced this issue and has seen success in managing it. In terms of expectations, note that the FY24 guidance does not include any expected improvement in shrink, and if the shrink mitigation efforts are successful, there could be upside to the FY24 guidance.
FIVE also continues to drive forward its growth strategies that support the medium-to-long-term growth outlook (shrink is a near-term headwind, in my opinion). The company intends to convert an additional 200 stores during FY24, bringing the year-end penetration closer to approximately 70% of their comp base, and as of 4Q23, around 700 stores have been converted to their new Five Beyond store format, which accounts for more than 50% of their comp store base. Historically, Five Beyond stores saw a mid-single-digit lift in sales during the first year after the switch and achieved chain average performance in the second year. Hence, I am positive that management is executing on this front to convert stores. The important aspect to point out is that the uplift in comp sales is coming almost entirely from higher transactions, which speaks really well of the quality of FIVE’s expanded offerings (in other words, this seems to be a structural driver to sales uplift). In addition, FIVE is targeting 225–230 new stores in FY24, which, at the midpoint, would be a 15% increase in the number of stores. This is consistent with the company’s average growth rate from FY18 to FY23. After implementing specific technological platforms and streamlining their real estate review process, FIVE has made significant improvements to their store opening process, which should make the rollout go off without a hitch from an executional perspective. In order to facilitate further expansion, FIVE has also leased space from defunct retailers and experimented with non-traditional sites, such as shopping centers that feature a grocery store as an anchor tenant. If FIVE continues to open approximately 270 stores annually, it will surpass its goal of 3,500 stores by FY30.
All in all, while share prices in the near term could continue to be volatile from the shrinking impact, my stance is that the longer-term story remains intact. Firstly, I expect shrinking headwinds to improve, and we should start to see positive results over the coming quarters. Secondly, Five Beyond conversions are gaining traction and were a major driver of transaction growth in 4Q23, which should provide top-line upside in FY24. Lastly, progress in store openings remains on track, setting FIVE well to meet FY30 targets at this pace.
Valuation
Author’s work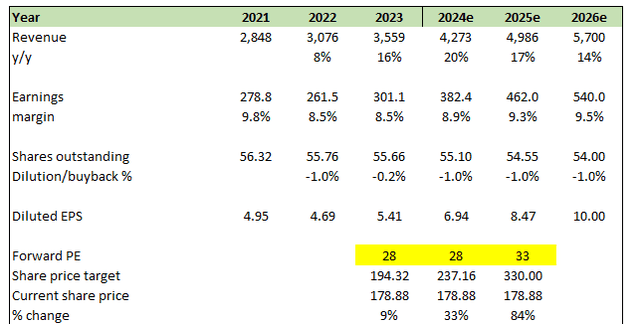
To better reflect how I think the share price will move forward, I modeled out the in-between years from FY24 to FY26, unlike my previous update, which only focused on the potential upside in FY25 (based on FY26-guided EPS). Broadly, my main assumption is the same, in that I still expect EPS to hit $10 in FY26, as I don’t see any fundamental weakness in the recent earnings that suggests FIVE would not be able to do so. However, I think it is fair to think that valuation will be pressured in the near term as the market holds a conservative view on the shrinking headwind. It will probably take a few quarters for this headwind on valuation to fade, as the market needs time to ascertain whether the improvement is intact. Walking through the model, I believe FIVE is on track to meet the $5.7 billion sales target in FY26, and margins should gradually expand back to 9.5% (near 10%) as shrink headwinds tap, coupled with operating leverage from revenue growth. I also modeled out my expectation that management will continue to buyback shares at a historical rate of 1% per year. With these assumptions, I think $10 is plausible. As for valuation, I expect forward PE to stay pressured at the current 28x (which is also the low end of its historical forward PE bend) and only inflect back to its average of 33x in FY25 when the market is convinced that shrink headwind is gone and FIVE is on track for growth and margin expansion.
Risk
A repeat of the shrink headwind incident could really impair management’s creditability, putting further pressure on the stock’s valuation as the market takes on a more aggressive stance on modeling margin expansion in the near term. Macro headwind is another risk that should be considered. While FIVE benefits from the trade down motion, a severe recession would heavily impact consumer willingness to spend, thereby impacting FIVE’s growth potential.
Final thoughts
My recommendation is a buy rating for FIVE. Fundamentally, FIVE delivered solid transaction growth and continues to execute on its growth strategy with store conversions and new openings. While the stock price may be volatile in the near term due to the expectations around shrink headwinds, my view is that the long-term story remains intact. FIVE should be able to manage shrink and benefit from Five Beyond conversions and store expansion, putting it on track to achieve its FY26 EPS target. Valuation may be pressured in the near term, but the stock is expected to rebound as the shrink issue improves.
Credit: Source link