
Oselote/iStock via Getty Images
We believe that P10 (NYSE:PX) is misunderstood and significantly underfollowed since the company’s October 2021 IPO on the NYSE. A recent unrelated scandal involving PPP loans has caused further distortion and investor apprehension causing share prices to decline over 27% in the last 6 months.
At today’s price, we now think PX presents significant upside as the newly appointed CEO from Goldman Sachs, Luke Sarsfield, takes the wheel to execute a prudent growth strategy in a highly fragmented and target rich M&A environment in the niche private equity segment of lower and lower-middle markets.
Most investors don’t realize that P10 is largely employee-owned enterprise, with 100+ P10 employees owning 54% of the company shares. These employees also fund roughly 1% of the GP commitments to their funds as part of P10’s funding, making for a good alignment of interest all the way around. We think the current price of $8.14 per share which is less than 10x current year estimates of around $.86 per share, PX offers 2x upside from here based on our target price estimate of $27 per share in 2027.
P10 Shares have declined by over 27% over the last 6-months (as of March 22, 2024)
P10 Stock Price over last 6-months (P10 )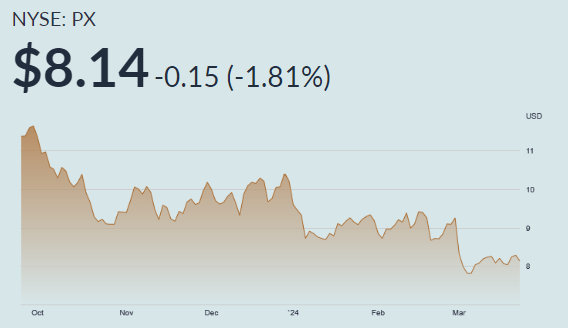
Investment Thesis
P10 is an alternatives asset manager with a highly scalable AUM platform across the middle and lower middle markets. Total fee-paying AUM (“FPAUM”) just hit $23.3 billion.
First, it is important to understand how P10 generates their revenue, which is through mostly contractual management and fees based on capital committed to their funds. The typical commitment period is usually between ten and fifteen years. This is very important for P10 shareholders to understand because they do not generate lumpy fees such as “carried interest” that can be very volatile from year to year and vintage to vintage. With P10 owning a split interest in the steady stream of recurring management fees of these funds, and not the lumpy carried interest, the outcome for P10 shareholders is a stable cash flow stream of revenue that grows with additional. The other benefit of this arrangement is allowing the carried interest to stay with investment professionals. In our eyes, this equates to a great alignment of interest because the ultimate and less predictable profits remain an incentive for the investment professionals to achieve.
Second, P10 grew through acquiring management fee interests over time through acquisitions. P10 management used their P10 stock as a currency, issuing P10 shares as a partial form of payment for the interest. Based on their latest disclosures, P10 has stated that one hundred P10 employees today have a collective equity interest of nearly 54% in the company (recent 10-K Annual Report filed on March 13, 2024). We feel this is strongly a good thing for P10 to be over half owned by its employees. After all, who would be more motivated to grow the value of the company. If the share price doesn’t work out, the employees will be just as disappointed as their shareholders. In addition, for further alignment of interest, P10 employees have additional capital to their investment vehicles as part of P10’s General Partner commitment, which is typically 1% of total commitments of each fund. We think this provides strong alignment all the way around with P10 employees truly eating their own cooking.
P10’s platforms: RCP Advisors, TrueBridge, Bonaccord Capital Partners, WTI, FivePoints Capital, and Hark Capital.
We believe that can execute further growth of earnings through the continued organic growth of fee-paying assets and the opportunistic acquiring more middle market and lower middle market platforms.
The newly appointed CEO, Luke Sarsfield, appointed to the role in October 2023 is an exceptionally strong leader for the company. Sarsfield has been appointed and is taking over the reins when the current market cap is well under $1 billion. In our opinion, the hire of an executive with Sarsfield’s credentials at this valuation is about as good as it gets for P10 shareholders.
Sarsfield has a highly skilled background and deep industry rolodex as a career FIG (Financial Institutions Group) banker serving in numerous investment banking leadership roles at Goldman Sachs. During his 20+ years Goldman alum, he served as Global Head of the Financial Institutions Group, and more recently as Global Co-Head of Goldman Sachs Asset Management.
Second, P10 made a second appointment of another Goldman Sachs alum in March 2024 to bolster the growth team, Arjay Jensen who is serving as Executive Vice President, Head of Strategy and Mergers and Acquisitions.
Ultimately, we believe that the P10 has appointed high caliber leadership with deep industry rolodexes stemming from one of the top tier financial institutions group on Wall Street, Goldman Sachs. If we are correct, we think P10 is poised to begin a multi-year growth spree in the asset management world that has already proved to be high scalable and will ultimately give PX shareholders fast-growing revenue, operating profit, cash flows, and a stock price.
Private Markets Industry Present Long Term Tailwind
Over the last decade, private market investing has become considerably popular. For example, the trending phase for Wall Street has become “private credit”. It is a place where many participants are finding undervalued and underserved segments compared to the public markets. According to McKinsey & Company’s 2020 report McKinsey’s Private Markets Annual Review, the private markets have grown steadily since 2010 with assets under management growing 2.7x from $2.4 trillion in 2010 to $6.5 trillion in 2020. According to PitchBook Data Inc.’s US PE Middle Market Report, Q1 2021 during roughly the same period (2010 to 2020), lower middle market deal value is up 2.5x while venture capital is up 4.9x.
This all bodes very well for P10 shareholders who have multiple revenue streams across the middle and lower middle market, as well as venture and secondaries funds that all participate in these private markets.
To make sure the latest trends are still intact at the moment, we can confirm these fund flows with the latest conclusions from the 2023 McKinsey Global Private Markets Review, where they concluded that since 2017, assets under management have grown at an annual rate of nearly 18% brining private markets AUM total to $11.7 trillion as of June 30, 2022.
Early History
P10 is an alternative asset manager. They are a leading multi-asset class private market solutions provider in the alternative asset management industry. They provide investors access to private equity, private credit, venture, and impact investing across many strategies.
The company rose from the bankruptcy ashes as a non-operating OTC listed company, formerly Active Power Inc with a sizeable federal NOL tax asset of $270+ million. Then in 2017/2018, management entered the private solutions space in with the acquisition of RCP Advisors, a crown jewel investment platform active in the lower middle market private equity segment.
RCP’s early history dates back to 2001 and is a lower middle market private equity firm that invests capital across funds-of-funds, secondary funds, and co-investment funds. As part of the transaction, RCP principals received 44+ million shares of P10 common stock. This means that post-closing, RCP principals owned around 49.5% of P10’s outstanding shares. Put another way, this first acquisition with RCP instantly made legacy P10 shareholders the minority and made RCP the largest stockholder of P10.
We think this early structure provides a strong alignment of interest with employees and shareholders. In the following six years in continued execution of their growth strategy, P10, further expanded its portfolio with the acquisitions of Five Points, TrueBridge, and Enhanced.
In October 2021, P10 priced its initial public offering of 20 million Class A common stock shares at $12.00 per share moving from an OTC-listed company to an NYSE listed stock. At the time, P10 had about $19 billion in FPAUM at the time. Today, P10 has FPAUM of $23.3B, an increase of $2.1B, or 10% from 2022. Since 2018, FPAUM has grown at an impressive 16% CAGR.
FPAUM over time (P10 SEC Filings)
Business Model
P10 structures, manages and monitors portfolios of private market investments. P10’s investment offerings include: specialized funds and customized separate accounts within primary investment funds, secondary investments, direct investments and co-investments.
At the moment, with the current portfolio of investment offerings, P10’s asset classes span the middle and lower middle markets across:
- Private Equity
- Venture Capital
- Impact Investing
- Private Credit
Why is P10 Attractive for Shareholders
P10 offers an attractive arrangement for their platforms. P10 eliminates many perceived challenges facing other publicly traded alternative asset management firms. First and foremost, the earnings volatility due to lumpiness of carried interest is eliminated for P10 shareholders. With this, so are many of the tax complexities from the ownership of management and advisory fees that come from carried interest in publicly traded partnerships that plagued all the early PE firms that went public as partnerships. Finally, the potential misalignment of interest between investment professionals and the shareholders is greatly eliminated as the investment professionals have skin in the game funding some or all of the GP commitments of the funds. In our opinion, this makes for a truly great alignment of interests all the way around.
Deep industry relationships are the core of P10. They are growing with every additional platform they acquire starting with RCP Advisors over 7 years ago as the first platform. Second, they offer their fund investors unique investment access and structures, proprietary data analytics, and portfolio monitoring and reporting capabilities.
P10 offers three different vehicles for investors: Primary, Direct & Co-Invest, and Secondaries:
P10 SEC Filings (P10 SEC Filings)
Primary – $13.5B in FPAUM at 2023 Year End
Primary solutions are offered across private equity and venture capital, diversifying investments across asset classes with defined strategies. Primary funds are offered for commingled investment vehicles and customized separate accounts. P10 offers access to relationship-driven VC and lower-middle market sectors.
Direct and Co-Investments – $8.3B in FPAUM at 2023 Year End
Direct and co-invests are offered across all of P10’s solutions where they invests alongside leading GPs in secured unitranche, second lien, mezzanine loans, and equity. P10’s GP and vast industry relationships allow them to see deal flow with attractive economics. Direct and co-investment opportunities are offered across commingled funds and customized separate accounts.
Secondaries – $1.5B in FPAUM at 2023 Year End
Secondaries are only offered through commingled vehicles and offered in private equity solutions and cover exclusively lower-middle market funds. P10 leverages RCP’s position in the industry and their fund manager networks and deal flow.
(as of 2023 Q4)
P10 SEC Filings (P10 SEC Filings)
A Non-Factor Weighing on the Share Price
In early 2024, P10’s stock price has been under pressure, going even under $8 per share with concerns of dark clouds of potential litigation related to allegations of misuse of PPP loans by Crossroads Impact Corp. P10 co-founder Robert Alpert was a co-controlling shareholder of Crossroads at the time when its subsidiary Capital Plus issued $7.6bn of PPP loans.
The SBA filed a 2022 report titled “How Fintechs Facilitated Fraud in the Paycheck Protection Program” which directly names Capital Plus numerous times. However, because Crossroads is a separate operating organization and P10 has no direct involvement, we anticipate that this noise will eventually pass, especially with newly appointed leadership at the helm.
We arrived at this conclusion with the latest commentary from management mentioned on the Q4 earnings call on March 6, 2024. P10 CEO Sarsfield addressed this issue proactively outlining that the above mentioned transaction was completed under all of the appropriate governance controls. For the avoidance of doubt and to fully clear the air in the room, Sarsfield clearly communicated to investors that P10 did not invest any capital into Crossroads and specifically outlined that a committee of its independent directors commissioned third party law firm Wilkie, Farr, and Gallagher to conduct a review of the transaction and no deviations from established governance provisions were found.
Attractive Valuation
We think that P10’s two closest competitors are Hamilton Lane Inc (HLNE) and StepStone Group Inc (STEP).
HLNE is another alternative private equity company with a similar model where they service clients in the private equity world and provide follow on services with managing and monitoring client portfolios. They cover both private markets funds and direct investments.
STEP is also similar where they work in tandem with their clients to develop and build private markets portfolios. However, they have a broader offering of investable asset classes, that cover private equity, private debt, infrastructure, and real estate asset classes.
SEC Filings (SEC Filings and Oppenheimer Estimates)
Both of these peer companies trade at significantly higher multiples of EBITDA and Revenue than P10 at the moment. We conclude that 8x Forward revenue and 15x forward EBITDA are reasonable valuation metrics for the peer set. P10 currently trades at 4.5x current year revenue and 9.9x current year EBITDA.
To arrive at our 2027 year-end price target of $27 per share, we think P10 will be trading at 8x forward year 2028 revenue and 15.9x forward year 2028 EBITDA of $212 million.
Our 5-year P10 Proforma Model:
Valuation Framework (Underwriting)
We think that P10 shares are a 2x from today by 2027 based on continued execution of the business, modest recovery in the PE fund raising business, and normalization of the EBITDA margins to 50% levels.
Estimating a $27 stock price by 2027 based on very reasonable valuation metrics at 15.9x EBITDA and 8.6% EV to FPAUM looking out at 2027YE – 2028 levels.
Potential for faster PX share price appreciation should Sarsfield and team find additional acquisition candidates at attractive multiples. Strong balance sheet at 2.1x net debt to EBTIDA means P10 can buy back shares and pay the 1.8% dividend yield to P10 shareholders.
Potential Risk
We think the biggest risk is a downtrend in US and global investor allocations to private markets. If there were to be a large and prolonged slowdown of fresh funds into these segments, it would certainly harm the management fees associated with P10’s platforms. However, we think this is a low probability given the depth of these markets and investor’s growing appetites for exposure and investment performance that is outside of the global stock indices.
All data indicates that private equity, private credit, and venture capital markets are here to stay for the long haul. They have grown in to formidable and attractive asset classes for investors seeking exposure to diversify their portfolios. P10’s risk is being overweight poor performing funds or poor performing sub asset classes. However, given their early track record we think they have thus far done a great job of showing their skill in acquiring and partnering with blue chip private equity franchises in the lower and lower middle markets.
Conclusion
We believe the recent selloff presents a very attractive entry point for investors with a long-term time horizon.
P10 has come a long way over the last 7 years. Today, P10 has 250+ employees, including 108 investment professionals across 11 offices located in the United States. We see the potential for low double digit FPAUM growth in 2024-2027 coupled with growth investments made in the platform that are one time in 2024 shrinking EBITDA margins to the mid 40% range. We see that normalizing back to 50% over time and when applying very reasonable valuation metrics, see a $27 share price coming in 2027.
Bottom line, we think this is very attractive return for a high-quality asset manager with long-term, contracted fee arrangements, growing platforms, and now a superb management team now at the helm.
Credit: Source link