
kyoshino/E+ via Getty Images
Thesis:
Normally, I don’t go anywhere near any company that has fraud allegations or any difficulty filing their required financial disclosures. B. Riley (NASDAQ:RILY) has both. On March 15th, RILY missed the 15-day grace period to file its 10-K. While this delay is concerning, there are some mitigating issues that should be pointed out. Plus, I believe the company has a reasonable explanation for the delay, and the filing should be coming soon.
RILY’s core business, BRS, B. Riley Securities, is a broker/dealer primarily focused on small-cap companies. It offers research, sales and trading, and investment banking. The company has acquired a liquidation/auction business (Great American) and a wealth management business to complement its other BRS businesses.
B. Riley Financial Overview (December Investor Day)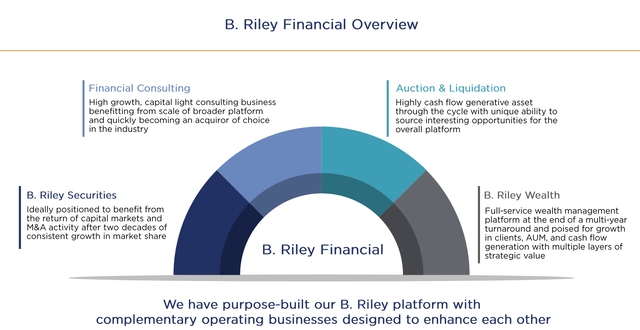
The company has leveraged its work and connections in the small-cap space to make partial or whole principal investments in a variety of small-cap companies. As a result, it is an unconventional business structure with many parts that require some work to understand, but the legwork is worth it in my opinion.
B. Riley Principal Investments (December Investor Day)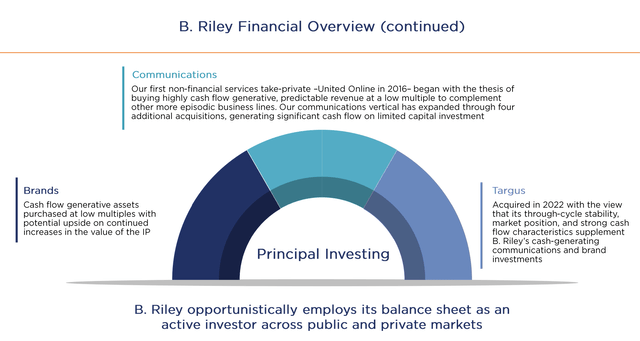
I have little experience with the company. I typically do not look at B. Riley or the types of companies it banks. I tend to avoid companies that have always been small/micro-cap (rather than fallen former large caps like PTON) unless I know them or their management extremely well. Tiptree (TIPT) is one such company that gets a small cap exception.
Although it’s now a small cap itself with a $600 million or so market cap (as of Thursday, March 28th), the company had a market cap near $2 billion in July. The main reason for the drop is an unfortunate association with one individual, Brian Kahn, who led a hedge fund called Prophecy Asset Management, which failed in 2020. However, from what I see, unless a fairly prominent law firm has completely missed the mark, the company has no nefarious connection to any wrongdoing attributed to Kahn or Prophecy.
Who is Brian Kahn?
You can get background on Kahn here. The quick and skinny is Kahn started involvement in Prophecy Asset Management in 2015. Prophecy was supposed to be a “first loss” provider that gave capital to third-party firms. These firms were supposed to post the first 10% loss in the portfolio, protecting Prophecy’s investors. In reality, it appears that Kahn, who was CEO of FRG (Franchise Group) directed most investments (without any third party or first loss capital) and lost a ton. A Prophecy co-founder has pled guilty to Securities Fraud Conspiracy.
I recommend reading the link that details the actions it looks like Kahn engaged in. Please see below for RILY’s history with Kahn and FRG.
History of Vintage Relationship (December Investor Day)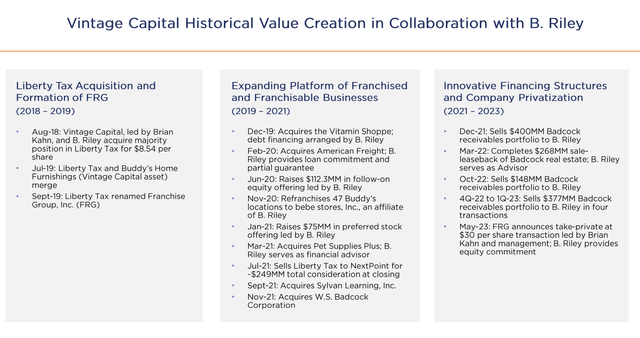
If its pre-2023 dealings with Kahn were the extent of the connection, I don’t think there would be much blowback to RILY. The problems stem mainly from its involvement in FRG, which RILY banked, and where it owns 31% of the equity post supporting the Kahn-led MBO (management buyout) of the company last summer.
FRG Transaction (December Investor Day)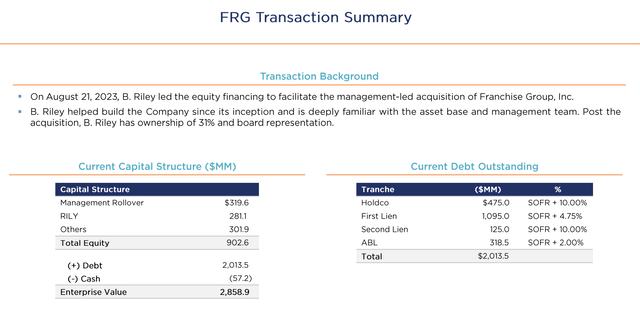
There is a considerable amount of controversy surrounding this MBO. At the time of the deal, several bulls on FRG considered the deal price too low, considering it was about 40% below where FRG had traded a year earlier. RILY bears contend that the group overpaid for the business. Combining that latter thought with RILY borrowing money to fund its participation in the deal and the controversy surrounding Kahn and some have speculated that FRG can sink RILY.
Whatever you want to say about Kahn and RILY connections to him, I don’t think the FRG deal will sink the business. In fact, I think it has a shot at being a pretty big win for the company.
The Virtues of FRG:
During an investor day in December, the company attempted to lay out the SoTP (sum of the parts) for FRG.
FRG Business Lines (December Investor Day)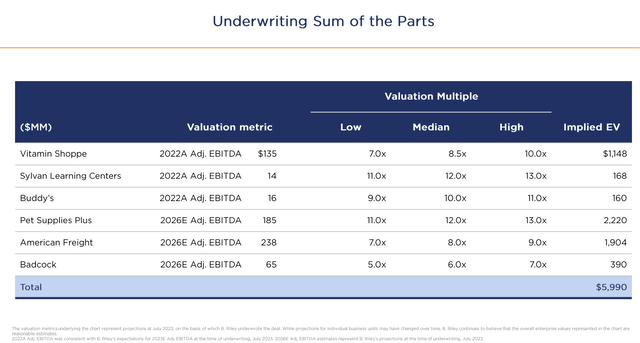
I don’t love this SotP presentation. It uses actual EBITDA from 2022 for three line items (even though the presentation was made in December 2023) and it uses estimated 2026 EBITDA for three other line items. That invites skepticism. However, that does not render it completely worthless.
As you can see above, the company believed that Sylvan Learning Centers, which FRG bought in 2021 for $81 million is worth $168 million. Well, in February 2024, the company announced the sale of Sylvan. While the terms were not released, a $185 million price was leaked. This price hasn’t been confirmed yet, but I’d be surprised if the price for Sylvan turned out lower than $168 million.
Vitamin Shoppe and Pet Supplies strike me as fairly easily sellable too. Both businesses are already pretty big wins for FRG, which bought them for $208 million and $700 million respectively.
FRG’s last 10-K listed operating income of $107 million for Vitamin Shoppe and you can see above that RILY listed $135 million of EBITDA for the period. Since the stores are almost all company-owned, let’s assume cap ex equals depreciation so $107 million approximates cash flow. That means FRG bought Vitamin Shoppe for less than 2x cash flow. That last 10-Q for FRG showed that organic revenue is still growing at Vitamin Shoppe. Therefore, selling that business for around $1 billion, if not slightly higher, does not strike me as a huge reach.
The Vitamin Shoppe (December Investor Day)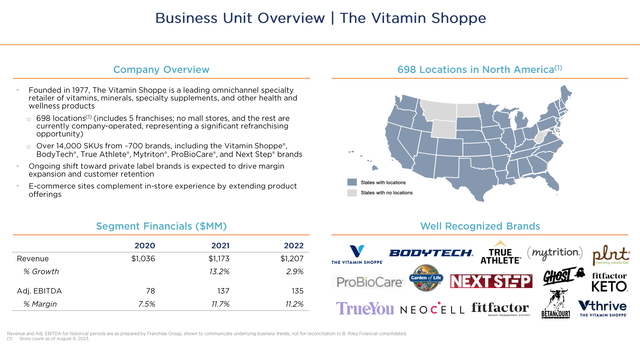
Pet Supply is growing quite a bit. The business had 500 stores (~300 franchised) when FRG bought it in January 2021. By December 2022, it had 675 stores (443 franchised). As of the December investor day, the company had grown to 718 stores and 481 franchises. This store count is consistent data from the second quarter last year, where sales had grown over 10% for the first six months over the prior year period. For fiscal year 2022, Pet Supply did $81 million of operating income and $115 million of adjusted EBITDA
Pet Supplies Plus (December Investor Day)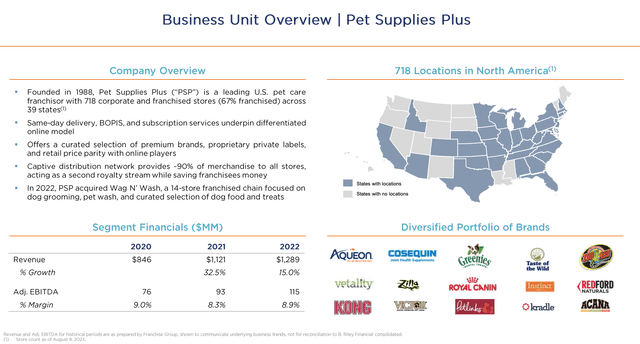
Given this growth rate, the company projecting $185 million of adjusted EBITDA for 2026 doesn’t strike me as crazy. Franchise models often sell for low-double-digit EBITDA multiples. Let’s take 11x, the low end of the range the company assumed above to be conservative. Assuming $115 of EBITDA grew just 10% inline with revenue for 2023 to $127 million. 11x gets you a value of ~$1.4 billion right now. Again, I think that is really conservative given the growth rate and the opportunity to sell the 200+ company-owned stores to franchisees.
Taking those three businesses’ value together gets you to ~$2.6 billion pre-tax versus the company buying FRG for $2.9 billion over the summer. One can argue that the other three businesses aren’t worth much, but less than $300 million strikes as a stretch. At the very least RILY’s investment is extremely unlikely to be impaired.
The company hired Sullivan and Cromwell to investigate the company’s relationship with Kahn. S&C is a very prominent, very serious law firm. They determined that the company didn’t do anything improper in relation to the buyout of FRG or its interaction with Kahn for the deal.
Delayed Filing:
Unfortunately, that investigation took a lot of time and attention. The company is blaming it for a delayed 10-K filing, whose 15 grace period ended on Friday. The stock has bounced around a bunch since that delay. I do not think there is much to worry about for a couple of reasons.
One thing I take comfort in is that the company had to submit the audit for its broker/dealer to the SEC already. I would think that we would have heard if the SEC had a problem with that audit.
The broker/dealer and wealth management are big pieces of the operating profit here.
Capital Markets and Wealth Management (December Investor Day)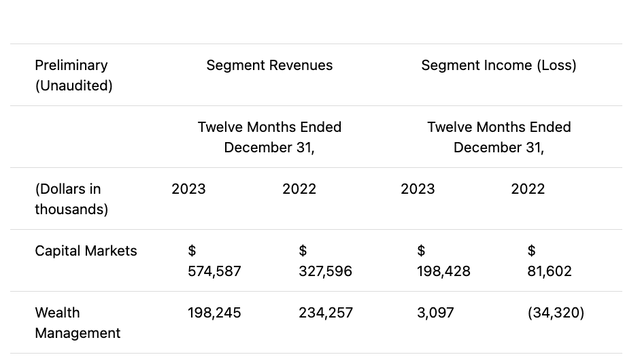
The company also said in its Q4 press release “The Company is compiling the required information to complete its Annual Report and it does not anticipate any significant changes to the financial results for the fourth quarter and year ended December 31, 2023 as disclosed.”
In other words, if there is a major problem here, the company was not aware of it at the end of March. Audits can be delayed for all sorts of reasons. Perhaps the auditor wanted another review of the Kahn situation before they signed off on anything.
Another thing I take comfort with is that the lenders on the Nomura term loan is really the only group that could force major problems on the company for delayed loan. That group has already given the company a pass on the delayed filing. I haven’t heard anything out of that group and they have no incentive to cause RILY any problems over a delayed audit. Moreover, this group, which sees much more in-depth data on business lines and cash flows than we do, was comfortable enough with the stability of the business to allow a dividend payment. Albeit the dividend was only $.50/share instead of $1, the fact that they allowed cash out the door to equity holders rather than forcing all cash to pay down the loan says a lot, in my opinion.
B. Riley Debt Stack (December Investor Day)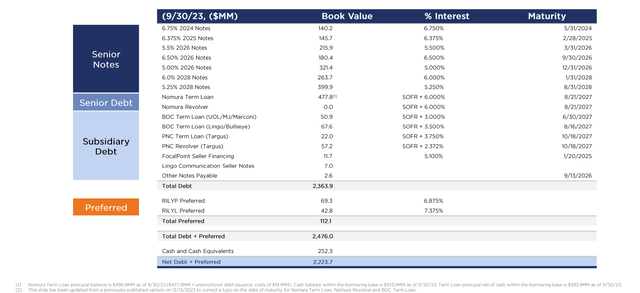
The exchanges could delist companies for not filing timely financials, but that takes a while. I would expect the audit to be done before that becomes a serious concern.
Lastly, while Sylvan is an announced sale, the company hasn’t announced anything regarding Vitamin Shoppe or Pet Supply. I was just using those businesses as relatively easy sales for high values to show that FRG shouldn’t be considered this albatross for the company. Indeed, it could generate quite a bit of value for the company.
Potential Asset Sales at B. Riley:
The company did announce that Great American, its liquidation and auction business.
Auction and Liquidation Business (December Investor Day)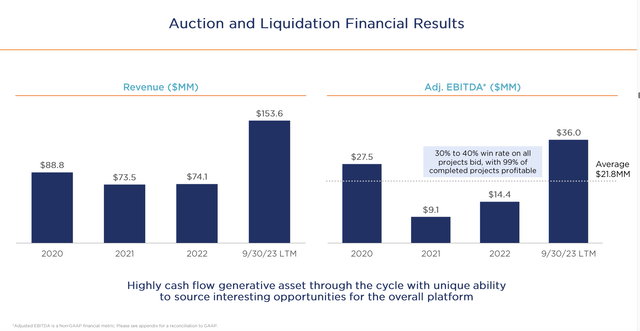
This business is lumpy but potentially worth a lot to a strategic acquirer looking to leverage the core competencies with a lending or real estate restructuring business. Given its capital light business, I can easily see this business garnering 10x LTM EBITDA. $350 million would allow the company to pay down a chunk of its term loan and also retire a lot of its near-term maturity (the next 12-month’s worth) baby bonds.
Haters of Cash Flow:
I have seen short reports that dump on RILY’s investments. The communications business, which includes Magicjack and United Online etc, gets particular attention as a buggy whip type of business. I hate to break it to the haters, but it’s all a matter of price. If you tell me there’s a high-cash generative biz that is declining 10%/year, but I can buy it for ~2.5x EBITDA, I’d probably take a look as I only need it to stay in biz for a little about 3 years to get my cash out and then everything is gravy. That’s basically RILY’s Communications business. If you look at the cash invested versus the cash pulled out below, I imagine most people wouldn’t mind having some investments like that.
Communications (December Investor Day)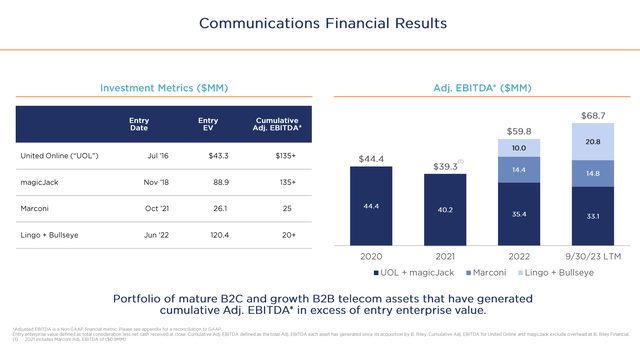
The company expects United Online, Magic Jack and Marconi to keep throwing off cash for the next 5+ years. It expects Lingo and Bullseye to grow revenues.
Mistakes:
That’s not to say that every deal is a winner. Targus looks terrible at the moment. The company paid $250 million for it in late 2022, which was supposed to be 5.2x EBITDA. Unfortunately, Targus performance plummeted almost immediately after the deal. The company thinks it can make it back. If it can’t, it will be a hickey. Time will tell there. The company has also lost on Babcock & Wilcox (BW), where it owns a ~30% stake (27.45 million shares) and where Kenny Young, RILY’s president, is also the CEO. I actually think BW will be fine if it can address some near-term liquidity issues. It’s not particularly overleveraged and it’s a real business. It just needs to square away its balance sheet.
Valuation:
Since there are so many different pieces here, I think you have to look at a SotP (Sum of the Parts). Overall operational EBITDA is quite strong here.
B. Riley Consolidated EBITDA (December Investor Day)
Even in the covid year, the company did over $300 million of operating adjusted EBITDA. EBITDA for the full year of 2023 was about equal to the TTM as of the end of Q3 at $368 million. The consolidated numbers don’t really tell you much. You have to look at the business lines. Even that requires some guesswork.
B. Riley Segment EBITDA (December Investor Day)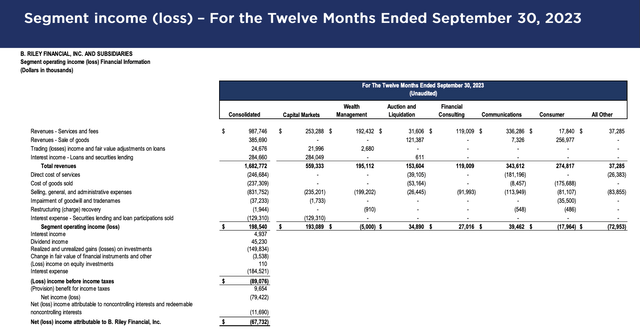
The capital markets business is the hardest to value. The assets walk out the door every day, and we’ve seen these types of businesses go away overnight. However, despite everything thrown at the company, they are still underwriting deals, advising companies, and trading with clients. It’s hard to pin down book value for the capital markets business alone. Looking at comps like Moelis (MC), Evercore (EVR), PJT Partners (PJT), and Perella Weinberg (PWP), they tend to trade at 7-15x EBIT. If we apply 7x to $200 million, we get $1.4 billion.
Wealth management is tough here. Despite having $24 billion aum (assets under management), the business has never really made money.
B. Riley Wealth Management (December Investor Day)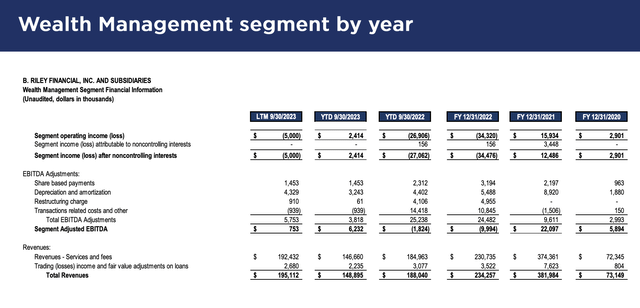
These businesses typically trade as a percentage of aum, often 1-2%. Putting 1% on 24 billion gets you $240 million. I think that’s probably fair.
Auction and Liquidation was discussed above. I think that business can garner at least $350 million in a sale. It’s lumpy but a great business that I can see a lot of potential suitors for.
Auction and Liquidations by Year (December Investor Day)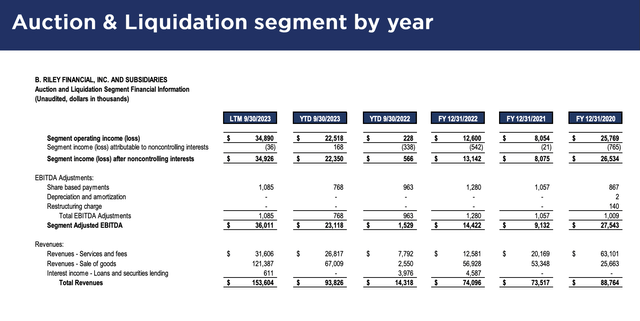
Financial consulting is a steady-eddy business that is highly cash generative. I see this business trading at 10-12x EBITDA. Let’s call 2023 an outlier (to the high side) and say steady state EBITDA is $25 million. At 11x it’s a $275 million business.
Communications is just a cash cow. Let’s say that only gets 3x EBITDA. At about $70 million of EBITDA, let’s use round numbers and value it at $200 million.
The Consumer Brands have a bunch of different ownership percentages as outlined below. Like communications, the cash flows have been generally quite good and fairly steady.
B. Riley Brands (December Investor Day)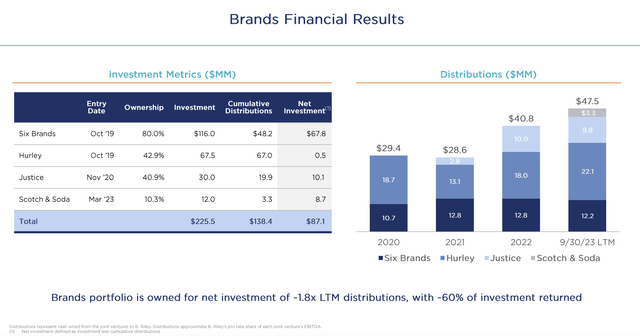
I think it’s fair to say the Consumer Brands should be worth at least what was paid for them in a sale, which is $225 million. I’ll call Targus a zero for simplicity sake, with just the debt for it going away. These are part of a $1.6 billion investment portfolio.
B. Riley Principal Investing (December Investor Day)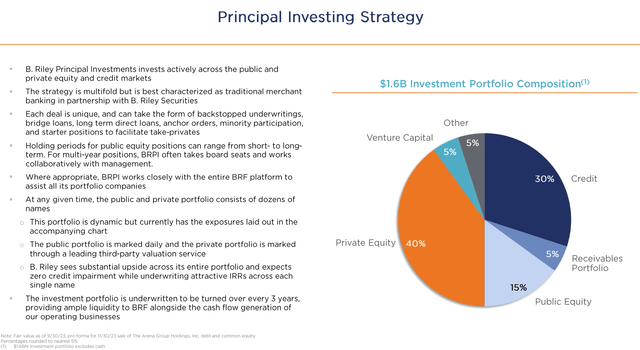
The biggest piece is private equity, of which the company’s $281 million equity stake in Franchise Group is the biggest component. A $201 million loan to the GP of Franchise Group deal makes up the biggest component of the credit book. That loan is backed by the GP’s equity stake in Franchise. As I demonstrated above, I think the company will at least get its investment back, thereby satisfying the Nomura loan, $475 million. I think there is upside to this but let’s be conservative here.
If one wanted to be super conservative, I think you could call the public equities a zero. That implies a 15% loss to the portfolio and a $1.26 billion of value. The brands are embedded in this so I’ll incorporate that value into the $1.26 billion.
Putting that all together.
| Segment | Value |
| Capital Markets | $1.4 billion |
| Wealth Management | $240 million |
| Auctions and Liquidations | $350 million |
| Financial Consulting | $275 million |
| Communications | $200 million |
| Investment Portfolio | $1.26 billion |
| Subtotal Enterprise Value | $3.725 billion |
| Term Loan (minus the Targus piece) | $550 milion |
| Notes Payable | $1.668 billion |
| Preferred | $112 million |
| Cash | $234 million |
| Equity Value | $1.629 billion |
| Equity Value/Share (Using 31 million shares) | $52.50/share |
I believe that there is upside to this number and it explains why the stock was between $40 and $60 from June through October.
Risk:
None of the above work is worth anything if there is some horrendous fraud here or some deep nefarious ties to Brian Kahn emerge. The company seems to think that the audit will not differ materially from the Q4 numbers and the Sullivan Cromwell investigation absolved the company of any wrongdoing tied to Kahn. That could all change. There is also the risk that the audit is not done in time to satisfy lenders or the exchange, leading to a default or a delisting respectively.
Moreover, the M&A environment might not produce the values I’ve ascribed to the business that could be/are being sold. If Great American can’t be sold or can’t fetch over $300 million, that will impact valuation here a decent amount.
Conclusion:
This is not a typical investment for me at all. When I hear the word fraud or see a structure that is a big tangle of businesses with a fair amount of leverage, I usually run the other way. However, I think most of the bears here are focusing on the wrong things or looking at the businesses the wrong way. There is around 70% short interest here. If the company can file its 10-K soon and get off some asset sales, I can see a vicious short squeeze.
There is a decent amount of potential value here. If you’re afraid of the equity, longer-dated call spreads can make sense here. Volatility is high but the stock realizes that volatility. As of the time of this writing, $20-40 call spreads to July probably cost around $3.50 maximum. That’s around a 6:1 payoff. I think that’s worth risking some money you’re willing to lose.
Credit: Source link