
pluem05/iStock via Getty Images
Synopsis
VSE Corporation (NASDAQ:VSEC) is a company that provides aftermarket distribution and maintenance, repair, and overhaul services for air and land transportation assets. VSEC’s past revenue has demonstrated strong recovery and growth after COVID-19’s impact. In addition, margins have been expanding annually as well. For 4Q23, it continued to report strong year-over-year growth, and margins have remained robust as well. Looking ahead, the divestiture of its federal and defense segments will allow VSEC to focus on its core competencies and strengthen its balance sheet. In order to capture growth, it has strategically acquired Adesto and Turbine Control Inc., both of which are expected to bolster VSEC’s growth outlook. However, due to a lack of margin of safety in its share price, I am recommending a hold rating.
Historical Financial Analysis
VSEC’s historical financials have demonstrated strong revenue post 2020. In 2020, revenue was down 12% due to the impact of COVID-19 and the divestiture of Prime Turbines. In 2021, revenue recovered and grew 13.5% due to improved demand in aviation’s end markets. In 2022, it reported growth of 26.5% year-over-year, driven by distribution contract wins and the acquisition of Global Parts. For 2023, take note that revenue excludes revenue from discontinued Federal and Defense Segment operations. Revenue growth reported was 28.54% driven by the acquisition of Desser Aerospace, strong execution on distribution contracts, growth in repair capabilities, and improved demand.
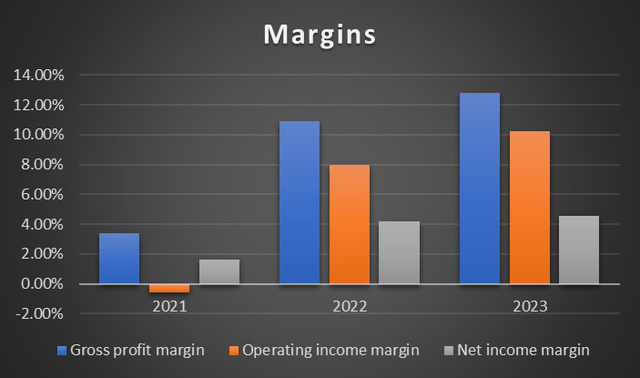
In terms of margins, it has shown strong expansion since 2021. In 2021, the reported gross profit margin was 3.43%, the operating income margin was negative, and the net income margin was 1.65%. By 2023, gross profit margin expanded to ~12.7%, operating income increased to ~10.2%, and net income margin grew to ~4.5%. Operating income margin expansion was driven by favorable shift in sales mix and increased pricing in both the Aviation and Fleet segments.
Author’s Chart Author’s Chart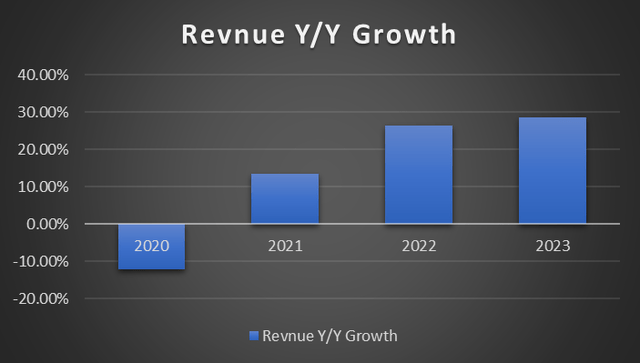
4Q23 Earnings Analysis
VSEC reported strong 4Q23 results, as total revenue was up 37% to $235.3 million. Its revenue segment can be broken down into Aviation and Fleet with Aviation forming the largest share of total revenue at 65.3%. For the quarter, Aviation segment revenue was up 43.4% to $153.7 million, while operating income for the segment was up 52.3% to $18.7 million. The strong revenue growth was driven by increase in MRO services, the acquisition of Desser Aerospace, and strong execution in its distribution awards. The strong growth in Aviation’s operating income was driven by increase in MRO market share, improved price, and product mix. The acquisition also contributed to the growth in operating income.
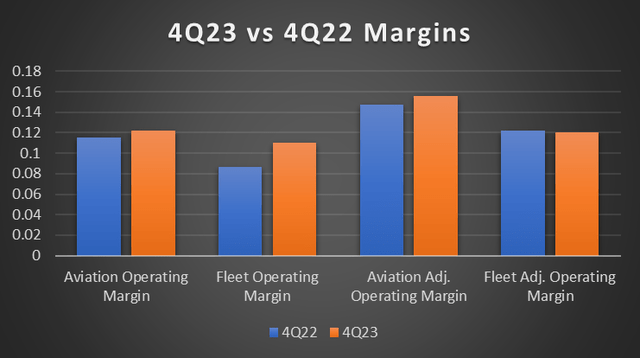
Moving onto Fleet segment, revenue increased 25.9% to $81.6 million for 4Q23. The robust growth was driven by strong e-commerce growth and commercial fleet sales. Operating income grew 59.5% to $8.9 million, and this growth was driven by better customer and product mix. When looking at Aviation and Fleets operating margin and adjusted operating margin, it remained robust year-over-year. In fact, some of the margins expanded modestly year-over-year.
SEC Fillings Author’s Chart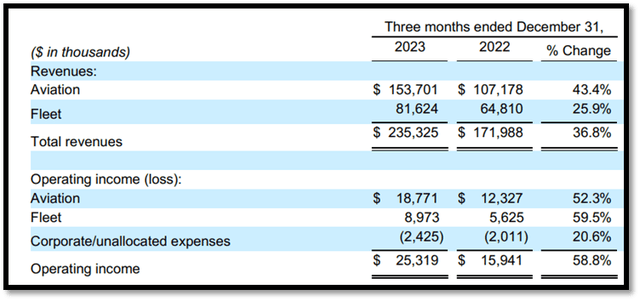
Divestiture of Federal and Defense segment
In 4Q23, VSEC fully divested its federal and defense segment [FDS]. The sales of the operating assets under this segment were completed in February. This divestiture is part of VSEC’s transformation plan, as it is planning to streamline its business operations, focus on its core competencies, which are aftermarket services, and to bolster its balance sheet.
Based on the following table, FDS’s operating income has been contracting year-over-year since 2020. In 2020, it reported an operating income of $26.3 million. By 2022, it reported an operating loss of $805 million. The loss was attributed to a shift in its contract mix towards more cost-plus contracts vs. fixed-price contracts. Cost-plus contracts, in general, generate lower profit margins vs. fixed price. In addition, revenue in 2022 grew a modest 4% due to decline in U.S. Army work as a result of program completions offsetting gains from the U.S. Navy.
Annual Report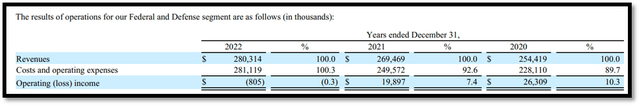
Acquisition of Adesto and Turbine Control Inc
In 2023, VSEC completed the acquisition of Adesto. Adesto is a company that specializes in distribution and maintenance, repair, and overhaul [MRO] services. This acquisition aligns well with management’s plan to strengthen its services in the aerospace market.
Apart from Adesto, VSEC also announced that it would acquire Turbine Control Inc. [TCI]. Just like Adesto, TCI’s business also focuses on aviation aftermarket maintenance, repair, and overhaul support services. This announcement further pushed the point that management is really focusing its business plan to strengthen its services in the aerospace market. TCI has a strong presence on multiple engine platforms, including those engines that will be used in next-generation aircraft. Such a strong market presence indicates that TCI has an important role in the aviation industry, making this acquisition an excellent fit for VSEC. Management is confident that TCI’s OEM partner-focused strategy complements well with VSEC’s long-term OEM support strategy. This acquisition is anticipated to strengthen VSEC’s service offerings and bolster its growth outlook.
Relative Valuation Model
VSEC operates in the diversified support service industry, and it specializes in aftermarket products and services for the aviation and fleet segments. In terms of growth outlook, VSEC is in line with its peers, as its forward revenue growth rate of 6.54% is closely in line with its peers’ median of 6.93%.
Moving onto profitability margins, VSEC underperformed in terms of net income margin TTM. It has a reported net income margin TTM of 3%, which is lower than peers’ median of 6.73%. However, it did so with a much lower gross profit margin TTM of 9.85% vs. peers’ median of 37.32%.
Currently, VSEC’s forward P/E is trading higher than its peers’ median. VSEC’s forward P/E ratio is 19.99x vs. peers’ median of 15.94x. In addition, it is trading higher than its own 5-year average of 17.71x. Although its net income margin TTM is lower than peers’ median, it did so with a lower gross profit margin TTM. In addition, given that its forward revenue growth rate is in line with its peers’ median, I argue that it should be trading at its peers’ median P/E of 15.94x. By doing so, it ensures that VSEC’s valuation is conservative.
The market revenue estimate for 2025 is $1.15 billion, while the 2025 EPS is $4.90. Given the growth catalyst discussed above, these estimates are reasonable as they reflect the same perspectives. By applying 15.94x to VSEC’s 2025 EPS estimate, my target price for VSEC is ~$78.08, which represents a modest upside potential of 2%.
Author’s Valuation Model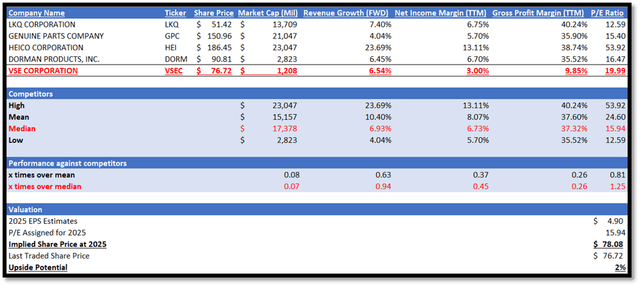
Risk
The upside risk to my hold recommendation is regarding the potential opportunity cost associated with missing out on VSEC’s growth. As discussed above, VSEC’s strategic acquisitions of Adesto and TCI are set to enhance its service offerings, which is expected to bolster its future growth. In addition, the divestiture of the loss-making FDS segment could lead to more streamlined operations and improved profitability. If future margins were to expand and surpass peers’ median, we could potentially see the market readjust their expectations for VSEC upwards.
Conclusion
In conclusion, VSEC’s past four years of revenue have shown strong recovery and growth after COVID eased. Apart from strong revenue growth, its margins have expanded year-over-year as well. For its most recent quarter, both revenue growth and margins continued to be strong.
Looking ahead, the acquisition of Adesto and the planned acquisition of TCI are anticipated to strengthen VSEC services’ capabilities in the aerospace market. In addition, in 4Q23, it fully divested its FDS. This divestiture is expected to streamline its business operations and allow VSEC to focus on its aftermarket services. Despite all the tailwinds, my target price indicates a modest upside potential that is in the single digits. Therefore, I am recommending a hold rating for VSEC at the moment.
Credit: Source link