
bjdlzx
Equitrans Midstream (NYSE:ETRN) shareholders can now see why EQT (EQT) spun off the midstream company and then later sold the remaining shares. The Mountain Valley Pipeline proved to be a huge anchor to company improvements. Now, after everything this company has been through, EQT proposes to acquire Equitrans Midstream. The .3504 shares of EQT offered were at a slight premium to the price of Equitrans Midstream before the announcement. But the market quickly dropped the price of EQT to largely eliminate that premium. Still, this may be the best way for Equitrans shareholders to go.
All the delays and court cases have raised the cost of the Mountain Valley Pipeline’s project to at least $7 billion. Now this depends of course upon your source. But there is general agreement that the pipeline cost far more than was originally proposed thanks to all the delays.
The new cost was not anything that was close to justifying the project in the first place. On the other hand, now that it is built, all the challenges in building the pipeline mean that competition for the same service area is not likely to exist. Therefore, the pipeline could become a very valuable business “down the road”.
Stock Price History
Time has not treated this investment idea very well.
Equitrans Midstream Common Stock Price History And Key Valuation Measures (Seeking Alpha Website March 11, 2024)
The stock is now trading for about half of the price it was at right after the spinoff. It was actually worse before shareholders received the news that construction would resume with an expected completion date in the second quarter of the current fiscal year. But the stock price response to that announcement a few months back (as shown above) did not come close to making up for the losses since the spinoff.
Debt
One of the reasons for this is the debt laden balance sheet.
Equitrans Midstream Debt Due Schedule (Equitrans Midstream Fourth Quarter 2023, Earnings Conference Call Slides)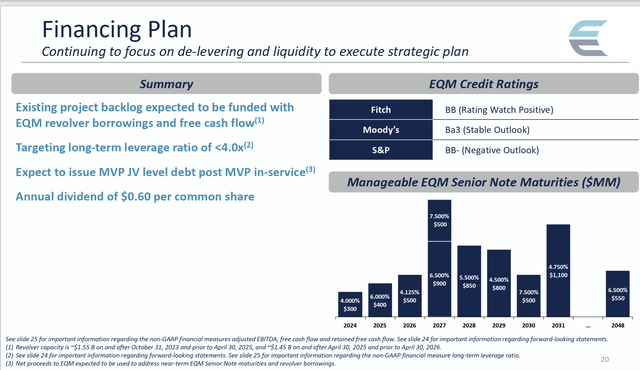
Even with the expected income from the pipeline, the amount of debt shown above likely means that it will be a while before there are any dividend increases.
Anytime a project such as the Mountain Valley Pipeline gets delayed, then sooner or later, the debt market becomes too costly to finance the delay. That means money that might have gone for dividends now needs to finance the project itself. Furthermore, with a debt schedule like the one shown above, it could be some time before an independent Equitrans Midstream could even think about a dividend increase.
Throughout all of this, the common stock price is unlikely to go anywhere.
EQT Benefits
EQT Corporation is a much stronger company as it is investment grade. One of the reasons for the combination is that EQT will likely be able to lower its transportation costs. The company will also be able to transport natural gas out of the oversupplied Marcellus Basin. Equitrans Midstream shareholders would benefit quite a bit as shareholders of the combined company, and they would likely benefit sooner.
The concerns of EQT and its partners may make dividends not as important as earnings. Therefore, as a private company, the deleveraging would likely be the priority with cash flow to the partners in the future.
Clearly, the debt due schedule shown before indicates that the debt needs some work to be done. Debt needs to be repaid and debt due needs to be extended out. That could probably be an easier task with strong joint venture partners rather than as a public company that needs to pay a dividend.
Equitrans Midstream Projected Adjusted EBITDA (Equitrans Midstream Fourth Quarter 2023, Earnings Conference Call Slides)
One of the untold benefits of the EQT offer is that EQT is making a market offer for Equitrans and therefore effectively does not pay for all the extra costs incurred to build the pipeline. EQT effectively pays for what the midstream assets are worth to the current market. Remember the EQT stock price dropped on the announcement. Therefore, any premium is likely forgettable. The shareholders have already paid for what turned out to be a boondoggle of a project.
As shown above, the annual incremental EBITDA is nothing close to what is needed for a pipeline that is estimated to have cost roughly $7.5 billion (this is more than some other estimates I used before). Even taking into account that Equitrans only has an interest of roughly 50%, there is no way to make that additional EBITDA figure enough to justify the pipeline at its final cost. It is going to be a while before price increases justify the MVP pipeline.
More Care Needed
Management is expressing an interest in doing an add-on project. But a whole lot of care is needed to make sure the same thing does not happen to the additional projects as happened to the MVP project. This is something that may get delayed or even cancelled after the MVP experience if there is even a hint of trouble early on.
Equitrans Midstream Southgate Pipeline Proposal (Equitrans Midstream Fourth Quarter 2023, Earnings Conference Call Slides)
This is something that management proposed due to a demand for the pipeline. But demand is not the only thing to consider. What happened with MVP is management did not take into account all the factors. The main factor included the success that opponents had in court against the MVP project.
I have long maintained that necessary interstate pipeline face considerable challenges. Most of them happened in one project. But when a company decides whether to build a pipeline, it has to take into account all things (even politics) to accurately gauge a chance of success. That is going to be very important with this proposed project.
Summary
Equitrans finally got the Mountain Valley Pipeline [MVP] completed. But the finances took quite a hit in the process as did the share price. Now that the pipeline is complete and likely to begin operations relatively soon, this pipeline could prove to be a very valuable piece to EQT in the future.
The lesson for investors is that not every project for which there is demand can be completed at a low enough cost. Some risk factors are qualitative in nature. An evaluation error, as was the case here, can be very costly. Clearly the market does not value the cost overruns that shareholders had to finance.
As EQT shareholders, the Equitrans shareholders are likely to benefit sooner as EQT will save on transportation costs as the owner and operator of the pipeline. EQT also benefits by getting its gas away from the oversupplied Marcellus Basin.
While this brings an end to a very long-suffering situation for investors, it also teaches a very important lesson about profitable projects. It is probably one that both investors and management will not forget for a very long time.
Editor’s Note: This article discusses one or more securities that do not trade on a major U.S. exchange. Please be aware of the risks associated with these stocks.
Credit: Source link